

BIOTECH man LONGTERM FOCUS many positions-also trade around my CORE holdings my opinion only do your own research with me
Joined September 2015
- Tweets83K
- Following652
- Followers44.5K
- Likes50.8K



Pinned Tweet
Wonderful Day for me. - celebrating 25 GREAT years with my WIFE & best friend today. Best decision I ever made - happy #anniversary to my WIFE ❤️❤️


Tomorrow 23 year anniversary +8 years of dating -like @SheffStation I started young 😃 MY WIFE best #LONGTERM Decisions I ever made ❤️❤️❤️ xitter.cf/tgtxdough/status/78728…

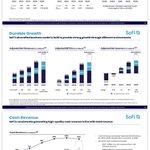
$SOFI - major sentiment change for LONGS/SHORTS with that statement "I now have as much confidence in our ability to drive durable growth in a high-rate environment as I do in a low-rate environment." -- Anthony Noto

Most important quote from the $SOFI call:
"I now have as much confidence in our ability to drive durable growth in a high-rate environment as I do in a low-rate environment." -- Anthony Noto
You absolutely love to hear it.
dough retweeted

$SOFI CEO Anthony Noto's full CNBC appearance following strong Q3 2026 earnings.
$ZURA Wedbush would be 'aggressive buyer' ahead of key Q4 catalyst

$ZURA Pitch Addendum:
This is the first time for me doing this - adding a section discussing some feedback on the pitch at the very bottom/end of the pitch document. The main reason I share these is to get my thoughts out there so that I can field feedback. So, why not update the document to dig deeper into the discussions that the initial diligence triggers?
Scroll to the bottom if you want to read some updated thoughts based on the $ZURA feedback to date, or just ctrl+F "Pitch Addendum"
docs.google.com/document/d/1…
$TGTX - market & many investors long/SHORT still not digested the implications of $TGTX having Q3m SUBq that can be given at home

The two key charts from the $TGTX subq dosing trial. The AUC for the every 3 month dose is numerically modestly higher than the current IV every 6 months, and injection site reactions were extremely low and completely absent after the second dose. This is undoubtedly going to be a several billion dollar product. They have a clear advantage here over monthly Kesimpta, and pricing is very favorable for both the company and payors (avoids the high infusion charges).


$COGT PDUFA upcoming - DATA continue to impress Of patients randomized the control arm of PEAK, 61% crossed-over to bezu + suni: 148 of 209 control patients (71%) had progressed
on sunitinib by the data cut, and 128 crossed over to the combination (61% of the control arm; 86% of those who progressed). In these 128
crossover patients, median PFS was 7.4 months relative to median of 5.7 months of PFS these patients had on PEAK control arm; ORR was
29.7% (n=38) vs. 20.3% on sunitinib (n=26). In the post-oral discussion, the discussant suggested that the data favor using the combination
earlier, given the PFS of 7.4 months after crossover vs. 16.5 months in the second line, but the discussant also highlighted that the crossover
was non-randomized, and enrolled patients who progressed early on sunitinib (mPFS 5.7 vs. 9.2 months for the full arm).
COGT also disclosed treatment duration by arm. Median treatment duration was 61.4 weeks (~14.1 mo) for patients randomized
to the combination, compared with 23.9 weeks (~5.5 mo) after crossover (vs. 42.4 weeks (~9.8 mo) on sunitinib monotherapy).
Compared with the randomized combination arm, crossover patients had fewer serious side effects and needed fewer dose cuts, with lower
rates of Grade 3+ treatment-related AEs (39.1% vs. 71.6%), dose reductions (25.8% vs. 55.9%) and treatment-related discontinuations (2.3%
vs. 7.4%). All-grade liver-enzyme increases (ALT/AST) were only modestly lower (46.9% vs. 56.4%) despite less than half the time on drug.
$COGT Stifel Investment Thesis
COGT's bezuclastinib put up a historical PFS in the Ph3 PEAK study of bezuclastinib 2L GIST which has driven M&A speculation. COGT
has also presented positive pivotal data in advanced and non-advanced systemic mastocytosis (AdvSM, non-AdvSM) expected to support
approval of bezuclastinib as a second-mover in both SM indications. model ~$2.5B in global revenue for bezuclastinib by 2035 (inclusive
of non-AdvSM, AdvSM, and GIST). value COGT at ~4x EV/5yr forward sales, which is in line with recent biotech M&A (~4-5x deal
value/5yr forward sales).
$AVR TCT Innovation 3: Emerging Concepts and Innovations in TAVR
Sunday, November 1, 2026, 10:45 AM - 12:15 PM PST
Room: Innovation Theater
The Novel Biomimetic Medium DurAVR THV Balloon-Expandable Valve (Anteris): First Report of the 30-Day Clinical and Hemodynamic Outcomes
Presenter: Azeem Latib, MD
2) TCT Innovation 15: Live Case-in-a-Box Innovation: Emerging TAVR Technologies
Tuesday, November 3, 2026, 8:35 – 9:35 AM PST
Room: Innovation Theater
$AVR Kaleidoscope - Anteris Announces Upcoming Data Release for Medium-Size DurAVR THV from EMBARK Study at TCT 2026 api.kscope.io/v2/documents/v…
$BHVN LR PT $26 Don’t Be Surprised If
This Drug Gets Approved Bottom Line: It’s difficult not to be incrementally more positive
about this situation after speaking with management. It just
sounds like the recent FDA swerve has rejuvenated the
likelihood that this NDA package will finally get approved.
Mgt has submitted 4-year data and additional
supportive analyses with the resubmitted NDA and is
seeking a broad label with SCA based on its discussions
with the FDA
$BHVN short interest of 19.05 million shares sold short, representing 14.63% of the public float
$RLAY GUGG caught up with MGT guided updates for vascular anomalies (VA) &1/2L mBC,YE26. VA: consistency vs. prior update is
likely to be a success. While base case remains an accelerated approval (AA) for PROS, an alignment for AA inclusive of LM would represent significant
upside.see a line of sight toward $1B for this indication. On 1/2L mBC, mgmt is likely to provide: (1) an enrollment update for its Ph 3 ReDiscover-2
study of 2L+ PIK3CAm HR+ mBC; (2) an outline for the design of zovega + atirmociclib (PFE) + ET triplet in 1L HR+ mBC. To-date Ph 1b data confirms
high dose intensity for all medicines, crucial for the multi-year 1L treatment durations. Additional Ph 1/2 triplet data during 1H27 should de-risk the regimen.
Bottom line, with three (two meaningfully de-risked), commercially lucrative shots on goal, we believe RLAY has the potential to significantly exceed $3B in
peak sales with an unencumbered, strategically important asset.
$DYN RJ Risk-Reward Too Good to Ignore + Deep Dive on DYN's Z-Ros and
Fab 4 (DMD) Programs; TP to $41
estimate z-ros U.S.
accelerated approval can support a ~$500-$700M U.S. peak revenue opportunity, while success
in the ongoing Ph3 FORZETTO trial could increase this peak to ~$1.5-2.3B on expanded U.S.
penetration and unlocking key global markets

$NVS is now guiding $4B+ peak sales for remibrutinib in urticaria ALONE. This asset is single-handedly carrying their entire pipeline. MS another win and HS is still a black box, Ph3 readout is imminent

$COGT Stifel Investment Thesis
COGT's bezuclastinib put up a historical PFS in the Ph3 PEAK study of bezuclastinib 2L GIST which has driven M&A speculation. COGT
has also presented positive pivotal data in advanced and non-advanced systemic mastocytosis (AdvSM, non-AdvSM) expected to support
approval of bezuclastinib as a second-mover in both SM indications. model ~$2.5B in global revenue for bezuclastinib by 2035 (inclusive
of non-AdvSM, AdvSM, and GIST). value COGT at ~4x EV/5yr forward sales, which is in line with recent biotech M&A (~4-5x deal
value/5yr forward sales).
$ZURA •TibuSHIELD topline data in hidradenitis suppurativa (HS) remains on track for Q4 2026; enrollment completed with 247 participants randomized, exceeding target
•TibuSURE topline data in systemic sclerosis (SSc) remains on track for H1 2027; enrollment completed with 91 participants randomized, exceeding target
•NEXUS-PMR, a Phase 2 study evaluating tibulizumab in polymyalgia rheumatica (PMR), remains on track to initiate by year-end 2026
•Cash and cash equivalents of $187.7 million as of September 30, 2026, which is expected to fund planned operations through at least the end of 2028
$ZURA Zura Bio Reports Third Quarter 2026 Financial Results and Recent Corporate Updates | Zura Bio Ltd investors.zurabio.com/news-r…
$ZURA Zura Bio Reports Third Quarter 2026 Financial Results and Recent Corporate Updates | Zura Bio Ltd investors.zurabio.com/news-r…
$KNSA ARCALYST® (rilonacept) Q3 2026 net product revenue of $286.0 million, representing ~58% year-over-year growth –
– ARCALYST 2026 expected net product revenue increased to $1.045 - $1.050 billion –
– KPL-387 pivotal Phase 3 data expected in 2H 2027 –
– Conference call and webcast scheduled for 8:30 am ET today –
$SOFI nice to hear for guidance good news is @SoFi is executing as well as we ever have. I now have as much confidence in our ability to drive durable growth in a high rate environment as I do in a low rate environment.

These are strong results in any environment, but they're even more remarkable when considering how the macro environment in 2026 has unfolded. Nine months into the year, the environment looks different than what we expected.
Our original 2026 guidance assumed two rate cuts. Instead: one rate hike and today we are positioned for two more this year.
The good news is @SoFi is executing as well as we ever have. I now have as much confidence in our ability to drive durable growth in a high rate environment as I do in a low rate environment.
$PCVX Salim —Worth noting, $PFE's own slides state that "modeling predicts ≥22/25" ST non-inferiority (i.e., implies base case ~three ST misses) in a Ph3 trial. should help investor confidence in VAX-31 infants.
$PCVX Mizuho Outperform PT $163.00
IDWeek ==> PFE PCV25 Infants Forest Plot Implies Likely Some Ph3 ST Misses; Good for PCVX