

Author: The Investor's Mind, Framing Business Uncertainty | https://xitter.gq/t.co/B2IsdWeoo8 | https://xitter.gq/t.co/bDKgZLuYEH
Greener outside of London
Joined November 2016
- Tweets31.5K
- Following231
- Followers161K
- Likes39K





Pinned Tweet
When everyone is pumping the CDMO narrative, don't ask who is a CDMO. Ask who would still be a CDMO if the word disappeared from the presentation or annual report ...


Hi @MaulikM07457284 – I’ve dropped a note to your IR team. Look forward to the possibility. Many thanks.
#LaurusLabs is often measured by 125 projects, a 34% margin and 1.4x peak asset turns.
All three may be measurements of the old Laurus.
A free essay on why the old ruler may no longer measure the mountain.
No advice. No recommendation. Just a perspective. A different frame for thinking about the business.
Read the disclaimer at the bottom of the essay
antifragilethinking.substack…

Someone mocked me when #LaurusLabs was in a valley, with EBITDA margins falling from 32% in 2021 to around 15% a few quarters later.
The day Laurus announced poor results, they climbed onto their soapbox and asked:
“Where is the party tonight? London or Mumbai?”
All I have to say is this:
There is a party globally. In many small cities and towns. And there will be many more.
Ahmednagar. Surat. Savli. Hyderabad. Bengaluru. Vizag. Nagpur. Chennai. Pune. Kanpur. Jaunpur. Lucknow. Mumbai. Kashmir to Kanyakumari. London. Cities across the US and Europe. The Nordic region. ANZ to LatAm.
And for many families, this will mean something far more meaningful than a stock price.
A child’s education. A new home. Retirement. A holiday. A little more freedom. A little more security.
The people who quietly stayed through the valley may have their own parties to attend.
The real party is not on a trading floor. It is in the lives that get changed.
#LaurusLabs in “Positive Hydra” mode.
Credit not to the soothsayer, but to the soul in the game. Dr Satya and the team have worked tirelessly to build what is now unfolding. More to come...
They take 30% of the total value created.
The remaining 70% belongs to shareholders.
This was recorded (31:00) 👇
youtu.be/trvtbF1P6uQ?list=PL…

It is a blessing from the universe to have the opportunity to interact with some of the finest minds in the industry. I cherish every such interaction and hold it with the deepest respect and gratitude.
The Machine Behind the Molecules
antifragilethinking.substack…
$SDGR | Schrodinger


$SDGR surges another 15% today. US biotech and cybersecurity space have been good at an aggregate level in 2026.
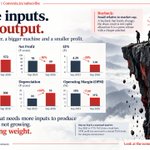
Skip the buyback theatre. Sales grow 6% a year; profits shrink 11%. That’s not a growth story. It’s a slow leak. Call it what it is.

The best of Syngene is still ahead, but take it one quarter at a time. Do not confuse hope with proof.
Everything they said on today’s Q2 FY27 earnings call sounded honest and grounded, without the usual corporate spin. That is brutal honesty, and I appreciate it.
May they have the strength to keep going, and a fair share of luck too.
antifragilethinking.substack…

But here’s what I’d tell my younger self: the scraped knee was the lesson, not the strategy.
For every trader who lost 90% and came back, many never did. You don’t hear from them. That is the idea behind “Silent Evidence”, the last heuristic chapter of The Investor’s Mind: we overlearn from survivors and underlearn from those who disappeared.
Tinker, experiment, make mistakes, but keep them small enough to survive. Fall early. Fall small. Learn fast. Ghutne chilne do, gardan mat katne do.
Antifragile Thinking retweeted

Diwali at 10 Downing Street in London 🪔 🪔 🪔
Prime Minister Andy Burnham and his wife Marie-France van Heel lit diyas and joined the Indian diaspora to celebrate the spirit of Diwali.


Concord Bio, Syngene and Piramal Pharma all reported better numbers. But a good quarter is not proof of a good system. The more interesting question is what the numbers still don’t reveal.
New post 👇
antifragilethinking.substack…


Always .... if your horizon is extremely short, start with the price, not the story.
Unimech Aerospace
Syngene
Piramal Pharma
I have no view on the stock per se. Your risk capital is yours. Your judgement is yours. So are the consequences!

If a framework cannot survive contact with a different industry, it is not a framework. It is a narrative wearing a framework’s clothes.
Can the same framework be applied to Divis, Laurus, Anthem, Sai Life, Shilpa Medicare, Aether Industries, Unimech, Sansera and Sona Comstar?
A static snapshot tells you what the business is. Rate of change tells you what it is becoming.
That is where the real test begins. Old engines must be replaced. Diversification must show up in the numbers. And what management says today must survive contact with FY28.
If the framework cannot travel, it is not a framework.
Acutaas 👇
antifragilethinking.substack…

Joined Syngene’s Q2 call at 3:30 am UK time and had a meaningful exchange with Siddharth Mittal on how the new team plans to keep programmes from discovery through to commercial supply.
Worth a listen.
Thank you, @kiranshaw, for leading from the front.
(Disclosure: Family owns shares. Not investment advice.)
Acutaas Chemicals trades at ~19x sales.
You're not buying today's business. You're buying its ability to keep improving faster than the valuation becomes demanding.
"3 FY28 paths" and the hurdle every quarter must clear is here:
antifragilethinking.substack…
Not investment advice!


IF 700: I'd buy
ELSE IF: 600 - I'd buy more
END
Buridan's Donkey lens
Buridan's Donkey is a special lens. Not a tip/advice for mass consumption. Never clone. Invested in सोना since Sep 2025

Bernstein on Sona BLW
OW, TP Rs 850
Q2 Revenue growth (+35% YoY) reflects several levers coming through together: traction motors gaining share, strong recovery in differential assemblies, & suspension motors scaling in China
Business enters H2 with a broader base of growth & further programs to ramp
While declining percentage margins will understandably attract attention, don’t think earnings case require a return to historical peaks while revenue opportunity continues to expand
Management has, however, retained its 23-25% EBITDA margin framework
CITI on Sona BLW
Buy, TP Raised to Rs 960
Strong beat in 2QFY27 results, driven by a robust revenue growth.
Suspension motors, traction motors and differential assemblies segments saw strong trends.
Demand outlook remains positive, with tailwinds for global EVs as well as domestic E2W sectors .
New products are likely to result in Sona’s growth being higher than underlying industry’s.
Orderbook trends improved with (Rs251bn now vs Rs240bn as of 1QFY27 end).
That said, margins are likely to remain under pressure, given 1) severe material cost inflation, 2) increase in freight rates, & 3) mix shift towards 2W traction motors (low margin).
Kotak Inst Eqt on Sona BLW
Sell, TP Rs 700
2QFY27 EBITDA came in 9.5% above estimates due to a better-than-expected revenue print
Expect revenue growth to accelerate, owing to
(1) recovery in differential assembly business,
(2) strong momentum in traction motors and railway segments
(3) incremental opportunity in differential gears.
Beyond current products, expect Physical AI & BEV traction motor opportunity to drive medium-term growth prospects
Valuation remains expensive, which drives SELL
JPM on Sona BLW
UW, TP Rs 600
2QFY27 a beat vs expectations.
Revenue of Rs 15.5bn (+35% YoY) was 7% above JPMe, while EBITDA of Rs 3.6bn (+23% YoY) was +5% vs JPMe
EV revenues grew 129% YoY due to a combination of:
1) normalisation of differential assembly revenues in North America,
2) traction motor growth in Indian 2W/3W EVs, and
3) suspension motors ramp-up in China
Raising FY27-29 revenue and EBITDA forecast by 9-13% and 5-10%, respectively
This should drive an EPS CAGR (FY26-29) of 23%, but stock is already trading at 47xFY28 P/E
@CNBCTV18News @sudarshankr
Antifragile Thinking retweeted

Was invested around ₹350 when hardly anyone believed. The thesis was never about the quarter: deep science, customer relationships, and a technocrat promoter who compounds capability.
You'd know the pattern from Laurus.
Experienced Ms Soumya's empathy and attention to detail firsthand at CPHI Milan this year. Onwards and upwards. Best wishes from a long-term shareholder with meaningful skin in the game.

Proud moment for Laurus Labs! Ms Soumya Chava has been honoured with the Business Today Most Powerful Women in Business Award 2026, recognising her leadership and contribution to business excellence.#LaurusLabs #BusinessToday #WomenInLeadership