

Founder | @ALSTOCKTRADES // @NeuroSurgGlobal The consensus is always late.
Wall Street, New York
Joined December 2017
- Tweets3.9K
- Following90
- Followers3.5K
- Likes7K




Pinned Tweet
I've been fighting this whole time with my hands tied behind my back. Now I am unleashed.
My mind, the very thing they mocked, just built a public portfolio worth $1.475 million with my
company valued over $50 million.
You're not just going to see my brain power. You're going to feel it rumble through the ground
beneath your feet. $CLOV $OPEN $SOFI

$CLOV
GOING LIVE!

Clover Health $CLOV Stock: The Consensus Is Always Late xitter.gq/i/broadcasts/2nQBKLdLy…

How Many of Your Publications Would Exist If No One Required Them?
Count the papers on your CV that would exist if no accreditation form had asked for them. Whatever number you land on, the distance between it and your total is what this article is about, and you do not have to take my word for the size of that gap, because in 2024 the past chair of the committee that writes the scholarship rules for family medicine residencies published the numbers himself. I came to this after a week of reading René Girard, who spent decades on a single idea until it explained desire, violence, and religion at once, and against that standard the modern academic department is hard to look at.
Most of what gets published in medicine today exists because a requirement says it must. The American College of Surgeons now requires a Level I trauma center to produce at least 10 trauma related research articles in peer reviewed indexed journals each verification cycle, with at least three written by trauma surgeons and three from other disciplines, and that cycle runs three years. The ACGME requires every residency program to demonstrate faculty accomplishments in at least three scholarship domains, and one of those domains is satisfied by systematic reviews, review articles, textbook chapters, or case reports. Family medicine goes further and expects residents to complete two scholarly activities, at least one of them a quality improvement project. Read the rules closely and you will notice what is missing. None of them asks what a paper changed. They ask whether it exists.
The output follows the incentive with a precision that should embarrass everyone involved. Grant Hoekzema, past chair of the ACGME Review Committee for Family Medicine, and Warren Newton of the American Board of Family Medicine analyzed the scholarship data that programs report to the ACGME every year. Between 2016 and 2021, PubMed articles went from 505 to 3,617, conference presentations went from 4,673 to 13,842, and publications per faculty member rose from 0.03 to 0.21, an increase the authors call out of proportion to the growth in programs and faculty. Their explanation is the shift that made scholarship a core requirement rather than a detail. Nobody believes family medicine learned seven times more about medicine in five years. The rule changed, and the count followed.
The part that should end the argument is in their own limitations. The authors acknowledge the numbers may be “overinflated to satisfy accreditation requirements,” and that assessing the quality or impact of the publications and presentations was not possible. The people who wrote the requirement are telling you that the measurement may be fiction and that nobody checked whether any of it mattered.
The trainees have read the rules the same way. In a 2024 national survey of family medicine program directors, more than half reported that fewer than a quarter of their residents did any scholarly activity beyond the ACGME minimum. When a system defines the floor, the floor becomes the ceiling, and that is not a character flaw in residents. It is the only rational response to a rule that counts.
Everyone inside this system is behaving rationally, which is exactly why it will not fix itself. The resident needs lines on a CV, the attending needs a promotion packet, the program needs its accreditation, and the hospital needs its designation. In his 2014 letter to Berkshire Hathaway shareholders, Warren Buffett named the ABCs of business decay as arrogance, bureaucracy and complacency, and warned that when these corporate cancers metastasize even the strongest companies can falter. His antidote was extraordinary delegation of authority, which means trusting the people who own the outcome. Academic medicine has done the opposite. The checklist is what central authority looks like once it stops trusting judgment.
In physics you can expend enormous energy and produce zero displacement, and a career built on these requirements can look exactly like that from the outside. People call it a growth mindset because they are always busy, but a system designed to produce the same unit of output every cycle, verified by a form, is the definition of fixed.
The real scholars are still out there, and they are rare for a reason: nothing in this structure selects for them. Girard never needed a verification cycle to tell him what to think about. When the people doing the counting are the people being counted, the number only goes up, and a rising number that measures nothing is what we have agreed to call academics.
Until Next Time,
Albert Alan, MD

$CLOV
Soon this will be more applicable than ever before.


$CLOV
Hardware’s share of the US economy just hit its highest level since the fourth quarter of 2000, the exact quarter the dotcom buildout peaked, and the last time that happened it took software seventeen and a half years to catch up. I pulled the raw Bureau of Economic Analysis data behind this ARK chart and ran the numbers myself, because the pattern underneath it is the single most useful framework I know for figuring out where the next decade of value will show up.
The chart compares two kinds of business investment as a share of nominal GDP. The purple line is information processing equipment, the physical layer: computers, servers, networking gear, the wiring. The green line is software, the layer that actually puts those machines to work. The data goes back to 1959, and for 237 straight quarters, through the first quarter of 2018, hardware led. Every dollar of software still needed a bigger dollar of hardware underneath it.
The 1990s were a hardware story before they were anything else. Carriers laid the fiber, companies bought the routers and stacked the servers, and hardware investment climbed from 2.08 percent of GDP in early 1991 to 2.91 percent in the fourth quarter of 2000, which is still the all time record. Then the bubble broke. Hardware spending fell 24 percent in two years, and its share of the economy has never returned to that peak, not even now.
Software did not die in the crash. It waited. The glut of cheap fiber and cheap servers left behind by the bankruptcies became the foundation for everything that followed: YouTube in 2005, Amazon Web Services in 2006, Netflix streaming and the iPhone in 2007, and the entire software as a service industry after that. Software’s share of GDP bottomed at 1.34 percent in 2003 and then climbed slowly and steadily for fifteen years until it finally crossed above hardware. That crossover happened in the second quarter of 2018. In the first quarter of 2018 the two lines were in a statistical tie at 2.005 percent versus 2.001 percent, and by the April to June quarter software was ahead at 2.04 percent against 1.97 percent. It stayed ahead for 31 consecutive quarters.
So here is the number that matters. From the hardware peak in the fourth quarter of 2000 to the software crossover in the second quarter of 2018 is 70 quarters, seventeen and a half years. Start the clock at the Nasdaq top in March 2000 instead and it is eighteen years. Either way, the application layer needed the better part of two decades to grow into the infrastructure that had been built for it.
That streak ended this year. In the first quarter of 2026 hardware passed software for the first time since 2018, and by the third quarter hardware investment was running at an annual rate of 934 billion dollars, 2.83 percent of GDP, against 831 billion for software. Hardware spending is up 41 percent year over year. Software is up 9 percent. The four largest hyperscalers spent about 410 billion dollars on capital expenditures in 2025 and have guided to roughly 700 billion for 2026. We are watching the same movie: an infrastructure layer being built faster than the application layer can absorb it.
The question worth asking is how long the catch up takes this time, and the chart itself gives you the answer. The 1990s buildout added 0.83 percentage points of GDP share over almost ten years. The AI buildout has added 1.13 points in three. That is more than four times the pace, so assuming this cycle runs merely twice as fast as the last one is a conservative assumption. Cut the seventeen and a half year lag in half and you get eight years and nine months. If hardware’s share peaks sometime in 2027, which is what current capex guidance points to, software crosses back above hardware in early 2036. If it already peaked this quarter, 2035. If this buildout runs as long as the 1990s one did at double speed, 2037. My base case is 2036, inside a window of 2035 to 2037.
Two things are different this time, and both argue for speed. Fiber laid in 1999 had a useful life of twenty to thirty years, so the infrastructure could sit dark and wait a decade for applications. The GPUs being bought today depreciate in roughly five to six years, which means the hardware layer cannot afford to wait, and the companies buying it are under enormous pressure to find software that pays for it. At the same time the price of intelligence is collapsing faster than the price of bandwidth did after 2001, with the cost of running a given model falling roughly tenfold per year by a16z’s estimate. Cheap bandwidth gave us streaming video. Cheap intelligence will give us something larger.
The economics of the lag are well understood, even if almost nobody applies them to this chart. Carlota Perez described every technological revolution as an installation period, in which financial capital overbuilds the infrastructure and a bubble forms, followed by a crash, followed by a deployment period in which the real gains show up in applications. Erik Brynjolfsson calls the same phenomenon the productivity J curve: tangible investment shows up first, intangible investment in software and new workflows comes later, and measured returns dip before they climb. Both frameworks reach the same conclusion. The money made during installation goes to whoever builds the infrastructure. The money made during deployment goes to whoever owns the applications people cannot live without.
This is where healthcare comes in, and where I have a front row seat. Healthcare is roughly 18 percent of US GDP, more than five trillion dollars a year, which makes it the largest single application layer in the economy. The data is digitized, the interoperability standards are live, and the cloud compute is sitting there waiting. What is missing is software that turns all of that into a better decision at the moment a doctor is sitting with a patient.
That is exactly what Clover Health built with Clover Assistant, and what it now sells to other payers and providers through its subsidiary, Counterpart Health. Clover proved the software on its own Medicare Advantage members first, the same way Amazon built its cloud for itself before renting it to everyone else. Its flagship PPO just earned a 5 Star rating for payment year 2028, the largest 5 Star PPO contract in the country, and it has ranked number one nationally among comparable PPO plans on core HEDIS quality measures three years running. The insurance business is on track for its first full year of GAAP profitability in 2026, with 62 million dollars of net income through nine months, revenue up 53 percent, a benefits expense ratio of 91.1 percent, 513 million dollars in cash and no debt. It turned free cash flow positive in 2024 and net income positive in 2026, the sequence I call the Triple Dragon.
Counterpart is the application layer inside that company. Counterpart Assistant uses Google Cloud’s Vertex AI and large language models, which means it is literally renting the purple line in this chart, and it is deployed inside physician workflows at organizations like Duke Connected Care. Clover’s published data show that returning members whose primary care doctors use the tool carry a double digit lower medical cost ratio, and that those doctors post 33 percent higher receipt of hospital discharge information and 11 percent higher post discharge medication reconciliation. Management’s stated goal is to serve as many people through Counterpart as through Clover’s own plans, and the CEO said this week that they are making strong progress toward it.
I want to be careful, because the dotcom analogy cuts both ways. Most of the application companies of 1999 never lived to see 2018, and the ones that did shared three things: real cash flow, a distribution channel they controlled, and proprietary data the infrastructure providers could not copy. Clover has not broken out Counterpart’s revenue yet, Medicare Advantage is a politically exposed business, and a 2001 style capex bust would hit every name attached to AI. But the lines in this chart have crossed exactly twice in 67 years, and both crossings told the same story: the infrastructure gets built, the bubble gets blamed, and then the applications quietly take over the economy. In medicine, Counterpart is one of the very few public ways to own that layer today.
The consensus is always late. It was late to software in 2003, and it will be late to the AI application layer in 2027. The chart already told you when to start paying attention.
Albert Alan, MD
I am not a licensed financial advisor. This post is educational content, not investment advice. Do your own research before making any financial decision.

$CLOV
Just wait until the market catches up to the application layer of AI that can eat up a whole industry.
"THIS IS 10X PROBABLY 50X BIGGER THAN DOT COM"


$CLOV
love how Vivek is teaching about the $VIX my hats off to you. Educating people is the highest calling. Thank you for sharing your experience.
There have been 10 different instances since October 2008 that the NASDAQ fell by 5.5% or more in a single trading day.
The soonest an IPO raise of $1 billion or more happened after one of those days was 79 days, Warner Music Group, raising ~$2 billion approximately 11 weeks after the March 16, 2020 12.3% NASDAQ drop.
Anthropic is reportedly raising approximately $100 billion in the next few weeks. It would be the most unbelievable capital markets achievement ever given the above.
I'm not sure many portfolio managers will want to take that large of a risk so close to year-end.
If you don't know what the VIX is, it matters a lot leading up to an IPO.

$clov UBS adjust PT to $5.50 from $5
marketscreener.com/news/ubs-…

What does it take to enable humans to engage with AI agents about their health insurance?
@CloverHealth found out, with voice agents facilitating how members engage with their health plan, including care check-ins, navigating plan benefits and instant access to member inquiries, and transferring to a Clover Health team member whenever human support is needed.
Head of Strategy for the Office of the Chairman, Cameron Pringle, joins @ashleyekramer on Nov 11 to explain how.
Apply to join: elevenlabs.io/summit/new-yor…

$CLOV
Democrats just won the midterms on affordability, and their first move was to threaten the one industry holding up the stock market.
When I say Wall Street, I mean the hedge funds, the big banks, the asset managers, and the trillion dollar tech giants whose data center spending is the reason your index fund has climbed for four straight years. Your 401k is not separate from them, it is built out of them. Every dollar in your retirement account is a share of the machine you just promised to shut down.
Here is how this works. You come for the data centers, we sell, the market drops, and the 401k of every voter who trusted you gets smaller by the hour. People who feel poorer do not feel like anything got more affordable, and affordability is the only reason you were handed power. We never had to beat you in a vote. We just had to hit the sell button.
Consider this a vaccine before you take office. We will throw this entire economy into a recession to prove a point, and you will be the ones standing there taking the blame when it lands. Your voters can't fix it, you can't fix it, and the people who can never needed an election to get their seat.
So bend the knee. You work for us, you always did, and today was the reminder.


$CLOV
GOING LIVE!
Clover Health $CLOV STOCK Q3 2026 | PART 1 xitter.gq/i/broadcasts/2EmrKaaqK…


$CLOV
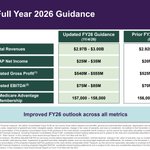
Clover Health Q3: revenue up 53% to $759M, first profitable year ahead (YTD net income $62M), Medicare Advantage members up 45%, 5 Star PPO rating, and raised 2026 guidance across every metric.
$CLOV
Clover Health Q3: revenue up 53% to $759M, first profitable year ahead (YTD net income $62M), Medicare Advantage members up 45%, 5 Star PPO rating, and raised 2026 guidance across every metric.


I love @AOC - she will be President one day. I’ll be there for her when she’s ready.
$CLOV
"The Superinvestors of Graham & Doddsville all lost money 3 years in a row during the mid-1970s."
All of this will soon make sense.

Cassandra Unchained is in its anniversary month. What this means is we have been around for just 1 year. 1 year is a useless measure of investment skill. It's not close to long enough.
The Superinvestors of Graham & Doddsville all lost money 3 years in a row during the mid-1970s. Another crop of value investing big guns were left for dead by March 2000. 2026 has been the worst year for consumer sentiment on record, going back to 1952.
We are dealing with extremes, and have been for some time. We should all cut ourselves some slack for what has gone right and wrong over the last year.