

India First | Investing | FIRE | All Views are Personal | No Recommendation.
📖 Learning Hub 👉🏻
Joined March 2014
- Tweets41.2K
- Following517
- Followers37.6K
- Likes84.4K




The Indian Investor retweeted

ICICI PRUDENTIAL LARGE & MID CAP FUND – OCTOBER 2026 PORTFOLIO DISCLOSURE 🚀
The complete portfolio holdings, stock-wise allocation, quantity, market value and percentage of NAV are provided in the attached image below 👇
▪️ A detailed look at the fund's latest portfolio composition, major stock holdings and sectoral exposure.
▪️ Useful for tracking which companies and sectors a leading mutual fund is allocating capital to.
Disclaimer: Shared for educational and informational purposes only.


The Indian Investor retweeted
MOTILAL OSWAL MIDCAP FUND – OCTOBER 2026 PORTFOLIO DISCLOSURE 🔥
The complete portfolio holdings, stock-wise allocation, quantity, market value and percentage of AUM are provided in the attached image 👇
Disclaimer: Shared for educational and informational purposes only. This is not an investment recommendation.


ABAKKUS SMALL CAP FUND – OCTOBER 2026 PORTFOLIO DISCLOSURE 🔥
The complete portfolio holdings, stock-wise allocation, quantity, market value and percentage of AUM are provided in the attached images 👇
▪️ A detailed look at the fund's latest small-cap portfolio allocation and stock holdings.
Disclaimer: Shared for educational and informational purposes only. This is not an investment recommendation.


The Indian Investor retweeted
2026 IPO COMPANIES SHOWING GOOD STRENGTH AND FUNDAMENTALS – STUDY & TRACK
▪️ Bonfiglioli Transmissions
▪️ Zetwerk Manufacturing
▪️ Indo-MIM
▪️ Aye Finance
▪️ Karamtara Engineering
▪️ Tonbo Imaging
▪️ EAAA India Alternatives
▪️ Dhoot Transmission
▪️ Steamhouse
▪️ Sonaselection
▪️ Sedemac Mechatronics
▪️ NSE
▪️ Rentomojo
▪️ Waterways Leisure
▪️ Prasol Chemicals
▪️ Xtranet Technologies
▪️ Symbiotec Pharmalab
▪️ Lalithaa Jewellery
▪️ Sahajanand Medical Technologies
These companies are worth keeping on the radar for further research and tracking. Focus on their business models, financial performance, growth prospects, competitive advantages, management quality and valuations.
Disclaimer: This list is for educational purposes only and is not a buy or sell recommendation.
HIGH RELATIVE STRENGTH STOCKS TO STUDY & TRACK 🔥🔥🔥
Laurus Labs
Lenskart Solutions
Coforge
MCX
Ather Energy
Sona BLW Precision
Gland Pharma
Cupid
Sai Life Sciences
Acutaas Chemicals
Sansera Engineering
Welspun Living
Diamond Power
Shadowfax Technologies
Lumax Auto Technologies
Shreeji Shipping Global
Pearl Global Industries
Saregama India
Sri Lotus Developers
SG Mart
Indo Count Industries
M B Agro Products
Unimech Aerospace
Steel Strips Wheels
Entero Healthcare
Neogen Chemicals
Krishna Phoschem
Tourism Finance Corporation of India
Timex Group India
Rolex Rings
Sambhv Steel Tubes
SG Finserve
Nitin Spinners
Yash Highvoltage
Shukra Pharmaceuticals
SBC Exports
Oriental Hotels
Ratnaveer Precision Engineering
M M Forgings
⚪ WHY TRACK RELATIVE STRENGTH?
Relative strength helps identify stocks outperforming the broader market or their respective indices.
▪️ Strong stocks tend to show resilience during market corrections.
▪️ They can attract buying interest when broader market momentum improves.
▪️ Look for sustained outperformance, strong price structures, volume confirmation and healthy consolidations.
▪️ Relative strength is a useful starting point for identifying potential leaders, but fundamental research and risk management remain equally important.
Disclaimer: This is a watchlist for educational and research purposes only. Inclusion does not imply a buy recommendation.

The Indian Investor retweeted
ALL 87 SME COMPANIES REPORTING STRONG SALES GROWTH IN H1 FY27 / Q2 FY27 TO STUDY🔥🔥🔥
The increase in sales growth (YoY) reported by these companies is mentioned below:
▪️ Kesar India – 554%
▪️ Gretex Industries – 503%
▪️ Vans Electroengineerings – 308%
▪️ Anawil Wire – 272%
▪️ Aptus Pharma – 240%
▪️ GRE Renew – 223%
▪️ Blue Water – 211%
▪️ Teamtech Formwork – 199%
▪️ Mach Travel Solutions – 182%
▪️ Bizotic Commercial – 172%
▪️ Sheetal Universal – 160%
▪️ B-Right Real – 159%
▪️ Prizor Viztech – 154%
▪️ Organic Recycling – 152%
▪️ Akiko – 138%
▪️ Innomet Advanced – 137%
▪️ Bai-Kakaji Polymers – 124%
▪️ Simca Advertis. – 124%
▪️ ACE Alpha Tech – 121%
▪️ Madhusudan Masa – 118%
▪️ Prime Cable Industries – 117%
▪️ TechD Cybersecurity – 114%
▪️ Savy Infra – 113%
▪️ Infinity Infoway – 106%
▪️ Purple United – 104%
▪️ Sathlokhar Systems – 100%
▪️ Chemkart India – 99%
▪️ Goldstar Power – 99%
▪️ Technocrats Plasma Systems – 97%
▪️ Kody Technolab – 97%
▪️ OBSC Perfection – 97%
▪️ Yash Highvoltage – 95%
▪️ Concord Control – 95%
▪️ GP Eco Solutions – 93%
▪️ Indo SMC – 92%
▪️ Chaman Metallics – 92%
▪️ Hoac Foods – 91%
▪️ Shivam Chemicals – 91%
▪️ Shreedhar Spinners – 90%
▪️ Monolithisch India – 88%
▪️ Cospower Engineering – 87%
▪️ HP Telecom – 85%
▪️ Shree Refrigerations – 85%
▪️ Aimtron Electronics – 83%
▪️ Utssav CZ Gold – 83%
▪️ Digilogic Systems – 83%
▪️ Fabtech Technologies Cleanrooms – 75%
▪️ Sunlite Recycling – 75%
▪️ Taurian MPS – 73%
▪️ Sugs Lloyd – 73%
▪️ V-Marc India – 73%
▪️ Jay Jalaram Tech – 69%
▪️ Parmeshwar Metal – 69%
▪️ Poojaa Precision Engineering – 68%
▪️ Laxmipati Engineering – 68%
▪️ B.R. Goyal Infra – 62%
▪️ Gayatri Rubbers – 59%
▪️ Forcas Studio – 56%
▪️ Aayush Art – 56%
▪️ Apsis Aerocom – 55%
▪️ Infinium Pharma – 54%
▪️ Connplex Cinemas – 54%
▪️ Msafe Equipments – 54%
▪️ Remus Pharma – 53%
▪️ Credent Connect N Care – 53%
▪️ Silkflex Polymer – 52%
▪️ Trident Lifeline – 50%
▪️ Unified Data – 50%
▪️ Admach Systems – 48%
▪️ Spunweb Nonwoven – 48%
▪️ Adisoft Technologies – 48%
▪️ Rajesh Power – 46%
▪️ Goel Construction – 45%
▪️ Effwa Infra – 45%
▪️ Macfos – 44%
▪️ Cryogenic OGS – 44%
▪️ Hi-Green Carbon – 43%
▪️ Parth Electrical – 42%
▪️ Danish Power – 38%
▪️ Patil Automation – 37%
▪️ Novus Loyalty – 37%
▪️ Monarch Survey – 36%
▪️ Brandman Retail – 35%
▪️ Shri Ahimsa – 32%
▪️ Petro Carbon – 32%
▪️ Vivid Electromech – 30%
Strong sales growth is worth tracking, but growth alone is not enough. Check profitability, cash flows, debt and valuations before making an investment decision.
📌 Once all companies have announced their results, I will upload the updated list covering all the results of this earnings season and then close the list.
Which companies from this list are on your watchlist?
Disclaimer: For educational purposes only. Not a buy or sell recommendation. Please do your own research (DYOR) before making any investment decisions. DYDD.

The Indian Investor retweeted
ABAKKUS SMALL CAP FUND – OCTOBER 2026 PORTFOLIO DISCLOSURE 🔥
The complete portfolio holdings, stock-wise allocation, quantity, market value and percentage of AUM are provided in the attached images 👇
▪️ A detailed look at the fund's latest small-cap portfolio allocation and stock holdings.
Disclaimer: Shared for educational and informational purposes only. This is not an investment recommendation.
HELIOS SMALL CAP FUND – OCTOBER 2026 PORTFOLIO DISCLOSURE
The complete portfolio holdings, stock-wise allocation, quantity, market value and percentage of AUM are provided in the attached images 👇
Disclaimer: Shared for educational and informational purposes only. This is not an investment recommendation. Please conduct your own research before making any investment decisions.


The Indian Investor retweeted
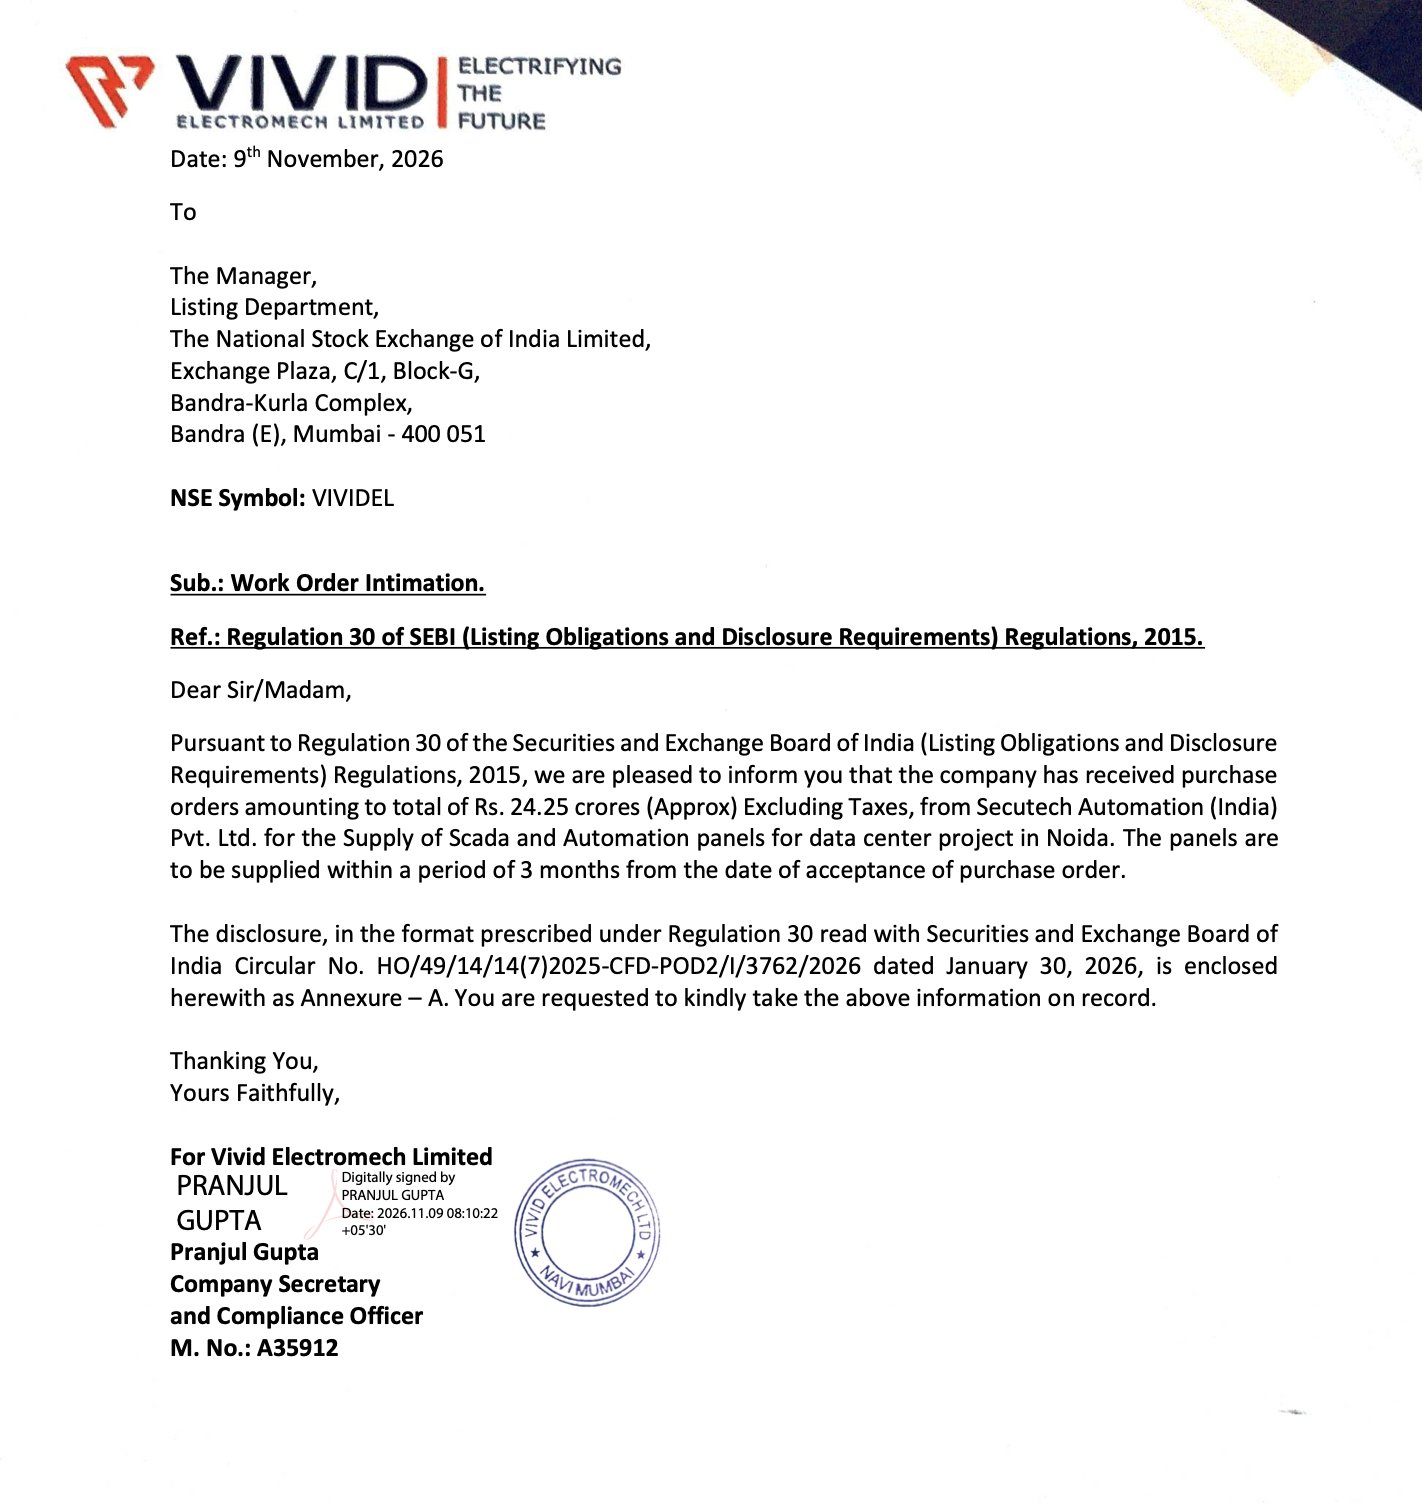
VIVID ELECTROMECH RECEIVES ₹24.25 CRORE ORDER FOR DATA CENTRE PROJECT 🔥🔥🔥
▪️ Vivid Electromech has received purchase orders worth approximately ₹24.25 crore (excluding taxes) from Secutech Automation (India) Pvt. Ltd.
▪️ Scope of work: Supply of SCADA and Automation Panels for a data centre project in Noida.
▪️ Execution timeline: The order is to be executed within 3 months from the date of acceptance of the purchase order.
For informational purposes only. Not a buy/sell recommendation. Please do your own research (DYOR).
The Indian Investor retweeted
HIGH RELATIVE STRENGTH STOCKS TO STUDY & TRACK 🔥🔥🔥
Laurus Labs
Lenskart Solutions
Coforge
MCX
Ather Energy
Sona BLW Precision
Gland Pharma
Cupid
Sai Life Sciences
Acutaas Chemicals
Sansera Engineering
Welspun Living
Diamond Power
Shadowfax Technologies
Lumax Auto Technologies
Shreeji Shipping Global
Pearl Global Industries
Saregama India
Sri Lotus Developers
SG Mart
Indo Count Industries
M B Agro Products
Unimech Aerospace
Steel Strips Wheels
Entero Healthcare
Neogen Chemicals
Krishna Phoschem
Tourism Finance Corporation of India
Timex Group India
Rolex Rings
Sambhv Steel Tubes
SG Finserve
Nitin Spinners
Yash Highvoltage
Shukra Pharmaceuticals
SBC Exports
Oriental Hotels
Ratnaveer Precision Engineering
M M Forgings
⚪ WHY TRACK RELATIVE STRENGTH?
Relative strength helps identify stocks outperforming the broader market or their respective indices.
▪️ Strong stocks tend to show resilience during market corrections.
▪️ They can attract buying interest when broader market momentum improves.
▪️ Look for sustained outperformance, strong price structures, volume confirmation and healthy consolidations.
▪️ Relative strength is a useful starting point for identifying potential leaders, but fundamental research and risk management remain equally important.
Disclaimer: This is a watchlist for educational and research purposes only. Inclusion does not imply a buy recommendation.
The Indian Investor retweeted
#Susanelectricals
SUSAN ELECTRICALS INDIA – Q2 & H1 FY27 CONCALL 5 MINUTES READ ONLY 🔥🔥🔥
BUSINESS TRANSFORMATION & GROWTH STRATEGY
▪️ Management is shifting the company's focus from being a conventional wire and cable supplier towards becoming a specification-driven power cable manufacturer.
▪️ The immediate priority is to strengthen its presence in three key product categories: HT cables, Medium Voltage Covered Conductors (MVCC) and winding wires.
▪️ Management's personal ambition is to achieve approximately 100% YoY growth in FY28 over FY27. This is an aspiration and not formal revenue guidance.
▪️ Management expects H2 FY27 to be significantly stronger than H1, in line with the company's historical seasonality. Government schemes and EPC contractors generally accelerate tendering and execution from October onwards, with February and March being particularly strong months.
▪️ They indicated that H2 revenue can be around 25–40% higher than H1, depending on order availability and execution capacity. This is an industry seasonality observation, not a company-specific revenue commitment.
ORDER BOOK & ORDER PIPELINE
▪️ Order book stood at ₹147 crore as of September 30, 2026, with an additional active order pipeline of approximately ₹200 crore, taking combined visibility to around ₹347 crore.
▪️ During Q2, the company executed approximately ₹107 crore of orders and received around ₹111 crore of fresh orders.
▪️ Order book composition:
HT cables and MVCC: ₹54 crore
Winding wires: ₹69 crore
LT cables: ₹24 crore
▪️ HT cables/MVCC and winding wires together account for more than 80% of the existing order book, reflecting the company's changing product mix.
▪️ Management stated that a significant portion of the ₹200 crore pipeline had already converted into orders during October. It expected approximately 70–100% of this pipeline to receive Letters of Intent (LOIs) within the following month.
▪️ The ₹200 crore pipeline includes tenders where the company had emerged L1, L2, L3 or L4 and was expecting orders. It should therefore be viewed as pipeline visibility, not as an already confirmed order book.
▪️ Management stated that approximately 90% of the referenced order book was scheduled for execution before March 31, 2027. However, it did not commit to executing the entire ₹347 crore during FY27.
▪️ The pipeline is continuously replenished through fresh bids. The company operates across approximately 15–16 states and continues participating in government tenders and engaging with EPC contractors.
▪️ Management indicated that around 90% of its tender outcomes reach the L3 or L4 level. In government supply tenders, orders can sometimes be allocated beyond L1 through reverse auctions, depending on pricing and tender conditions. The company chooses to accept orders where the pricing is commercially suitable.
CAPACITY EXPANSION & MANUFACTURING
▪️ Cable manufacturing capacity has already increased from 7,500 km to approximately 11,000 km.
▪️ The company plans to further expand cable capacity to 16,000 km, with commercial production targeted from March 2027.
▪️ Management also indicated that capacity could subsequently increase from 16,000 km to 20,000 km within the existing facility.
▪️ Winding wire capacity has increased from 3,307 tonnes to 4,200 tonnes, with further expansion planned to 5,500 tonnes. This represents an overall increase of approximately 66% from the earlier capacity.
▪️ Management clarified that the capacity expansion already completed after the IPO should also be considered when assessing the overall increase. It expects capacity by March 2027 to be more than double the March 2026 level.
▪️ The company is at an advanced stage of taking possession of newly acquired land. Management expected the acquisition to be completed by the following month.
▪️ Construction at the new location is planned to begin before the end of 2026. The company intends to install factory sheds and shift operations during FY28–FY29.
▪️ The new facility will focus on HT cables, MVCC and winding wires. Management does not intend to expand LT cable capacity significantly because of intense competition and relatively lower margins.
▪️ They stated that the new land could eventually support capacity approximately five times the scale of the current expansion.
▪️ The existing facilities are expected to be sufficient for the company's internal growth targets up to March 2028. A major expansion is planned after that.
▪️ The company currently operates three plants at different locations and is considering shifting one or two existing factories to the newly acquired land.
LAND ACQUISITION & FUNDING
▪️ The land acquisition will be funded through a combination of internal accruals and bank borrowings.
▪️ Management explained that approximately 25–30% of the collateral provided against cash-credit facilities is in the form of fixed deposits.
▪️ The company has approximately ₹48 crore of fixed deposits, including ₹5.62 crore of pledged mutual funds, placed as collateral against bank cash-credit limits.
▪️ Once the new land is acquired and becomes operational as collateral, management expects to release some of the existing fixed deposits and other collateral.
▪️ Management also indicated that the new land is substantially cheaper than the existing UPSIDC industrial-area land. It quoted approximately ₹1 lakh per square yard for land in the UPSIDC industrial area versus around ₹10,000 per square yard for the newly acquired land.
▪️ The company may eventually shift existing factories and release or sell some of its current properties, subject to collateral release and bank revaluation. Management believes this could unlock capital and support future expansion.
▪️ Management stated that a significant portion of the current year's capex has already been undertaken and advances have been paid. It does not currently foresee a funding crunch over the next few years.
▪️ The company has not provided a firm asset-turnover target for the new plant. Management said it would be possible to assess this after the plant becomes operational and reaches the required capacity.
PRODUCT MIX & REVENUE CONTRIBUTION
▪️ Q2 revenue mix was approximately:
HT cables and MVCC: 30%
Winding wires: 33%
LT cables: 31%
▪️ Management expects HT cables and MVCC to contribute around 40–50% of FY27 business, winding wires approximately 40%, and LT cables around 10–20%.
▪️ For FY28, management reiterated its ambition to move towards a product mix of approximately 45% HT cables/MVCC, 45% winding wires and 5–10% LT cables.
▪️ HT cables and MVCC contribution has increased substantially from approximately 0.75% of H1 FY26 revenue to around 30% in Q2 FY27.
▪️ For the full FY26, HT cables and MVCC had contributed approximately 8.57% of revenue.
▪️ Winding wire sales grew 109% in H1 FY27. Management considers this a core business with relatively fewer organised players and attractive margins.
▪️ Management is deliberately reducing its dependence on LT cables. LT was previously a much larger part of the business, but its contribution has now come down to approximately 30% in Q2.
▪️ HT cable machines can also manufacture LT cables, whereas LT cable machines cannot manufacture HT cables. This provides some manufacturing flexibility as the company shifts towards higher-value products.
Q2 SALES VOLUMES & UNIT ECONOMICS
▪️ Q2 sales volumes:
HT cables and MVCC: 518 km
LT cables and conductors: 1,498 km
Winding wires: 937 tonnes
▪️ For comparison, Q1 sales volumes were:
HT cables: 176 km
LT cables: 3,641 km
Winding wires: 554 tonnes
▪️ HT cable volumes increased from 176 km in Q1 to 518 km in Q2, while winding wire volumes increased from 554 tonnes to 937 tonnes.
▪️ Management also shared EBITDA earned per unit for H1:
HT cables and MVCC: ₹75,808 per km
LT cables: ₹22,252 per km
Winding wires: approximately ₹45 per kg
▪️ In H1 FY26, the corresponding figures were:
HT cables: ₹21,084 per km
LT cables: ₹18,279 per km
Winding wires: approximately ₹40 per kg
▪️ For Q2, management separately indicated EBITDA per unit of approximately:
HT cables: ₹81,987 per km
LT cables: ₹25,007 per km
Winding wires: ₹44 per kg
CCV LINE & HT CABLE OPPORTUNITY
▪️ The new CCV (Continuous Catenary Vulcanisation) line has arrived at the factory and was at the installation stage during the call. Management expected it to become operational within a few days.
▪️ CCV technology uses dry curing. Management explained that most states have made CCV/dry-curing technology mandatory for HT cable supplies.
▪️ The new line is therefore an important capability addition, allowing the company to participate in larger and more complex HT cable tenders that it could not fully access earlier.
▪️ The company currently manufactures HT cables up to 33 kV and plans to move into higher voltage categories.
▪️ Management expects to obtain the required BIS certification for higher-voltage products within approximately 2–3 months and intends to announce the development after certification.
▪️ The company has started participating in more government HT tenders following the expansion of its capabilities.
▪️ Management cited examples of the company emerging L1 in 11 kV and 33 kV MVCC tenders in Paschimanchal Meerut and an HT tender in Madhya Pradesh.
MARGINS & PRODUCT PROFITABILITY
▪️ Management indicated the usual EBITDA margin ranges across products:
HT cables: 12–14%
Winding wires: 10–13%
LT cables: 9–11.5%
▪️ Q2 segment EBITDA margins were approximately:
HT cables and MVCC: 13.13%
Winding wires: 11.82%
LT cables: 11%
▪️ Management expects the overall profitability profile to improve as the contribution of HT cables, MVCC and winding wires increases.
▪️ The company is consciously reducing lower-margin LT cable orders and rejecting orders where the pricing is not attractive.
▪️ Management clarified that the previous year's unusually high EBITDA margins were partly due to abnormal movements in copper and aluminium prices, which resulted in one-time gains.
▪️ Management does not see a current reason for margins to deteriorate, but did not provide a specific numerical margin target for FY28.
CUSTOMER MIX, TENDERING & RAW MATERIAL PRICING
▪️ H1 business mix was approximately 50% government customers and 50% private-sector/EPC customers.
▪️ Earlier, approximately 90–95% of the company's business came from government customers. The company has gradually increased its EPC/private-sector contribution.
▪️ Management is giving greater preference to EPC business because of faster payments, advances and letters of credit.
▪️ Approximately 90% of EPC contractor orders carry price-variation clauses.
▪️ Management clarified that private-sector customers also provide price-variation clauses for orders with longer execution periods. Firm-rate orders are generally supplied immediately, usually within a month.
▪️ Since raw material prices are covered through price-variation arrangements in most orders, management stated that it does not need to hedge conductor orders separately.
▪️ Government payments to MSMEs generally arrive within approximately two months. EPC customers generally pay within 20–30 days or around a month, often through letters of credit.
▪️ The company supplies material with freight included. Management stated that freight is a relatively small proportion of its overall cost because the products are high-volume materials.
WORKING CAPITAL, RECEIVABLES & CASH FLOW
▪️ Management confirmed that operating cash flow has turned positive and expects further improvement in the coming quarters.
▪️ Receivables stood at approximately ₹95 crore as of September 30, 2026.
▪️ Of this, approximately ₹25 crore related to sales made in the last 5–6 days of September and was not yet due.
▪️ The company received approximately ₹44 crore in October against receivables.
▪️ Only around ₹4 crore, or approximately 5% of total receivables, was older than 180 days. Management stated that around ₹3.5 crore of this had already been collected in October, leaving approximately ₹50 lakh outstanding beyond 180 days at the time of the call.
▪️ Management has made collections and inventory control key priorities. It stated that inventory is now being managed more efficiently rather than holding excessive stock to support growth.
▪️ The company uses TReDS to facilitate supplier payments. Under this arrangement, financiers pay suppliers directly, helping the company manage working capital.
▪️ Management indicated TReDS financing costs of approximately 9–12%, compared with around 8–8.5% on bank limits.
▪️ Management explained that TReDS can also help secure vendor discounts because suppliers receive their payments quickly. The facility is expected to continue being used.
▪️ The company currently does not see any working-capital stress and stated that the facilities arranged for FY27 are sufficient for the year.
▪️ Management is already making arrangements for higher working-capital requirements as the business expands in FY28.
DEBT & FINANCE COSTS
▪️ As of September 30, total borrowings stood at approximately ₹122 crore, comprising:
Short-term borrowings: ₹115 crore
Long-term borrowings: ₹7 crore
▪️ Cash and cash equivalents, including investments and short-term bank balances, stood at approximately ₹61 crore.
▪️ This translated into an effective net debt level of approximately ₹60 crore, which management said was broadly similar to the March 31 position.
▪️ Management clarified that a significant amount of the borrowings is connected with fixed deposits and other collateral placed against cash-credit limits.
▪️ Management expects the release of some collateral following the acquisition and use of the new land as security, subject to bank approvals and additional limits.
▪️ The finance team indicated that major capex is being funded through IPO proceeds and that the company intends to fund a substantial portion of future capex through operating cash flow.
▪️ Management does not currently expect a significant increase in finance costs and indicated that there could be scope for a reduction.
RAILWAYS, DEFENCE & OTHER OPPORTUNITIES
▪️ Railways: The company has already entered the railway segment and is supplying material to Indian Railways and RVNL.
▪️ Management stated that the company has completed 3–4 railway tenders and continues to receive orders from this segment.
▪️ Coalfields: The company has also supplied material under Coalfields tenders.
▪️ Defence: The company is exploring entry into the defence segment but had not received a defence tender at the time of the call.
▪️ CTC winding wires: Research and development for continuously transposed conductors (CTC) is underway.
▪️ Management stated that the company can begin CTC production with a smaller order by installing additional machines. Large-scale production would require dedicated machinery and a separate laboratory.
▪️ The company is not currently manufacturing CTC because it has not yet received an order, but management intends to pursue the opportunity.
▪️ Management stated that the company already holds 12 BIS certifications across its product portfolio.
▪️ The company recently completed registration in Uttarakhand for products up to 33 kV MVCC and is seeing good quantities going into the state.
▪️ Management does not currently plan to enter unrelated products such as capacitors or insulators. The immediate focus is to scale the existing portfolio of winding wires, HT cables, LT cables, conductors and MVCC.
EXPORT MARKET & TRADING BUSINESS
▪️ They stated that the company had previously been more aggressive in exporting winding wires, but current domestic demand and margins are attractive.
▪️ At the time of the call, management did not see any immediate export order for winding wires and was primarily catering to the Indian market.
▪️ Trading activity is now very limited, accounting for less than 2% of business and mainly relating to raw-material-related items and scrap.
▪️ Management clarified that earlier metal trading was undertaken during an unusual period of significant commodity-price movements. It is not part of the company's future business plan.
KEY MANAGEMENT CLARIFICATIONS
▪️ The company does not currently have any 3–5-year long-term supply contracts with winding-wire customers. Management said it would consider such contracts if suitable opportunities arise.
▪️ Customer names have not been disclosed because management considers this information commercially confidential.
▪️ Management has agreed to consider publishing more information on order wins, cash flow and product realisations in future disclosures, subject to what it is permitted to disclose.
▪️ Management also acknowledged investor suggestions to provide more regular updates on orders and business developments.
KEY THINGS TO TRACK
▪️ Commissioning of the CCV line and subsequent ramp-up in HT cables and MVCC.
▪️ Cable capacity expansion from 11,000 km to 16,000 km by March 2027, followed by the planned increase towards 20,000 km.
▪️ Winding wire capacity expansion from 4,200 tonnes to 5,500 tonnes.
▪️ Conversion of the ₹200 crore active pipeline into confirmed orders.
▪️ Execution of the ₹147 crore order book and the additional pipeline visibility.
▪️ Progress towards the targeted FY27 and FY28 product mix.
▪️ Higher-voltage HT cable BIS certification and development of CTC winding wires.
▪️ Completion of the new land acquisition, construction and planned FY28–FY29 expansion.
▪️ Further improvement in operating cash flow, receivables and inventory management.
▪️ Management's ability to maintain margins while scaling manufacturing capacity and increasing the share of higher-value products.
Disclaimer: This post is for educational purposes only and is not a buy or sell recommendation. Please conduct your own fundamental and technical research before making any investment decisions. DYDD.

DANISH POWER – H1 FY27 ONLY 2 MINUTES CONCALL READ 🔥🔥🔥
⚪ REVENUE GUIDANCE & OUTLOOK
▪️ FY27 revenue guidance of ₹700 crore+, with management prioritising margin preservation.
▪️ FY28 revenue target of ₹950–990 crore, assuming peak capacity utilisation.
▪️ Management reiterated that the business is structurally H2-heavy, with stronger execution expected in the second half.
▪️ Management believes current demand is structural rather than cyclical, driven by rising power consumption, BESS, renewables, thermal power, transmission and distribution, and exports.
⚪ ORDER BOOK & DEMAND
▪️ Confirmed order book stands at ₹600 crore+, with deliveries scheduled over the next 6–9 months.
▪️ Around 70–80% of orders come from repeat customers. Order book mix is approximately 80% private sector and 20% PSU.
▪️ BESS-related requirements contribute approximately 20% of the order book and around 10% of H1 execution, driven by solar-plus-storage projects and retrofitting existing solar installations.
▪️ Management reported healthy inquiry inflows, higher than earlier levels, across its major business segments.
⚪ MARGINS & RAW MATERIAL
▪️ Management aims to maintain margins at broadly similar levels in FY27, with profitability taking priority over aggressive volume growth.
▪️ Raw material price volatility and freight disruptions are being managed through price variation clauses, selective order pricing and customer-supplier relationships.
▪️ Management does not expect significant raw material cost carryover into H2, as most orders in the current order book are from April onwards. However, geopolitical uncertainty remains.
▪️ Export margins are not consistently higher than domestic margins. They depend on geography and project economics and can be at par or marginally higher.
⚪ CAPACITY EXPANSION & CAPEX
▪️ Phase-3 expansion: Additional capacity of approximately 15,000 MVA, taking total installed capacity to around 26,000 MVA.
▪️ Estimated capex of ₹200 crore, with site work planned around December 2026 and commissioning expected within 18–24 months.
▪️ The new facility will focus on 132 kV, 220 kV and 400 kV EHV transformers, marking Danish Power's entry into the 400 kV segment.
▪️ Around 30–40% of the new capacity is planned for international markets, as export demand continues to grow.
▪️ Funding is expected through approximately ₹100 crore of internal accruals and ₹80–100 crore of debt. Management stated that the company currently has no debt on its books.
⚪ UTILISATION & BACKWARD INTEGRATION
▪️ The Phase-2 expansion became operational in January, activating the power transformer division.
▪️ H1 production output was approximately 500 MVA, with management indicating around 60% utilisation of the expanded 11,000 MVA facility.
▪️ Management expects utilisation to reach approximately 90–92% in FY28, which it considers the typical peak level in transformer manufacturing.
▪️ A fully automated radiator manufacturing plant is expected to be commissioned by the end of November, covering approximately 80–90% of radiator requirements. Radiator delays have been a key bottleneck for delivery timelines and quality consistency.
▪️ In-house tank manufacturing currently covers approximately 20% of total requirements.
⚪ PRODUCT MIX & CERTIFICATIONS
▪️ Power transformers are expected to contribute around 15% of FY27 product mix.
▪️ 132 kV transformers: LOI received, with type testing expected in Q4 FY27.
▪️ 220 kV transformers: LOI expected shortly, with type testing targeted for Q1 FY28.
▪️ Railway-sector opportunities are at an advanced stage, providing another potential growth avenue beyond industrial and distribution transformers.
⚪ EXPORTS & INDUSTRY DEVELOPMENTS
▪️ Export contribution increased from approximately 8% in FY26 to 15% in H1 FY27. Management is targeting profitable export growth rather than volume-led expansion.
▪️ Management indicated that exports account for more than 25% of private-sector orders, while also referring to approximately 20% overall export contribution in the order book. The figures were not entirely consistent during the call.
▪️ The US market remains largely untapped and is currently under evaluation, while existing capacity is being prioritised for Europe and the Middle East.
▪️ Export payments are largely secured through confirmed LCs or ECGC cover. Currency risks are managed through natural hedging, forward contracts and foreign currency accounts.
⚪ WORKING CAPITAL & OTHER DEVELOPMENTS
▪️ Operating cash flow is expected to turn positive in FY28. Growth-related working capital requirements are likely to remain elevated in the near term.
▪️ Additional working capital limits of approximately ₹40–50 crore may be required due to longer production cycles for higher-voltage transformers.
▪️ The approximately ₹14 crore increase in borrowings between March and September was clarified as a subsidiary term loan for sheet-metal fabrication backward integration.
▪️ Main-board migration eligibility completes in October 2027, with the company planning to apply approximately 3–4 months earlier.
⚪ KEY THINGS TO TRACK
▪️ Execution of the ₹600 crore+ order book and achievement of FY27 revenue guidance.
▪️ Commissioning of the radiator plant and improvement in delivery timelines.
▪️ Progress on 132 kV and 220 kV certifications and entry into the 400 kV segment.
▪️ Phase-3 expansion, export growth and utilisation ramp-up towards 90–92% in FY28.
▪️ BESS order conversion, working capital management and the expected improvement in operating cash flow.
Disclaimer:
For educational purposes only. Not a buy or sell recommendation. Please do your own research before making any investment decisions. DYDD.


The Indian Investor retweeted
🪔 SAMVAT 2083 Diwali Picks
25 Brokerages. 187 Stocks. One Diwali Research List.
📊 Most Widely Covered Stocks
▪️ ICICI Bank: 7 brokerages
▪️ Kotak Mahindra Bank: 6 brokerages
▪️ Eternal: 5 brokerages
▪️ HDFC Bank: 5 brokerages
▪️ Indian Hotels: 5 brokerages
▪️ Larsen & Toubro (L&T): 5 brokerages
▪️ Bharat Electronics (BEL): 4 brokerages
▪️ Titan Company: 4 brokerages
▪️ Bharti Airtel: 3 brokerages
▪️ Blue Star: 3 brokerages
▪️ M&M: 3 brokerages
▪️ Tata Steel: 3 brokerages
Axis Securities
▪️ Eternal
▪️ Larsen & Toubro
▪️ Axis Bank
▪️ Bharat Electronics
▪️ BEL
▪️ Bharti Airtel
▪️ Blue Star
▪️ CUMI
Nirmal Bang
▪️ Adani Ports
▪️ HDFC Securities
▪️ HDFC Bank
▪️ Nirmal Bang
▪️ ICICI Bank
▪️ Kotak Bank
▪️ Titan Co
▪️ UltraTech Cement
Arihant Capital
▪️ Sheela Foam
▪️ GMM Pfaudler
▪️ CE Info Sys
▪️ Raymond Lifestyles
▪️ Nuvoco Vistas
▪️ HEG Advanced
▪️ Exide Ind
▪️ Navin Fluorine
Motilal Oswal
▪️ Kotak Bank
▪️ Adani Ports
▪️ Titan Company
▪️ Eternal
▪️ BSE
▪️ SPR Auto
▪️ Shaily
▪️ Arvind
Mirae Asset Sharekhan
▪️ Mirae Asset Sharekhan
▪️ Radico Khaitan
▪️ Dee Development
▪️ Karnataka Bank
▪️ Lumax Auto Tech.
▪️ Sagility
▪️ VA Tech Wabag
PL Capital
▪️ One 97 Communic.
▪️ Prince Pipes
▪️ Rentomojo
▪️ 5G Finserve
▪️ HBL Engineering
▪️ Jindal Steel
▪️ Marine Electricals
▪️ TARIL
KC Securities
▪️ HDFC Bank
▪️ ICICI Bank
▪️ Sansera Engineering
▪️ Jio Platforms
▪️ Grasim Industries
▪️ LIC Housing Finance
▪️ SBI
▪️ PowerGrid
HDFC Sec
▪️ Ambuja Cements
▪️ Adani Power
▪️ Coal India
▪️ Maruti Suzuki
▪️ Can Fin Homes
▪️ KPR Mill
▪️ Tata Steel
▪️ Emcure Pharma
Religare Broking
▪️ Bajaj Finance
▪️ L&T
▪️ Kotak Bank
▪️ ICICI Bank
▪️ HCL Technologies
▪️ Tata Power
▪️ Glenmark Pharma
▪️ Symbiotec
Kotak Neo
▪️ APL Apollo Tubes
▪️ Eternal
▪️ HAL
▪️ Jubilant Ingrevia
▪️ Persistent Sys
▪️ Titan Co
▪️ Ujjivan SFB
▪️ Cyient
Monarch
▪️ Aster DM QC
▪️ BEL
▪️ Bharti Airtel
▪️ Blue Star
▪️ CUMI
▪️ CCL Products
▪️ HDFC AMC
▪️ Indegene
JM Financial
▪️ ICICI Bank
▪️ BEL
▪️ PowerGrid
▪️ Sterlite Tech
▪️ Gravita
▪️ Emcure Pharma
▪️ Eternal
▪️ Bharti Airtel
Geojit
▪️ ICICI Bank
▪️ L&T
▪️ Kotak Bank
▪️ Eternal
▪️ Tech Mahindra
▪️ Samvardhana Mot.
▪️ Indian Hotels
▪️ PVR Inox
SMIFS
▪️ ITC
▪️ L&T
▪️ Mazagon Dock
▪️ Olectra Green
▪️ Bharat Electronics
▪️ Coforge
▪️ Unimech Aero
▪️ Nimtech Aero
Eureka Securities
▪️ DLF
▪️ Deepak Nitrite
▪️ LTTS
▪️ CG Power
▪️ Kotak Bank
▪️ South Indian Bank
▪️ Aditya Infotech
▪️ Leela Palaces
Bajaj Broking
▪️ M&M
▪️ Varun Beverages
▪️ CG Power Indl
▪️ GE Vernova
▪️ Tata Steel
▪️ Indian Hotels
▪️ Time Technoplast
▪️ Centum Elec.
InCred Equities
▪️ RHI Magnesita
▪️ HCL Technologies
▪️ Britannia
▪️ M&M
▪️ Indian Hotels
▪️ Tata Power
▪️ Blue Star
▪️ CESC
Jainam
▪️ Indian Hotels
▪️ HDFC Bank
▪️ Kotak Bank
▪️ Tech Mahindra
▪️ Bharti Hexa
▪️ L&T
▪️ Rolex Rings
▪️ Lemon Tree Hotels
Shriram
▪️ Aeroflex Ind
▪️ Radico Khaitan
▪️ Karur Vysya Bank
▪️ Navin Fluorine
▪️ Dr Lal Path
▪️ ICICI Bank
▪️ Titan Co
▪️ Sona BLW
Choice Intl
▪️ Aptus Value
▪️ Bajaj Consumer
▪️ CPCL
▪️ Coforge
▪️ Fractal Analytics
▪️ ITC Hotels
▪️ Granules
▪️ JK Cement
Anand Rathi
▪️ SBI
▪️ Indo-MIM
▪️ Cemindia Projects
▪️ Shilpa Medicare
▪️ HDFC AMC
▪️ Tech Mahindra
▪️ Sudarsh Chem
▪️ Kirloskar Pneumatic
Ventura Sec
▪️ Park Medi
▪️ HDFC Bank
▪️ One97 Comm
▪️ Meesho
▪️ LG Electronics
▪️ Ather Energy
▪️ Voltas
▪️ Lloyds Engg
SBI Securities
▪️ Tata Steel
▪️ Indian Hotels
▪️ MCX
▪️ Jyoti CNC
▪️ Sky Gold
▪️ Genus Power
▪️ Power Mech
▪️ Antelopus Selan
Equirus
▪️ HDFC Bank
▪️ M&M
▪️ Canara Bank
▪️ Hero MotoCorp
▪️ Time Technoplast
▪️ Technocraft
▪️ Regaal Resources
▪️ Frontier Springs
Angel One
▪️ ICICI Bank
▪️ Northern Arc
▪️ Aarti Pharma
▪️ Shanti Gold
▪️ Ratnaveer
▪️ Precision
▪️ Engineers India
▪️ AGI Infra
🚫 For educational purposes only. Not a recommendation. DYODD.

The Indian Investor retweeted
VIVIANA POWER TECH – Q2 & H1 FY27 CONCALL 2 MINUTES READ ONLY 🔥🔥🔥
⚪ REVENUE GUIDANCE & OUTLOOK
▪️ FY27 revenue guidance: Management reiterated its revenue target of ₹875–910 crore, with expectations of maintaining healthy profitability.
▪️ Current-year revenue mix is expected to remain H1/H2 weighted at approximately 20:80 to 30:70.
▪️ From next financial year onwards, management expects H1 to contribute approximately 40–45% of annual revenue, indicating a more balanced execution cycle.
▪️ The company intends to move towards larger infrastructure opportunities, targeting projects ranging from ₹1,000 crore to over ₹2,000 crore within the next couple of years.
⚪ ORDER BOOK & ORDER PIPELINE
▪️ Current order book stands at ₹1,800 crore+, providing execution visibility.
▪️ Management expects to carry forward at least ₹800–900 crore of order book into the next financial year.
▪️ The company participated in bids worth more than ₹1,900 crore and expects considerable order inflows.
▪️ BESS order book stands at ₹506 crore, with participation in additional BESS bids worth approximately ₹350 crore.
▪️ Importantly, the company is participating in BESS as an EPC contractor rather than a developer, focusing on project execution instead of owning and operating storage assets.
▪️ Technical and commercial bid openings for these opportunities are expected by the end of Q3 or around January.
⚪ MARGINS & PROFITABILITY
▪️ Management has guided for an operating profit margin (OPM) range of 13–15%, with a long-term sustainable margin expectation of approximately 14.5–15%.
▪️ A significant portion of the order book includes price variation clauses, protecting the company against raw material price volatility.
▪️ For fixed-price contracts, management follows proactive procurement and locks material prices around the time of project awards.
▪️ Recent margin pressure was attributed primarily to higher employee costs during H1. Management expects better operating leverage in H2 as revenue scales up.
⚪ BUSINESS EXPANSION & GROWTH STRATEGY
▪️ Viviana Power Tech operates across transmission lines, EHV substations, distribution network establishment and modification, underground cabling and upgradation of existing electrical infrastructure.
▪️ Management is exploring opportunities in RDSS, renewable energy integration, transformer manufacturing and specialised power infrastructure segments.
▪️ The company is preparing to participate in larger tariff-based projects and national infrastructure tenders worth ₹1,000–2,000 crore+ over the next couple of years.
▪️ Management highlighted rising electricity demand, grid expansion and renewable energy integration as long-term structural growth drivers.
⚪ EXECUTION & CUSTOMER MIX
▪️ Management stated that more than 90% of current business comes from government utilities, compared with approximately 90% private-sector business and 10% government business until FY24.
▪️ The company highlighted its execution track record, stating that it was the first company in the country to complete an RDSS project.
▪️ Current projects are progressing across Punjab, Gujarat and Kerala, with management reporting no material land acquisition or execution-related challenges.
▪️ H1 execution was primarily from existing orders, with typical project execution timelines ranging between 9 and 24 months.
⚪ WORKING CAPITAL & FUNDRAISING
▪️ Working capital cycle improved significantly to approximately 150 days from 245 days as of March 2026.
▪️ Management acknowledged that utility and substation EPC projects inherently involve longer billing cycles, regulatory approvals and customer retention amounts.
▪️ The company is continuously optimising its banking facilities to ensure funding availability does not constrain project execution.
▪️ Fundraising strategy change: Management has moved away from the earlier promoter-warrant route and is now pursuing a rights issue, citing interest from existing as well as outside investors. The proposal has been disclosed to the stock exchange.
⚪ KEY THINGS TO TRACK
▪️ Execution and conversion of the ₹1,800 crore+ order book.
▪️ Fresh order inflows from the ₹1,900 crore+ bidding pipeline.
▪️ Conversion of the ₹506 crore BESS order book and additional ₹350 crore bidding pipeline.
▪️ Progress towards larger ₹1,000–2,000 crore infrastructure projects.
▪️ Achievement of FY27 revenue guidance of ₹875–910 crore and maintenance of the 13–15% OPM guidance.
▪️ Further reduction in working capital days and successful completion of the proposed rights issue.
Disclaimer: For educational purposes only. Not a buy or sell recommendation. Please conduct your own fundamental and technical research before making any investment decisions.

The Indian Investor retweeted
SHREE REFRIGERATIONS – NEW DEFENCE ORDER WORTH ₹26.44 CRORE! 🚀
▪️ Shree Refrigerations has secured a fresh domestic defence order worth ₹26.44 crore (excluding GST)from Garden Reach Shipbuilders & Engineers Limited (GRSE), a Government of India undertaking under the Ministry of Defence.
▪️ Scope of work: Supply of specialised components, including:
Electronic control cards and modules
Compressor inverters
Pump bearings, impellers, casings and shafts
Canned motors
Condensers and evaporators
Other electrical components
▪️ Execution timeline: Delivery scheduled by 5 July 2027.
▪️ The company has confirmed that the order is not a related-party transaction and that promoters or promoter-group entities have no interest in the awarding entity.
⚪ WHY THIS IS IMPORTANT
▪️ Further order inflow from a major government defence shipbuilding organisation.
▪️ Strengthens the company's presence in the defence supply chain through specialised components.
▪️ Adds order visibility with execution extending into FY28.
Another defence-sector order win for Shree Refrigerations!
Disclaimer: For educational purposes only. Not a buy or sell recommendation. Please conduct your own research before making investment decisions. DYDD.

The Indian Investor retweeted
HELIOS SMALL CAP FUND – OCTOBER 2026 PORTFOLIO DISCLOSURE
The complete portfolio holdings, stock-wise allocation, quantity, market value and percentage of AUM are provided in the attached images 👇
Disclaimer: Shared for educational and informational purposes only. This is not an investment recommendation. Please conduct your own research before making any investment decisions.
The Indian Investor retweeted
HIGH ROCE SME COMPANIES TO STUDY & TRACK 🔥🔥🔥
ENS Enterprises
Simca Advertising
Vans Electroengineerings
Millworks Technologies
Recode Studios
Technocrats Plasma Systems
Vegorama Punjabi Angithi
Complete Sports
Robokidz Eduventures
Vivid Electromech
Devson Catalyst
Raksan Transformers
Kwick Forensic Solutions
Adon Agro
Infrax Renewable
UNDERSTANDING ROCE (RETURN ON CAPITAL EMPLOYED)
ROCE is one of the most important parameters to evaluate a company's capital efficiency.
It tells us how efficiently a company is utilising its total capital (equity + debt) to generate operating profits.
Formula:
ROCE = EBIT ÷ Capital Employed × 100
Where:
▪️ EBIT: Earnings Before Interest and Taxes, representing operating profit before interest and tax expenses.
▪️ Capital Employed: Total Assets minus Current Liabilities. It can also be calculated using shareholders' equity and debt, with appropriate adjustments.
Why is ROCE important?
▪️ Higher capital efficiency: A higher ROCE indicates that a company generates more operating profit from the capital invested in its business.
▪️ Quality of business: Consistently high ROCE can indicate efficient operations, pricing power and disciplined capital allocation.
▪️ Expansion efficiency: It helps investors evaluate whether a company is generating adequate returns from its expansion and additional investments.
▪️ Debt efficiency: ROCE helps assess whether the operating returns generated by a business justify the capital deployed, including borrowed funds.
▪️ Consistency matters: A company maintaining healthy ROCE over several years is generally more interesting to study than one reporting exceptionally high ROCE for just one year.
Example:
If a company has capital employed of ₹100 crore and generates EBIT of ₹25 crore, its ROCE is 25%.
This means the company generates ₹25 in operating profit for every ₹100 of capital employed.
Important: Never evaluate a company solely on ROCE. Also examine debt levels, cash flows, working capital, business growth, capital expenditure and return on incremental capital. Always compare ROCE with companies operating in similar industries.
Disclaimer: The above companies are shared for educational purposes and further research only. Their inclusion does not independently establish that they currently have high ROCE. Please verify their latest financials and conduct your own research before making investment decisions. Not a buy or sell recommendation. DYDD.


The Indian Investor retweeted
BIG BOOST FOR INDIAN DEFENCE MANUFACTURING – ₹2.12 LAKH CRORE! 🔥🔥🔥
SMALL-CAP AEROSPACE AND DEFENCE STOCKS TO STUDY & TRACK
Data Patterns
Sigma Advanced Systems
Zen Technologies
Apollo Micro Systems
Astra Microwave Products
Aequs
Paras Defence
Unimech Aerospace
Tonbo Imaging
AXISCADES Technologies
Mishra Dhatu Nigam
Cyient DLM
Centum Electronics
Rossell Techsys
Avantel
ideaForge Technology
CFF Fluid Control
Krishna Defence
Millworks Technologies
NIBE
Shree Refrigerations
Apsis Aerocom
⚪ WHAT HAS BEEN APPROVED?
▪️ Indian Army: Artillery systems, high-mobility vehicles, helicopters, air-defence systems, counter-drone systems, surveillance UAVs and long-range kamikaze drones.
▪️ Indian Navy: Active offboard decoy systems and other major naval platforms, including indigenously designed and constructed platforms.
▪️ Indian Air Force: Helicopters, air-defence systems, weapons and mobile X-band Doppler weather radar systems.
⚪ WHY IS THIS IMPORTANT?
▪️ Approximately 82% of the proposed procurement is expected to come from Indian industry.
▪️ The proposals cover multiple segments, including drones, electronics, surveillance, aerospace, artillery, naval systems and air defence.
▪️ This reinforces the government's focus on strengthening domestic defence manufacturing and reducing dependence on imports.
A significant development for India's defence manufacturing ecosystem. The next thing to watch is how these approvals translate into actual tenders and order awards.
Disclaimer: The above companies are listed for educational purposes and further research only. This is not a buy or sell recommendation.


⚔️ India’s ₹2.12L Cr Defence Value Chain: 75 Beneficiary Stocks
India's ₹2.12 Lakh Cr defence acquisition approval marks a massive push for indigenous manufacturing.
🗒️ Key listed players
▪️ HAL (Hindustan Aeronautics)
Revenue: ₹5,515 Cr | Order Book: ₹2,60,960 Cr
▪️ BEL (Bharat Electronics)
Revenue: ₹5,547 Cr | Order Book: ₹72,258 Cr
▪️ BDL (Bharat Dynamics)
Revenue: ₹572 Cr | Order Book: ₹26,176 Cr
🔥 AI, Drones & Multi-Domain Combat: Inside India’s 2026 Defence Value Chain
1️⃣ The next war won’t look like the last.
Defence Minister Rajnath Singh has unveiled the Indian Army’s Land Warfare Doctrine 2026, marking a massive strategic shift toward AI, drones, and multi-domain warfare.
2️⃣ The Warning Came from Real Battlefields
Recent conflicts and operations like Operation Sindoor have reinforced a harsh reality:
▪️ Communications can be disrupted.
▪️ Surveillance is constant.
▪️ Threats arrive without warning.
Precision, intelligence, and coordination are everything.
3️⃣ Five Domains. One War.
Future land battles will no longer depend on ground troops alone. The new doctrine emphasizes seamless integration across five core domains:
▪️ Land
▪️ Air
▪️ Sea
▪️ Space
▪️ Cyber
4️⃣ 1.2 Million Soldiers. A New Skillset.
Drones are rapidly becoming a soldier's second skill. To operationalize this, the Army is rolling out three major initiatives:
▪️ A 5-year roadmap for multi-domain training.
▪️ A 3-level AI skills program for officers.
▪️ Drone operations as a standard secondary skill force-wide.
5️⃣ Atmanirbhar Bharat in Defence
Self-reliance is now at the absolute centre of India's military planning. This means:
▪️ Indigenous defence systems
▪️ Stronger domestic supply chains
▪️ Technology-enabled soldiers
▪️ Greater tri-services coordination
6️⃣ The battlefield of tomorrow is being shaped today.
As technology evolves at breakneck speed, India’s military doctrine is adapting to ensure dominance across land, air, sea, space, and cyberspace.
📊 A robust ecosystem is emerging across every layer - from drones to destroyer:
▪️ Defence & Aerospace
Bharat Electronics Limited (BEL)
Hindustan Aeronautics Limited (HAL)
Bharat Dynamics Limited (BDL)
Data Patterns
Apollo Micro Systems (AMS)
Sigma Advanced Systems
Krishna Defence & Allied Industries Ltd
Unimech Aerospace and Manufacturing
Limited (UAML)
MTAR Technologies Ltd
Azad Engineering Ltd
NIBE Ltd
Avantel Ltd
Techera Engineering
DCX Systems
Adani Defence
Paras Defence
Dynamatic Technologies
Lokesh Machines
Rossell India
Macpower CNC Machines
Tembo Global Industries
AXISCADES Technologies
Premier Explosives
Sika Interplant Systems
Mishra Dhatu Nigam Ltd
Jyoti CNC Automation
PTC Industries
Solar Industries
Jaykay Enterprises
Swan Defence and Heavy Industries
Mahindra Aerospace
Tata Advanced Systems
Merritronix
Millworks Technologies
Tonbo Imaging India
Aequs
▪️ Land Systems & Military Vehicles
Ashok Leyland
Bharat Forge
Larsen & Toubro
Tata Motors
Mahindra & Mahindra
BEML
▪️ Shipbuilding & Naval Systems
Garden Reach Shipbuilders (GRSE)
Mazagon Dock Shipbuilders (MDL)
Cochin Shipyard
CFF Fluid Control Ltd
Larsen & Toubro
Shree Refrigerations
Hindustan Shipyard Limited (HSL)
▪️ Drone-Anti Drone & Unmanned
Zen Technologies
ideaForge Technology
Droneacharya Aerial Innovations
Paras Defence and Space Technologies
Garuda Aerospace
Adani Defence
Drone Destination
Asteria Aerospace Limited
▪️ Cybersecurity & Telecommunication
Expleo Solutions Ltd.
Tac Infosec
L&T Technology Services
Sahana Systems
Astra Microwave Products Ltd
▪️ Electronic Systems & C4ISR
Data Patterns
Bharat Electronics (BEL)
Tata Elxsi
Centum Electronics
Paras Defence
Electronics Corporation of India (ECIL)
💡Approvals highlight strong domestic sourcing (82%), but execution into final order conversions remains the crucial key metric to track.
🚫 For educational purposes only.
No Recommendation. DYODD.

The Indian Investor retweeted
DANISH POWER – H1 FY27 ONLY 2 MINUTES CONCALL READ 🔥🔥🔥
⚪ REVENUE GUIDANCE & OUTLOOK
▪️ FY27 revenue guidance of ₹700 crore+, with management prioritising margin preservation.
▪️ FY28 revenue target of ₹950–990 crore, assuming peak capacity utilisation.
▪️ Management reiterated that the business is structurally H2-heavy, with stronger execution expected in the second half.
▪️ Management believes current demand is structural rather than cyclical, driven by rising power consumption, BESS, renewables, thermal power, transmission and distribution, and exports.
⚪ ORDER BOOK & DEMAND
▪️ Confirmed order book stands at ₹600 crore+, with deliveries scheduled over the next 6–9 months.
▪️ Around 70–80% of orders come from repeat customers. Order book mix is approximately 80% private sector and 20% PSU.
▪️ BESS-related requirements contribute approximately 20% of the order book and around 10% of H1 execution, driven by solar-plus-storage projects and retrofitting existing solar installations.
▪️ Management reported healthy inquiry inflows, higher than earlier levels, across its major business segments.
⚪ MARGINS & RAW MATERIAL
▪️ Management aims to maintain margins at broadly similar levels in FY27, with profitability taking priority over aggressive volume growth.
▪️ Raw material price volatility and freight disruptions are being managed through price variation clauses, selective order pricing and customer-supplier relationships.
▪️ Management does not expect significant raw material cost carryover into H2, as most orders in the current order book are from April onwards. However, geopolitical uncertainty remains.
▪️ Export margins are not consistently higher than domestic margins. They depend on geography and project economics and can be at par or marginally higher.
⚪ CAPACITY EXPANSION & CAPEX
▪️ Phase-3 expansion: Additional capacity of approximately 15,000 MVA, taking total installed capacity to around 26,000 MVA.
▪️ Estimated capex of ₹200 crore, with site work planned around December 2026 and commissioning expected within 18–24 months.
▪️ The new facility will focus on 132 kV, 220 kV and 400 kV EHV transformers, marking Danish Power's entry into the 400 kV segment.
▪️ Around 30–40% of the new capacity is planned for international markets, as export demand continues to grow.
▪️ Funding is expected through approximately ₹100 crore of internal accruals and ₹80–100 crore of debt. Management stated that the company currently has no debt on its books.
⚪ UTILISATION & BACKWARD INTEGRATION
▪️ The Phase-2 expansion became operational in January, activating the power transformer division.
▪️ H1 production output was approximately 500 MVA, with management indicating around 60% utilisation of the expanded 11,000 MVA facility.
▪️ Management expects utilisation to reach approximately 90–92% in FY28, which it considers the typical peak level in transformer manufacturing.
▪️ A fully automated radiator manufacturing plant is expected to be commissioned by the end of November, covering approximately 80–90% of radiator requirements. Radiator delays have been a key bottleneck for delivery timelines and quality consistency.
▪️ In-house tank manufacturing currently covers approximately 20% of total requirements.
⚪ PRODUCT MIX & CERTIFICATIONS
▪️ Power transformers are expected to contribute around 15% of FY27 product mix.
▪️ 132 kV transformers: LOI received, with type testing expected in Q4 FY27.
▪️ 220 kV transformers: LOI expected shortly, with type testing targeted for Q1 FY28.
▪️ Railway-sector opportunities are at an advanced stage, providing another potential growth avenue beyond industrial and distribution transformers.
⚪ EXPORTS & INDUSTRY DEVELOPMENTS
▪️ Export contribution increased from approximately 8% in FY26 to 15% in H1 FY27. Management is targeting profitable export growth rather than volume-led expansion.
▪️ Management indicated that exports account for more than 25% of private-sector orders, while also referring to approximately 20% overall export contribution in the order book. The figures were not entirely consistent during the call.
▪️ The US market remains largely untapped and is currently under evaluation, while existing capacity is being prioritised for Europe and the Middle East.
▪️ Export payments are largely secured through confirmed LCs or ECGC cover. Currency risks are managed through natural hedging, forward contracts and foreign currency accounts.
⚪ WORKING CAPITAL & OTHER DEVELOPMENTS
▪️ Operating cash flow is expected to turn positive in FY28. Growth-related working capital requirements are likely to remain elevated in the near term.
▪️ Additional working capital limits of approximately ₹40–50 crore may be required due to longer production cycles for higher-voltage transformers.
▪️ The approximately ₹14 crore increase in borrowings between March and September was clarified as a subsidiary term loan for sheet-metal fabrication backward integration.
▪️ Main-board migration eligibility completes in October 2027, with the company planning to apply approximately 3–4 months earlier.
⚪ KEY THINGS TO TRACK
▪️ Execution of the ₹600 crore+ order book and achievement of FY27 revenue guidance.
▪️ Commissioning of the radiator plant and improvement in delivery timelines.
▪️ Progress on 132 kV and 220 kV certifications and entry into the 400 kV segment.
▪️ Phase-3 expansion, export growth and utilisation ramp-up towards 90–92% in FY28.
▪️ BESS order conversion, working capital management and the expected improvement in operating cash flow.
Disclaimer:
For educational purposes only. Not a buy or sell recommendation. Please do your own research before making any investment decisions. DYDD.
KRN HEAT EXCHANGER – Q2 FY27 2 MINUTES CONCALL READ 🔥🔥🔥
➡️ REVENUE GUIDANCE & GROWTH OUTLOOK
▪️ Management indicated that FY27 revenue could exceed the earlier ₹1,200 crore guidance and potentially reach approximately ₹1,250 crore, subject to external factors.
▪️ Export revenue guidance has been increased from around ₹200 crore to approximately ₹250 crore for FY27.
▪️ Management expects at least 30% growth beyond the current year, supported by exports, data centres, automotive, railways and new product segments.
➡️ EXPORT BUSINESS
▪️ Exports nearly tripled during H1 FY27 and contributed approximately 22% of total revenue.
▪️ The US is the largest export market, followed by Canada, France, the UK and Italy. The company also serves markets including UAE, Vietnam, Sri Lanka, Brazil and Nepal.
▪️ Management is targeting 50% export contribution in the fin-and-tube heat exchanger segment by FY28. This is not a target for total company revenue.
▪️ Export customers generally offer 4–5 percentage points higher EBITDA margins than domestic customers, before freight costs.
➡️ CAPACITY EXPANSION & UTILISATION
▪️ KRN operates two major manufacturing facilities at Neemrana, Rajasthan:
Plant I – KRN Heat Exchanger: Total land area of 1,04,948 sq. ft.
Plant II – KRN HVAC Products (wholly owned subsidiary): Total land area of 8,40,128 sq. ft.
▪️ Plant II is approximately eight times larger in land area than Plant I. These figures represent total land area, not built-up factory area.
▪️ The company's website lists annual fin-and-tube production capacity of approximately 10 lakh units at Plant I and 40 lakh units at Plant II.
▪️ Plant I is already operating at near-full utilisation. Plant II is being ramped up, with management targeting approximately 50% utilisation in FY27 and 80% in FY28.
▪️ The new facility supports a wider product portfolio, including fin-and-tube and bar-and-plate heat exchangers, refrigeration components and complete HVAC solutions.
▪️ An analyst referred to approximately ₹1,800 crore revenue potential at 100% utilisation of Plant II. Management did not independently confirm this figure during the call, noting that revenue potential also depends on metal prices.
▪️ Management is also planning a facility in Bengaluru/South India to support future expansion. No specific investment amount or commissioning timeline was disclosed during the call.
➡️ ORDER BOOK & ORDER INFLOWS
▪️ The company follows a rolling order-book model, with orders coming continuously from its customers. Management did not disclose a consolidated order-book figure.
▪️ Demand remains healthy across heat exchangers, data centres, exports, bus air-conditioning and industrial cooling, supporting ongoing order inflows.
➡️ DATA CENTRE OPPORTUNITY
▪️ Data-centre business contributed approximately ₹180 crore during H1 FY27, compared with around ₹38 crore in H1 FY26.
▪️ The company has onboarded domestic and international customers. Some domestic customers are single-sourcing from KRN, while others are allocating 50–60% of their requirements.
▪️ Export data-centre orders exceeded ₹50 crore at the time of the call, with customers generally placing rolling orders covering 1–2 months.
▪️ KRN is developing bridge-plate heat exchangers for liquid-cooling applications. Development is expected to take around 1.5 years, with commercial revenue potentially starting around FY29.
➡️ AUTOMOTIVE & BUS AIR-CONDITIONING
▪️ The Indian bus air-conditioning market is estimated at approximately ₹1,000 crore, growing at 25–30%, with electric buses driving demand.
▪️ KRN has commenced supplies to an OEM and added several bus bodybuilders as customers. It is engaging with additional OEMs for approvals, particularly in electric buses.
▪️ Management indicated that the company is currently slightly below its earlier 15% market-share ambition and expects better visibility on progress by Q3.
▪️ In-house heat exchanger tubing and FRP capabilities provide backward integration for this business.
▪️ The company is also working on local development of compressors for bus air-conditioning systems.
➡️ RAILWAY BUSINESS
▪️ Prototype development for railway air-conditioning systems has been completed. The company is pursuing the required plant approval to participate in railway tenders.
▪️ Initial focus will be on driver-cab AC systems, followed by LHB coaches, Vande Bharat trains and Metro projects.
▪️ Management expects approximately ₹20 crore revenue from railway HVAC systems next year.
➡️ PRODUCT PORTFOLIO EXPANSION
▪️ KRN is expanding beyond fin-and-tube heat exchangers into bar-and-plate heat exchangers, refrigeration components and complete HVAC systems.
▪️ New product categories include dry air coolers, open-top condensers, adiabatic coolers, remote radiators and cold-storage solutions.
▪️ Bar-and-plate heat exchangers, bus AC systems and complete HVAC solutions offer opportunities for a better product mix and higher margins.
▪️ More than 30 new customers were added across product segments during the previous quarter.
➡️ TECHNOLOGY & TESTING CAPABILITIES
▪️ The Thermotech Research Laboratory has started internal testing, supporting product validation, performance testing and value engineering.
▪️ The facility can help optimise designs and reduce copper consumption while maintaining product performance.
▪️ NABL certification was expected within 4–5 weeks of the call, followed by HRI certification. External testing services could commence 2–3 months after the required certifications.
➡️ WORKING CAPITAL & RAW MATERIALS
▪️ To manage new BIS requirements for copper tubes, the company has increased inventory, is developing domestic suppliers and plans to use advance licences for export-related sourcing.
▪️ Management stated that changes in copper, aluminium and stainless-steel prices are generally passed on to customers through quarterly price revisions.
▪️ SAP-based inventory monitoring, export factoring and buyer's credit for imports are among the measures being implemented to improve working-capital efficiency.
▪️ Management expects working-capital and cash-flow improvement by the end of FY27.
➡️ MARGIN OUTLOOK
▪️ Management indicated FY27 EBITDA margin guidance of approximately 17–18%, with a medium-to-long-term margin ambition of 18–20%.
▪️ Near-term margins are affected by higher export freight costs, metal prices and certain customer-specific pricing arrangements.
▪️ Management expects Q3 margins to remain broadly similar, with potential improvement in Q4 through higher volumes, operating leverage and a better export mix.
➡️ KEY MONITORABLES
▪️ Nimrana utilisation and progress on the Bengaluru facility.
▪️ Export growth and achievement of the FY28 export-mix target.
▪️ Data-centre order inflows and liquid-cooling product development.
▪️ Electric bus OEM approvals and railway plant certification.
▪️ Commercialisation of new products and improvement in working capital.
Disclaimer:
For educational purposes only. Not a buy/sell recommendation. DYDD.

The Indian Investor retweeted
#Airfloa
SETUP TO STUDY 👇
Airfloa Rail Technology - IPO BASE BREAKOUT SETUP + 100 EMA RETEST + 0.5 LEVEL OF FIBONACCI
No advice. DYOR.

The Indian Investor retweeted
🔋 India’s BESS Megatrend: 7X Growth by FY32 ⚡️
✅ Capacity projection: 34.7 GWh ➡️ 236 GWh
✅ Potential Investment: ₹3.49 Lakh Crore 📈
The Battery Energy Storage Systems (BESS) expansion is not just about battery cells - it covers power electronics, transformers, grid infra, EPC, and renewable energy.
🗒️ 27 Companies to Track Across the BESS Ecosystem
▪️ Waaree Energies
▪️ Exide Industries
▪️ Amara Raja Energy & Mobility
▪️ Premier Energies
▪️ Vikram Solar
▪️ HBL Engineering
▪️ Hitachi Energy India
▪️ Siemens
▪️ JSW Energy
▪️ Quality Power
▪️ Pace Digitek
▪️ Himadri Speciality Chemical
▪️ Neogen Chemicals
▪️ Advait Energy Transitions
▪️ Godawari Power & Ispat
▪️ Oriana Power
▪️ SPML Infra
▪️ Prostarm Info Systems
▪️ PCBL
▪️ HEG Advanced Materials
▪️ ACME Solar
▪️ KPI Green Energy
▪️ K.P. Energy
▪️ GP Eco Solutions
▪️ Maxvolt Energy
▪️ CLN Energy
▪️ Bondada Engineering
🔀 How BESS Proxy Plays Breakdown Across Sectors:
🔹 Batteries & Chemical Inputs: Exide, Amara Raja, HBL, Himadri, Neogen, PCBL, HEG Advanced Materials, Maxvolt Energy, CLN Energy.
🔹 Solar, Modules & Cell Mfrs: Waaree Energies, Premier Energies, Vikram Solar, ACME Solar.
🔹 Power Electronics & Transformers: Hitachi Energy, Siemens, Quality Power, Prostarm Info Systems, Pace Digitek.
🔹 EPC, Grid & Utilities: JSW Energy, KPI Green, K.P. Energy, Oriana Power, Bondada Eng, Advait Energy, Godawari Power, SPML Infra, GP Eco Solutions.
The Bottom Line 💡
A booming sector doesn't guarantee booming returns.
Before investing, track key metrics:
⚠️ Valuations & P/E multiples
📊 Order-book execution
📉 Profit margins & debt
💵 Sustainable cash flows
Demand is coming - focus on execution leaders.
🚫 For educational purposes only. Not a buy/sell recommendation. DYODD.

The Indian Investor retweeted
KRN HEAT EXCHANGER – Q2 FY27 2 MINUTES CONCALL READ 🔥🔥🔥
➡️ REVENUE GUIDANCE & GROWTH OUTLOOK
▪️ Management indicated that FY27 revenue could exceed the earlier ₹1,200 crore guidance and potentially reach approximately ₹1,250 crore, subject to external factors.
▪️ Export revenue guidance has been increased from around ₹200 crore to approximately ₹250 crore for FY27.
▪️ Management expects at least 30% growth beyond the current year, supported by exports, data centres, automotive, railways and new product segments.
➡️ EXPORT BUSINESS
▪️ Exports nearly tripled during H1 FY27 and contributed approximately 22% of total revenue.
▪️ The US is the largest export market, followed by Canada, France, the UK and Italy. The company also serves markets including UAE, Vietnam, Sri Lanka, Brazil and Nepal.
▪️ Management is targeting 50% export contribution in the fin-and-tube heat exchanger segment by FY28. This is not a target for total company revenue.
▪️ Export customers generally offer 4–5 percentage points higher EBITDA margins than domestic customers, before freight costs.
➡️ CAPACITY EXPANSION & UTILISATION
▪️ KRN operates two major manufacturing facilities at Neemrana, Rajasthan:
Plant I – KRN Heat Exchanger: Total land area of 1,04,948 sq. ft.
Plant II – KRN HVAC Products (wholly owned subsidiary): Total land area of 8,40,128 sq. ft.
▪️ Plant II is approximately eight times larger in land area than Plant I. These figures represent total land area, not built-up factory area.
▪️ The company's website lists annual fin-and-tube production capacity of approximately 10 lakh units at Plant I and 40 lakh units at Plant II.
▪️ Plant I is already operating at near-full utilisation. Plant II is being ramped up, with management targeting approximately 50% utilisation in FY27 and 80% in FY28.
▪️ The new facility supports a wider product portfolio, including fin-and-tube and bar-and-plate heat exchangers, refrigeration components and complete HVAC solutions.
▪️ An analyst referred to approximately ₹1,800 crore revenue potential at 100% utilisation of Plant II. Management did not independently confirm this figure during the call, noting that revenue potential also depends on metal prices.
▪️ Management is also planning a facility in Bengaluru/South India to support future expansion. No specific investment amount or commissioning timeline was disclosed during the call.
➡️ ORDER BOOK & ORDER INFLOWS
▪️ The company follows a rolling order-book model, with orders coming continuously from its customers. Management did not disclose a consolidated order-book figure.
▪️ Demand remains healthy across heat exchangers, data centres, exports, bus air-conditioning and industrial cooling, supporting ongoing order inflows.
➡️ DATA CENTRE OPPORTUNITY
▪️ Data-centre business contributed approximately ₹180 crore during H1 FY27, compared with around ₹38 crore in H1 FY26.
▪️ The company has onboarded domestic and international customers. Some domestic customers are single-sourcing from KRN, while others are allocating 50–60% of their requirements.
▪️ Export data-centre orders exceeded ₹50 crore at the time of the call, with customers generally placing rolling orders covering 1–2 months.
▪️ KRN is developing bridge-plate heat exchangers for liquid-cooling applications. Development is expected to take around 1.5 years, with commercial revenue potentially starting around FY29.
➡️ AUTOMOTIVE & BUS AIR-CONDITIONING
▪️ The Indian bus air-conditioning market is estimated at approximately ₹1,000 crore, growing at 25–30%, with electric buses driving demand.
▪️ KRN has commenced supplies to an OEM and added several bus bodybuilders as customers. It is engaging with additional OEMs for approvals, particularly in electric buses.
▪️ Management indicated that the company is currently slightly below its earlier 15% market-share ambition and expects better visibility on progress by Q3.
▪️ In-house heat exchanger tubing and FRP capabilities provide backward integration for this business.
▪️ The company is also working on local development of compressors for bus air-conditioning systems.
➡️ RAILWAY BUSINESS
▪️ Prototype development for railway air-conditioning systems has been completed. The company is pursuing the required plant approval to participate in railway tenders.
▪️ Initial focus will be on driver-cab AC systems, followed by LHB coaches, Vande Bharat trains and Metro projects.
▪️ Management expects approximately ₹20 crore revenue from railway HVAC systems next year.
➡️ PRODUCT PORTFOLIO EXPANSION
▪️ KRN is expanding beyond fin-and-tube heat exchangers into bar-and-plate heat exchangers, refrigeration components and complete HVAC systems.
▪️ New product categories include dry air coolers, open-top condensers, adiabatic coolers, remote radiators and cold-storage solutions.
▪️ Bar-and-plate heat exchangers, bus AC systems and complete HVAC solutions offer opportunities for a better product mix and higher margins.
▪️ More than 30 new customers were added across product segments during the previous quarter.
➡️ TECHNOLOGY & TESTING CAPABILITIES
▪️ The Thermotech Research Laboratory has started internal testing, supporting product validation, performance testing and value engineering.
▪️ The facility can help optimise designs and reduce copper consumption while maintaining product performance.
▪️ NABL certification was expected within 4–5 weeks of the call, followed by HRI certification. External testing services could commence 2–3 months after the required certifications.
➡️ WORKING CAPITAL & RAW MATERIALS
▪️ To manage new BIS requirements for copper tubes, the company has increased inventory, is developing domestic suppliers and plans to use advance licences for export-related sourcing.
▪️ Management stated that changes in copper, aluminium and stainless-steel prices are generally passed on to customers through quarterly price revisions.
▪️ SAP-based inventory monitoring, export factoring and buyer's credit for imports are among the measures being implemented to improve working-capital efficiency.
▪️ Management expects working-capital and cash-flow improvement by the end of FY27.
➡️ MARGIN OUTLOOK
▪️ Management indicated FY27 EBITDA margin guidance of approximately 17–18%, with a medium-to-long-term margin ambition of 18–20%.
▪️ Near-term margins are affected by higher export freight costs, metal prices and certain customer-specific pricing arrangements.
▪️ Management expects Q3 margins to remain broadly similar, with potential improvement in Q4 through higher volumes, operating leverage and a better export mix.
➡️ KEY MONITORABLES
▪️ Nimrana utilisation and progress on the Bengaluru facility.
▪️ Export growth and achievement of the FY28 export-mix target.
▪️ Data-centre order inflows and liquid-cooling product development.
▪️ Electric bus OEM approvals and railway plant certification.
▪️ Commercialisation of new products and improvement in working capital.
Disclaimer:
For educational purposes only. Not a buy/sell recommendation. DYDD.
KRN HEAT EXCHANGER – Q2 & H1 FY27 INVESTOR HIGHLIGHTS ❄️🧊
About the company
▪️ KRN caters to multiple industries, including HVAC, refrigeration, data centres, automotive, railways, industrial cooling, process applications, power and marine.
▪️ The company focuses on customised product development, precision engineering, integrated manufacturing, testing and quality control.
Data centre cooling – an important growth opportunity
▪️ Management highlighted data centre cooling as an important emerging growth engine for KRN.
▪️ New customers in the data centre segment have started working with the company.
▪️ Customers are planning their requirements and placing orders well in advance, providing better visibility for future business.
▪️ KRN's existing Fin & Tube product portfolio includes solutions for data centres, server rooms, precision air conditioning and CRAC units.
▪️ The company is also developing products for liquid cooling as data centre cooling technology evolves towards this solution.
▪️ Increasing demand for data centres and associated thermal-management infrastructure could create opportunities across the company's cooling product portfolio.
Bus AC business – new growth segment
▪️ During 2025–26, KRN established its wholly owned subsidiary, KRN HVAC Products Private Limited, and acquired the Bus AC division of Sphere Refrigeration Systems.
▪️ The acquisition expands the company's presence into bus air-conditioning solutions.
▪️ Management confirmed that supplies to an OEM have commenced.
▪️ The company is gradually adding more customers in this segment.
▪️ Its product portfolio includes electric bus AC and conventional bus AC systems, catering to city, school, staff and electric buses.
Exports and international presence
▪️ KRN has an established export presence across North America, Europe, the UAE and other international markets.
Export contribution to total revenue:
▪️ FY24 – 14.68%
▪️ FY25 – 15.69%
▪️ FY26 – 16.57%
▪️ H1 FY27 – 22.01%
▪️ Domestic sales contributed 77.99% of H1 FY27 revenue, while exports contributed 22.01%.
▪️ H1 FY27 country-wise export revenue distribution:
▪️ USA – 43.75%
▪️ Canada – 12.82%
▪️ France – 12.67%
▪️ UK – 7.93%
▪️ Italy – 7.65%
▪️ Others – 15.19%
▪️ Management stated that exports have grown several times over the first half of FY27, with increased business from customers in North America and Europe.
Certifications and competitive positioning
▪️ The company holds multiple quality and compliance certifications supporting its domestic and international operations.
▪️ Key certifications include CE, IMS, ZED Silver, EN ISO 15609-1:2019, ISO 9606-1:2017, BS EN ISO 13134, BS EN ISO 13535, AHRI, UL 207 and IS 11329:2018.
▪️ KRN has received recognition from global industry participants, including Carrier, Daikin, Honeywell and Schneider Electric.
Management outlook and growth strategy
▪️ Management described H1 FY27 as a strong period, with growth across customers, products and geographies.
▪️ Expanded manufacturing capabilities at Neemrana are expected to support larger customer programmes.
▪️ The company is continuing to qualify more customers and widen its product portfolio.
▪️ Management sees opportunities across data centres, infrastructure, mobility and industrial cooling.
▪️ Data centre cooling is becoming an important growth engine, with customers planning and placing orders well in advance.
▪️ Liquid cooling product development is another area the company is working on.
▪️ In the Bus AC segment, supplies have commenced to an OEM, and the company is working on adding more customers.
▪️ Management remains optimistic about the opportunities ahead and is strengthening its teams and systems to support expansion.
KRN is expanding beyond its traditional heat exchanger business into a broader HVAC&R solutions platform.
Data centre cooling, liquid cooling development, exports and the newly added Bus AC business provide multiple potential growth avenues. Its wider product portfolio, manufacturing infrastructure and international customer relationships are important strengths to track.
For educational purposes only. Not a buy/sell recommendation. Please do your own research before making any investment decisions. DYDD.

The Indian Investor retweeted
COMPANIES THAT REPORTED MORE THAN 100% YOY SALES GROWTH IN Q2 FY27 🔥🔥🔥
▪️ E2E Networks – 411%
▪️ Netweb Technologies – 336%
▪️ SPARC – 282%
▪️ MTAR Technologies – 200%
▪️ Innovassynth Technologies – 175%
▪️ Asian Energy Services – 161%
▪️ Prizor Viztech – 154%
▪️ Sterlite Technologies – 145%
▪️ HEG Advanced Materials – 144%
▪️ HFCL – 144%
▪️ Viviana Power – 141%
▪️ Kolte-Patil Developers – 141%
▪️ Juniper Green Energy – 136%
▪️ Diamond Power Infrastructure – 134%
▪️ Trishakti Industries – 133%
▪️ Madhusudan Masala – 118%
▪️ Antelopus Selan Energy – 116%
▪️ SG Finserve – 116%
▪️ Multi Commodity Exchange (MCX) – 114%
▪️ SBC Exports – 113%
▪️ Kanohar Electricals – 112%
▪️ Bharat Parenterals – 111%
▪️ KRN Heat Exchanger – 110%
▪️ Accretion Nutraved – 109%
▪️ Infinity Infoway – 106%
▪️ T N Petro Products – 105%
▪️ SEAMEC – 103%
▪️ Anlon Healthcare – 102%
▪️ Sathlokhar Systems – 100%
Good numbers attract attention. Consistent execution creates long-term value.
Have I missed any company that reported more than 100% YoY sales growth in Q2 FY27? Mention it in the comments below.
Disclaimer:
This list is based on the quarterly figures shown in the shared screenshots. For educational purposes only. Not a buy/sell recommendation.
