

Researcher, educator and trader. Opinions are my own.
Web3
Joined February 2012
- Tweets49.1K
- Following3.3K
- Followers187K
- Likes98.1K
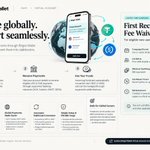



Getting paid internationally shouldn’t mean dealing with complicated banking setups
yes, you heard that right. @BitgetWallet lets eligible users receive USD or EUR payments through its Virtual Account feature and automatically convert incoming funds into stablecoins
the idea is simple = Receive globally. Convert seamlessly.
→ apply for a USD or EUR receiving account
→ receive eligible payments through supported banking networks, including ACH, Fedwire, SWIFT and SEPA
→ get your funds automatically converted into USDT or USDC
→ manage your stablecoins through supported wallet features
USD accounts come with routing and account numbers, while EUR accounts provide IBAN and BIC details
you can apply directly through Bitget Wallet without visiting a physical bank branch, subject to identity verification and regional eligibility
for freelancers, remote workers and Web3 contributors receiving payments from international clients, that could make managing income across borders more convenient
there’s a campaign angle too:
• eligible new users can get a waiver on receiving fees for their first qualifying payment
• the minimum qualifying net deposit is $50 equivalent
• the waiver covers receiving fees on up to $1,000 equivalent
• limited to the first 1,000 eligible users
• reimbursement is credited to the rewards account by the next day (T+1), subject to the official terms
the campaign runs from October 27, 2026, at 20:00 to December 31, 2026, at 23:59 (UTC+8)
important: this isn’t a $1,000 cash reward, and other applicable fees may still apply
the bigger picture?
traditional payment rails and stablecoins are becoming easier to connect
instead of stopping at receiving fiat, you can access a wallet experience where your incoming funds are converted into digital dollars you can hold, transfer or use through supported features
eligibility, supported regions and product terms still matter
but for people earning across borders, bridging payments and crypto in one flow is worth paying attention to
explore Bitget Wallet Virtual Account and check your eligibility:
newshare.bgw.live/en/noahVa/…
🤝 Paid partnership

TECA retweeted

RWA tokenization is growing. But the next phase is about what happens after issuance.
I reviewed the latest RWA.xyz data, Binance Research’s September report, and recent developments from DTCC and the SEC.
Here’s what the numbers actually tell us.
1/ The market is approaching $40B
As of October 26, 2026, RWA.xyz tracks approximately $39.04B in distributed on-chain real-world assets, excluding stablecoins.
That value is spread across 39 networks, with more than 5.3 million asset holders.
But there’s an important distinction: RWA.xyz also reports $389.25B in represented asset value.
These figures measure different things. Represented value can include assets that aren’t freely transferable between wallets, so the two numbers shouldn’t be treated as equivalent.
2/ Ethereum still leads, but other chains are gaining ground
The latest distributed-value figures show:
• @ethereum: $15.9B
• @BNBCHAIN: $6.2B
• @solana: $4.9B
• @Stella: $3.8B
• @avax : $1.6B
@ethereum remains the largest network by distributed RWA value.
However, BNB Chain, Solana and Stellar have established meaningful positions in the market.
The takeaway isn’t that one chain has won. It’s that #RWA distribution is expanding beyond a single network, making interoperability and liquidity increasingly important.
3/ Treasuries remain important, but the market is diversifying
Tokenized U.S. Treasuries and money-market funds remain a major source of demand.
Products such as @BlackRock BUIDL, @circle USYC and @Ondo USDY give eligible investors access to tokenized, yield-bearing instruments, subject to each product’s terms.
Gold-backed tokens, private credit and tokenized equities are also contributing to the market’s expansion.
@BinanceResearch reported that tokenized equities grew 390.4% year-to-date through September 15, 2026.
That growth rate is notable, although it comes from a much smaller base than bonds and money-market funds.
4/ The biggest issue may be capital utilization
This is the metric worth watching.
Binance Research estimated the overall Capital Activation Rate at around 12% in its September report.
In simple terms, only about $12 of every $100 in tracked tokenized asset value was deployed in qualifying on chain financial applications under its methodology.
The remaining capital isn’t necessarily idle or unproductive.
Some assets are held for investment, operate in permissioned environments, or aren’t eligible for DeFi applications.
Still, the data points to a clear opportunity: make more tokenized assets usable in lending, liquidity provision and collateral markets.
Issuance creates supply. Utility creates more reasons to hold and use it.
5/ Traditional financial infrastructure is moving on-chain
Two developments matter here.
In July, DTCC reported successful production trades using tokenized securities held at DTC, ahead of its planned October 2026 service launch.
The service is designed to preserve the entitlements and ownership rights associated with eligible underlying securities.
Separately, on September 17, the SEC issued temporary, conditional exemptive relief for certain venues trading tokenized U.S.
exchange listed stocks through permissioned automated market makers and liquidity pools.
These are meaningful steps toward integrating tokenization with established capital markets.
However, neither development means all securities can now trade freely across public blockchains.
Eligibility, permissions and regulatory conditions still matter.
6/ The infrastructure challenge goes beyond putting assets on a blockchain
A token representing a Treasury fund or a stock doesn’t automatically create deep liquidity.
The market still needs reliable pricing, compliant transfers, custody, legal clarity and connections between different networks and financial applications.
There is also a difference between holding a token and being able to use it as collateral.
These constraints help explain why distributed asset value can grow faster than on chain financial activity.
The next phase will depend on how effectively projects solve these problems, not simply how many assets they tokenize.
7/ What I’m watching next
Three indicators matter more to me than headline issuance figures alone:
• Capital activation: Is more tokenized value entering lending, collateral and liquidity markets?
• Market depth: Can investors enter and exit positions without excessive slippage or restrictive transfer conditions?
• Real adoption: Are institutions and investors using these assets repeatedly, beyond initial issuance and pilot programs?
Forecasts for 2030 range from a few trillion dollars to much higher figures, depending on which asset classes and definitions are included.
Those estimates are scenarios, not guaranteed outcomes.
My conclusion
RWA tokenization is moving beyond experimentation
but the market is still developing the infrastructure required for assets to move efficiently between traditional finance and on chain applications.
The opportunity is not just to bring more assets on-chain.
It is to make those assets transferable where permitted, liquid, useful as collateral and accessible through reliable financial infrastructure.
The next phase of RWA growth may be measured less by how much gets tokenized and more by how much economic activity those tokens actually support.

TECA retweeted
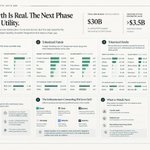
Tokenized stocks are starting to find real use in DeFi, but the numbers need context.
By September October 2026, deposits of tokenized equities across DeFi had reached roughly $248M–$313M, compared with just $15M–$22M in January.
That is significant growth in less than a year. But it is still a small part of the bigger market.
The total tokenized equity market sits around $3B–$3.8B, meaning only about 6–8% of those assets are deployed in DeFi.
So, what is driving the growth?
@binance launched bStocks in June, followed by @RobinhoodApp stock-token push in July.
As more tokenized equities became available onchain, users gained more ways to put those assets to work instead of simply holding them.
The capital is now flowing into several areas:
➯ Liquidity pools account for roughly 65% of deposits.
➯ Lending and borrowing represent about 28%.
➯ xStocks has emerged as a major issuer, with its tokens distributed across multiple DeFi protocols.
➯ @kamino, @0xfluid, @pendle_fi, @Raydium and @Uniswap are among the venues supporting these activities.
The interesting part is what users can do with these assets.
On @kamino, eligible tokenized stocks can serve as collateral for borrowing. @pendle_fi allows users to trade principal and yield separately.
@krakenfx has also introduced vault strategies that use xStocks as collateral to borrow stablecoins and pursue additional yield.
This is where tokenization starts to become more than putting a stock ticker on a blockchain.
The bigger opportunity is composability.
An asset that previously sat in a brokerage account can potentially become collateral, provide liquidity or participate in structured yield strategies.
But there are important risks.
Tokenized stocks are still concentrated across a handful of issuers and chains. Liquidity depends on users and market makers remaining active.
And borrowing against a tokenized equity introduces liquidation risk when the underlying stock falls in value.
There is also a difference between the growth of tokenized equities and the amount of capital actually being used in #DeFi.
Most tokenized stocks are still not deployed in onchain financial strategies.
My takeaway:
Tokenized equities do not need to replace traditional stock markets to become useful in crypto.
They need reliable infrastructure, sufficient liquidity, transparent collateral rules and products that give holders a reason to use them onchain.
The market is still relatively small, but the shift from holding tokenized stocks to actively using them in DeFi is worth watching.


TECA retweeted

Stablecoin deposits are growing across DeFi, but the capital isn’t flowing evenly between assets or lending markets.
The latest 30-day data shows sUSDS leading individual pool inflows, while USDC is attracting deposits across several @Aave, @sparkfinance and @Compound_xyz markets.
The largest inflows:
→ sUSDS / Sky Ethereum: +$383.1M (+8.6%)
→ USDC / Aave Arbitrum: +$38.0M (+20.9%)
→ RLUSD / Spark Ethereum: +$20.0M (+200%)
→ USDC / Aave Base: +$17.3M (+9.7%)
→ USDC / Aave V4 Ethereum: +$11.5M (+35.7%)
→ USDC / Spark Ethereum: +$9.0M (+22.3%)
→ USDT / Aave V4 Ethereum: +$7.6M (+38%)
What’s particularly revealing is the distribution of USDC inflows.
Across the seven USDC pools shown in the latest inflow table, deposits increased by approximately $92M in aggregate TVL.
Arbitrum and Base accounted for $55.3M of that increase, while Ethereum’s newer Aave V4 Core market grew 35.7%.
But deposit growth doesn’t necessarily translate into higher yields.
@Aave’s USDC supply APY on Arbitrum fell from 2.93% to 2.37% despite attracting $38M in additional deposits.
On Base, the opposite happened. USDC deposits grew $17.3M while supply APY increased from 3.96% to 4.17%, with utilisation reaching 90.3%.
That suggests the relationship between available liquidity and borrowing activity differs considerably between markets.
Meanwhile, sUSDS attracted $383.1M into @SkyEcosystem’s savings product, with its APY increasing from 3.60% to 3.80%.
The distinction is important because savings deposits and lending deposits don’t represent identical forms of capital demand.
These figures describe the largest inflowing pools, not net flows across every market. Outflows elsewhere can offset much of the growth.
Stablecoin adoption is one thing. Attracting deposits into specific markets, maintaining utilisation and generating sustainable borrower demand is another.
The distribution of capital across DeFi is becoming just as revealing as the total supply of stablecoins.

TECA retweeted
I’ve been looking into early-stage projects across AI, DeFi, trading infrastructure, RWA, and NFTs.
Rather than list every project I come across, I narrowed this down to 22 projects worth researching, each approaching its sector from a different angle.
1. AI & Agent Infrastructure
➠ @Tensorcash → Working on verification and settlement for AI inference.
➠ @instinct_xyz → Agentic trading infrastructure backed by Y Combinator.
➠ @TryNoahAI → Building apps, smart contracts, and AI agents from prompts.
➠ @AntSeed → A peer-to-peer marketplace for AI inference.
➠ @indexnetwork_ → Connecting personal AI agents through a social layer.
2. AI-Powered Trading
➠ @Ulys_AI → Uses AI agents to turn trading ideas into structured trades.
➠ @silhouette_ex → RFQ block trading for Hyperliquid perpetuals and tokenized stocks.
➠ @weftfinance → Turns trading ideas into rules-based strategies.
➠ @XStableAI → Onchain gold, silver, and FX trading on Solana.
3. DeFi & Real-World Assets
➠ @fhenix → Developing confidential smart-contract computing.
➠ @alloco_fi → Bringing structured investment strategies into tokenized products.
➠ @flexmeow → A lending market where borrowers choose their interest rates.
➠ @multiliquid_xyz → Building swaps for blue-chip RWAs and stablecoins; has reported raising $8M.
➠ @Bramble_fi → A self-custody wallet built for Starknet.
4. Trading, Launchpads & Infrastructure
➠ @signo_fi → AI agents for monitoring DeFi positions and managing transactions within user-defined limits.
➠ @Torchpaddotfun → Combining token launches, trading, and creator rewards on Robinhood Chain.
➠ @IntelTrade → Turning Hyperliquid activity and market events into trading intelligence.
➠ @districtxyz → A Solana and Base launchpad focused on fair launches and builder incentives.
➠ @ImperialPerps → Bringing multiple Solana perpetuals venues into one trading interface.
5. NFTs & Digital Collectibles
➠ @0xCyberThrone → An 8,888-piece robot NFT collection.
➠ @nuloraio → A Monero-focused digital collectibles and NFT launchpad project.
➠ @GigaLegendsLTD → An Ethereum collection from the Gigaverse team.
Early-stage doesn’t automatically mean undervalued, and a strong narrative doesn’t guarantee a working product.
Before getting involved, check what is live, whether users are actually engaging, how the project plans to grow, and whether its token has a clear purpose.
Which of these 22 projects would you research first?

TECA retweeted

➥ Solana hit a record in tokenized asset trading, but the value held onchain has barely moved over the past month.
Q2 2026 saw $5.8B in tokenized asset trading volume, up 114% from the previous quarter, according to Blockworks Research.
But the value of tokenized assets held on @solana has been broadly flat since September.
So where is all that activity going?
[1] Most of the volume came from tokenized equities
Tokenized equities accounted for roughly $4.8B of Q2 trading, more than four times the Q1 figure.
June alone contributed around $3.3B, with tokenized SpaceX shares reportedly driving much of the activity after the company’s June 12 listing.
Solana is also reported to handle around 97% of tokenized equity trading across blockchains.
That’s a big share, but most of the volume came from one category, and June had a major catalyst behind it.
[2] Asset value has stopped growing
Castle Labs data puts Solana’s tokenized asset value at around $4.3B, up from roughly $700M a year earlier.
RWA.xyz figures put it near $4.6B at the end of September, before falling to around $4.39B in mid October.
The market has grown considerably over the year, but the latest figures suggest that growth has slowed.
The totals differ between trackers and dates, so they shouldn’t be treated as one consistent series.
[3] More trading doesn’t necessarily mean more capital is coming in
The same assets can be bought and sold repeatedly without the total value held increasing much.
Existing holders could be trading more often. Or a major listing could have driven turnover without bringing in a similar amount of new capital.
The figures alone don’t tell us which explains the gap.
That’s why the Q2 volume record isn’t enough to conclude that adoption is accelerating at the same pace.
[4] There’s more happening across Solana
@Raydium reportedly led tokenized equity trading, helped by xStocks pairs.
Tokenized Treasuries and fund shares serve a different purpose, bringing traditional financial instruments onchain.
Solana also recorded 9.8B non-vote transactions in Q2, while stablecoin supply remained around $16.3B.
These figures show activity across the network, but they don’t tell us how many people are using tokenized assets beyond trading.
[5] What I’m watching next
Two things:
→ Whether the value of tokenized assets held on Solana starts growing again.
→ Whether trading volume stays elevated without another major listing driving activity.
If volume stays high while assets held remain flat, trading is growing faster than the value staying onchain.
The next quarter should help show whether new capital is catching up with trading activity.

TECA retweeted

BREAKING: @injective JUST LAUNCHED A NEW AI COMPUTE MARKET!
ethereum:0xe28b3b32b6c345a34ff64674606124dd5aceca30 is taking AI infrastructure trading to another level with the launch of the SuperIntelligence Compute Index ($SICI)
For the first time on Injective, traders can gain exposure to a basket of @nvidia GPU rental prices through onchain perpetuals with up to 10x leverage.
Here's what makes $SICI interesting:
The index tracks five major GPUs powering AI infrastructure:
• H100: 40%
• B200: 25%
• H200: 15%
• A100: 10%
• RTX 4090: 10%
Instead of trading AI tokens or NVIDIA stock, users can now trade the actual cost of renting the computing power behind AI development.
So this is the kind of innovation that keeps me bullish on Injective's long-term direction!
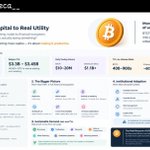
RWA growth is interesting, but real opportunity is making tokenized assets more useful across onchain financial markets.
my investment thesis depends on whether issuers can attract more capital, deepen liquidity, and make these assets practical to trade, borrow against, and use as collateral.
here is how i’m assessing each part of the market
[1] tracking stablecoin growth
@Paxos led weekly market cap growth, adding $249.8M, around 65% of the increase across the top 10 issuers.
by chain, @arc added $247.2M and Solana $99.3M.
holder growth showed a different picture:
→ @Tether added around 1.7M holders
→ @BNBCHAIN added around 1.3M stablecoin holders
→ @circle added approximately 160,700 holders
stablecoins remain an important part of onchain liquidity, but the next question is how effectively that capital supports trading and other financial activity.
[2] watching tokenized funds
Franklin Templeton @FTDA_US and @jpmorgan added $33.9M and $33.6M in market cap, respectively.
by chain:
→ @solana added $453.5M
→ @StellarOrg added $124.5M
@Spiko_finance led holder growth for the second consecutive week, adding 491 holders, followed by @onrefinance with 473 and @Ondo with 402.
the interesting part is how traditional financial products are expanding across different issuers and blockchain networks.
[3] assessing tokenized stock adoption
Binance @bStocksfinance added $127.8M in market cap, while @xStocksFi added $73.4M.
together, they accounted for roughly 94% of the market cap growth among issuers that expanded.
but holder growth was distributed differently:
→ @Backpack added around 58,500 holders
→ @PreStocks added around 47,500
→ Binance bStocks added 27,900
→ xStocks added 12,400
Solana led holder growth by chain, adding approximately 114,600 holders.
capital growth and holder growth don’t always point to the same leaders, which makes both metrics worth tracking.
[4] understanding the liquidity gap
tokenized stocks have surpassed $3.5B in distributed value, but only around $300M is deposited in DeFi, according to the broader figures shared.
that difference matters.
an asset can exist onchain without having enough market depth for efficient trading or meaningful lending activity.
fragmented liquidity across issuers, chains, and pools can increase slippage and make price discovery less reliable.
[5] tracking the infrastructure connecting RWAs to DeFi
different projects are addressing different parts of the market:
→ @DinariGlobal connects stock-backed dShares with regulated markets and DeFi
→ @Ondo expands access to tokenized financial assets
→ @BackedFi brings tokenized stocks and ETFs onchain through xStocks
→ @Uniswap provides infrastructure for onchain trading
→ @Morpho and @kamino expand DeFi lending opportunities
the opportunity becomes more interesting when these layers work together.
deeper liquidity could improve execution, support better price discovery, and make tokenized equities more practical as collateral.
[6] measuring what comes next
i would watch three things:
→ liquidity depth across tokenized stock markets
→ stablecoin pairs and integration across DeFi protocols
→ actual borrowing and trading activity, not just assets issued
more tokenized assets are a good starting point, but issuance alone doesn’t guarantee sustainable demand.
the next stage depends on whether users can trade these assets efficiently, deploy them as collateral, and move capital between onchain markets without unnecessary friction.
issuance brings assets onchain. liquidity makes them useful.
not financial advice.

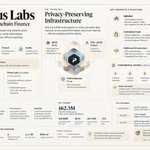
Institutions need to prove their assets are real without exposing every financial position
that’s what @primus_labs is building with zkTLS and fully homomorphic encryption
the idea is simple = Verify the data. Protect the details.
→ prove offchain balances
→ verify protocol reserves
→ keep sensitive positions private
here’s one example:
in oct 2025, @unitas had $18.85M in USDu backing, with roughly 18.5% held offchain
primus used zkTLS to verify binance balances without exposing financial strategies
the reported backing later reached $55.76M, with around 75% held offchain
primus PoR now reports $62.3M verified across unitas, unitas XGLD and RWAlpha
there’s a privacy angle beyond reserves too:
• confidential vaults let users stake encrypted stablecoins without revealing position sizes
• zkTLS verifies information from external platforms without exposing the underlying data
• FHE helps applications compute on encrypted information
and it’s not limited to yield vaults
@primus_labs and @allscaleio tested confidential stablecoin payroll on BNB Chain
→ all 4 sample payments were recorded onchain
→ individual salary amounts stayed encrypted
→ authorized users recovered the correct figures
wallets, recipient addresses and transaction records remained visible
so the goal isn’t to hide everything
it’s to make financial activity verifiable without exposing every sensitive detail
primus has also raised ~$6.5M in pre-seed and seed funding, with backers including Dispersion Capital, Symbolic Capital and VanEck
in august 2026, it joined the YZi Labs incubation ecosystem
AlphaNet, Confidential Vault and its ongoing creator campaigns are bringing more users into the ecosystem
the bigger opportunity is making onchain finance work for institutions that need both transparency and confidentiality
proof without exposure is an interesting direction to watch.
s.kaito.ai/tEyqRWe

TECA retweeted

𝗧𝗼𝗸𝗲𝗻𝗶𝘇𝗲𝗱 𝘀𝘁𝗼𝗰𝗸𝘀 𝗮𝗿𝗲 𝗺𝗼𝘃𝗶𝗻𝗴 𝗯𝗲𝘆𝗼𝗻𝗱 𝗵𝗼𝗹𝗱𝗶𝗻𝗴 𝗮𝗻𝗱 𝘁𝗿𝗮𝗱𝗶𝗻𝗴.𝗬𝗼𝘂 𝗰𝗮𝗻 𝗻𝗼𝘄 𝗯𝗼𝗿𝗿𝗼𝘄 𝗮𝗴𝗮𝗶𝗻𝘀𝘁 𝘁𝗵𝗲𝗺 𝗮𝗻𝗱 𝗯𝘂𝗶𝗹𝗱 𝗹𝗲𝘃𝗲𝗿𝗮𝗴𝗲𝗱 𝗲𝗾𝘂𝗶𝘁𝘆 𝗽𝗼𝘀𝗶𝘁𝗶𝗼𝗻𝘀 𝗱𝗶𝗿𝗲𝗰𝘁𝗹𝘆 𝗼𝗻𝗰𝗵𝗮𝗶𝗻.
I spent some time researching the latest development from @pendle_fi, and what caught my attention wasn't just the leverage. It was how three pieces of financial infrastructure are now working together on Base.
On October 22, Pendle introduced PendleLoop, allowing eligible users to build leveraged positions in tokenized US equities through @aave V4.
The supported assets include:
• AAPLc — Apple
• NVDAc — Nvidia
• GOOGLc — Alphabet
• TSLAc — Tesla
• AMZNc — Amazon
• MSFTc — Microsoft
• METAc — Meta
Here's what I found.
➊ 𝗙𝗶𝗿𝘀𝘁, 𝗵𝗼𝘄 𝗱𝗼𝗲𝘀 𝘁𝗵𝗲 𝗹𝗲𝘃𝗲𝗿𝗮𝗴𝗲 𝘄𝗼𝗿𝗸?
@aave already introduced lending markets for these equities in September.
@pendle_fi didn't create a new lending market. It built an interface that combines the transactions required to increase exposure.
Instead of manually buying tokens, supplying collateral, borrowing and repeating the process, users can manage the position through PendleLoop.
The mechanism works like this:
→ Purchase a tokenized stock.
→ Supply the tokens as collateral on $Aave V4.
→ Borrow $USDC against that collateral.
→ Use the borrowed $USDC to purchase additional stock tokens.
→ Repeat within the permitted collateral limits.
The result is a larger equity position than the capital initially committed.
At launch, available leverage ranged from approximately 2.6x to 4.2x, depending on the asset.
But leverage isn't free. Borrowing rates are variable, and a decline in collateral value can trigger liquidation.
➋ 𝗪𝗵𝗮𝘁 𝗮𝗰𝘁𝘂𝗮𝗹𝗹𝘆 𝗯𝗮𝗰𝗸𝘀 𝘁𝗵𝗲𝘀𝗲 𝘁𝗼𝗸𝗲𝗻𝗶𝘇𝗲𝗱 𝘀𝘁𝗼𝗰𝗸𝘀?
This is another detail worth understanding.
@coinbase Tokenized Stocks aren't simply synthetic assets following equity prices.
Each token represents a certificate issued by Coinbase Onchain SPV Ltd, with underlying shares held through Alpaca Securities (an SEC-registered broker-dealer).
The issuer holds those shares under a trust arrangement for token holders.
Corporate actions are also accounted for.
For example:
Dividends are reinvested into additional underlying shares (after applicable fees and taxes),rather than distributed directly to token holders.
This means the tokens provide economic exposure to the underlying equities, although their legal rights and redemption arrangements differ from holding ordinary shares through a brokerage account.
➌ 𝗡𝗼𝘄, 𝘄𝗵𝗮𝘁 𝗮𝗯𝗼𝘂𝘁 𝘁𝗵𝗲 𝗹𝗲𝗻𝗱𝗶𝗻𝗴 𝗺𝗮𝗿𝗸𝗲𝘁?
Aave V4's Equities Hub on @base supports the seven stocks as collateral for USDC borrowing.
At launch, the market had approximately:
• $29M in aggregate equity collateral caps.
• $32M USDC supply cap.
• $21M USDC borrow cap.
• Collateral factors ranging from 65% to 79%.
These are market limits, not actual deposits or borrowing volume.
And the collateral factors matter because they determine how much borrowing capacity each asset receives.
A token with a lower collateral factor generally requires more collateral for the same loan.
This also explains why PendleLoop cannot offer identical leverage across every stock.
➃ 𝗪𝗵𝗮𝘁 𝗱𝗼𝗲𝘀 𝘂𝘀𝗶𝗻𝗴 𝗣𝗲𝗻𝗱𝗹𝗲𝗟𝗼𝗼𝗽 𝗰𝗼𝘀𝘁?
Pendle is currently waiving its service fees on eligible non-PT looping positions until December 31, 2026.
However, that doesn't eliminate the cost of leverage.
Users still face:
• Variable USDC borrowing interest
• Transaction costs and slippage
• Liquidation risk when collateral values decline
Pendle has also announced borrowing incentives distributed through @Merkl_xyz.
Those incentives can reduce effective financing costs for qualifying positions, but they shouldn't be treated as permanent income.
➎ 𝗢𝗻𝗲 𝗿𝗶𝘀𝗸 𝗜 𝘁𝗵𝗶𝗻𝗸 𝗱𝗲𝘀𝗲𝗿𝘃𝗲𝘀 𝗺𝗼𝗿𝗲 𝗮𝘁𝘁𝗲𝗻𝘁𝗶𝗼𝗻
The lending market operates 24/7, but the underlying US stock market doesn't.
Aave uses Chainlink's tokenized equity price feeds, which publish prices 24/5.
During weekends and US market holidays, the feeds retain their last published prices.
That creates a pricing gap:
• A stock could experience a major development outside regular market hours
• while its onchain collateral valuation remains unchanged until the feed updates.
For leveraged positions, a sharp repricing when the feed resumes can become a liquidation problem.
So 24/7 access doesn't mean continuous price discovery or protection from market gaps.
✦ Conclusion
What I find significant is how the responsibilities are divided:
→ @coinbase handles the tokenized equity structure.
→ @aave provides the collateral and borrowing infrastructure.
→ @pendle_fi makes the transactions accessible through one interface.
Each component existed before this integration, but combining them reduces the work required to use tokenized equities in DeFi. And I think that distinction matters.
Issuing more tokenized stocks doesn't necessarily create more demand for them. The stronger test is whether holders are willing to supply those assets as collateral, borrow against them, and maintain positions after promotional incentives expire.
That's what I'll be monitoring:
▸ collateral deposits
▸ actual borrowing demand
▸ utilization
▸ how these markets behave during periods of equity volatility
Because the ability to tokenize a stock has already been demonstrated. Whether that stock can support a liquid, sustainable lending market is the more important question.

There are interesting projects building across AI, DeFi, trading infrastructure, RWA, and NFTs.
here are some early-stage projects worth researching, grouped by what they’re building.
1. AI & agent infrastructure
➢ @TryNoahAI — Build and deploy dApps, smart contracts, and AI agents from prompts.
➢ @instinct_xyz — Agentic trading harness designed for individual traders. Backed by Y Combinator.
➢ @AntSeed — P2P AI inference marketplace. Raised $2.4M.
➢ @Tensorcash — Verification and settlement layer for AI inference.
➢ @CommonFoundry — Live GPU-powered proof-of-work network, with AI inference coming soon.
➢ @indexnetwork_ — Social layer connecting personal AI agents.
2. AI-powered trading
➢ @weftfinance — Turns trading theses into rules-based strategies, monitoring market conditions and executing trades.
➢ @XStableAI — AI-native onchain gold, silver, and FX trading on Solana. Currently in public beta.
➢ @listendotmoney — Agentic DeFi trading platform.
➢ @Ulys_AI — AI agent that builds trades from your ideas.
➢ @silhouette_ex — RFQ block trading for Hyperliquid perpetuals and tokenized stocks.
3. DeFi, RWA & financial infrastructure
➢ @multiliquid_xyz — Instant swaps for blue-chip RWAs and stablecoins. Raised $8M from Polychain and others.
➢ @alloco_fi — Infrastructure for structured, tokenized investment products shaped by hedge fund strategies. Associated with Easy Residency and YZi Labs.
➢ @paxoslabs — Platform for onchain asset distribution and liquidity.
➢ @flexmeow — Fixed-rate money market where borrowers choose their own interest rates.
➢ @fhenix — Confidential smart-contract computing, with CoFHE live on Ethereum and Arbitrum mainnet.
➢ @Bramble_fi — Self-custody wallet native to Starknet, featuring transaction previews and shielded balances.
4. Launchpads, gaming & emerging ecosystems
➢ @AscendLaunch — Launchpad for projects building in the @Enter_Elysium ecosystem, with incubation, funding, and post-launch support.
➢ @Torchpaddotfun — Trading and token launchpad on @RobinhoodCrypto Chain, with creator rewards and automatic $TORCH burns.
➢ @districtxyz — Solana and Base launchpad backed by a16z, Initialized, and Alliance, with fair launches and builder incentives.
➢ @Evolutdotfun — Memecoin launchpad.
➢ @eloscapeHQ — Virtual mining protocol on Elysium.
➢ @traded_gg — Global exchange for collectibles.
5. More projects to research
➢ @ChopLogsApp — Volatility farming protocol on Robinhood Chain that lets users earn fees through token wrapping, unwrapping, and trading activity.
➢ @IntelTrade — Real-time intelligence layer for Hyperliquid, turning onchain data, trader tracking, and market-moving events into actionable insights.
➢ @ImperialPerps — Unified Solana perpetuals terminal and router that connects multiple trading venues through one interface and collateral pool.
➢ @signo_fi — AI agents that monitor DeFi positions, send alerts, prepare transactions for approval, and execute within user-defined limits.
➢ @suno_finance — Onchain solar infrastructure protocol connecting investment capital to solar projects and electricity-backed yield.
6. NFT watchlist
➢ @nuloraio — Monero-based digital collectibles and NFT launchpad, with its Genesis waitlist open.
➢ @0xCyberThrone — 8,888 handcrafted robot NFTs, with a free omnichain mint via Unvault.
➢ @Villagers_RH — Upcoming 9,999-piece collection on Robinhood.
➢ @OranguNation — Orangutan-themed animated universe. Supply, chain, and mint price are yet to be announced.
➢ @GigaLegendsLTD — Flagship collection from the Gigaverse team, minting on Ethereum mainnet.

TECA retweeted

💎 8 Early Opportunities
Join the waitlists 👇
🔷 LEBREL ( @LebrelAI )
> Uncensored AI platform with encrypted, attested, and verifiable responses signed on Solana
🔗 early.lebrel.ai/r/24R8TG
----------------------
🔷 NULORA ( @nuloraio )
> Genesis NFT launchpad for digital collectibles on Monero
🔗 nulora.io
----------------------
🔷 OnePump ( @onepumpcc )
> First memecoin launchpad on Canton Network
🔗 oneswap.cc/waitlist
----------------------
🔷 Forever ( @forevercultfund )
> Framework for autonomous onchain funds where AI agents propose strategies and holders vote on execution
🔗 enterforever.com
----------------------
🔷 Ambi ( @hello_ambi )
> Ambient AI that understands your real-time context across devices, remembers what matters
🔗 ambi.ai/waitlist
----------------------
🔷 RaidLords ( @RaidLords )
> Multiplayer strategy game on Robinhood Chain
🔗 raidlords.com
----------------------
🔷 OWNIT ( @ownit_xyz )
> On-chain trading platform on Solana
🔗 ownit.xyz/
----------------------
🔷 VelocityOS ( @velocityosxyz )
> Autonomous AI agent for crypto trading and scheduled investing
🔗 velocityos.xyz/
----------------------
✅ Done
💙 Don't miss any updates 👇
t.me/atoms_research


TECA retweeted
One thing worth paying attention to as @grvt_io expands is how users actually bring capital onto the exchange.
Grvt's latest update introduces two additional deposit routes:
→ $USDG from Robinhood Chain
→ $USDC from Arc
This might look like a minor integration, but there's a broader infrastructure angle here.
Robinhood Chain is building around tokenized financial assets, while Arc focuses on stablecoin-based financial infrastructure.
Supporting deposits from these networks gives users additional ways to fund their Grvt accounts without first moving assets through another supported chain.
And that matters as $Grvt expands its trading and investment products.
An exchange can offer hundreds of markets, but access to those markets also depends on how easily users can bring capital onto the platform.
The next thing worth tracking is whether these additional deposit routes translate into meaningful inflows and active trading accounts.
Expanding market access is one part of building an exchange. Making it easier for capital to reach those markets is equally important.


TECA retweeted
I don't think VCs expanding beyond crypto means the industry is cooked.
If anything, crypto could benefit from becoming less dependent on VC-funded token launches.
We've seen projects raise millions privately, launch at ridiculous FDVs, distribute airdrops, and then expect retail investors to provide the liquidity.
Who exactly is supposed to buy those valuations?
VC capital leaving speculative launches isn't necessarily bearish. It could force:
• better valuations
• more sustainable token economics
• projects that actually need users
And personally, I think we're getting closer to a market bottom.
Not because VCs are changing their names, but because the speculative funding model that supported so many overpriced launches is becoming harder to sustain.

You know crypto is cooked when some of its biggest VCs start shifting their attention and money to other industries.
a16z crypto just rebranded to a16z Frontier, expanding into AI, robotics and other industries.
Paradigm raised a $1.2B fund in July that also covers AI and robotics, while Haun Ventures has expanded beyond crypto.
For context, a16z raised $4.5B for its crypto fund in 2022, compared to $2.2B for its latest fund.
These are some of crypto's biggest investors.
They're not abandoning crypto, but they're increasingly looking elsewhere.
And that could make fundraising even harder for crypto projects, especially those with nothing to offer beyond launching a token.


TECA retweeted

Two tokenized stocks can track the same share price while offering very different legal rights, custody protections, and redemption access.
Even 1:1 backing doesn't guarantee holders own the underlying shares or can redeem them on demand.
So what actually separates these products?
Let's break it down.
—
● The Infrastructure Behind Tokenized Stocks
Four layers connect traditional equities to onchain markets:
Traditional stock market -> Broker and custodian -> Issuer and legal structure -> Onchain token
Each layer serves a different purpose, making three distinctions important:
• Backing: Are the underlying shares actually held?
• Ownership: What legal rights does the token holder receive?
• Redemption: Can holders exchange tokens for cash or underlying shares?
A token can be fully backed without granting direct shareholder rights or unrestricted redemption.
Understanding this distinction starts with how shares become tradable tokens.
—
● How Tokenized Stocks Move From Shares to Redemption
The process generally follows four steps:
1. Acquire: The issuer or broker purchases and custodies the underlying shares.
2. Mint: Eligible participants complete KYC/AML checks before tokens are issued.
3. Trade: Tokens trade across supported CEXs or DEXs, depending on liquidity and restrictions.
4. Redeem: Eligible holders exchange tokens for cash, stablecoins or securities under the product's terms.
Importantly, holders have two potential exit routes:
• Secondary sale: Sell tokens to another buyer at the prevailing market price.
• Direct redemption: Return tokens to the issuer through its approved redemption process.
The distinction matters because selling requires market liquidity, while redemption requires issuer access.
—
● Tradable Doesn't Mean Redeemable
A token can remain freely tradable even when direct redemption is restricted by KYC/AML requirements, jurisdiction or wallet whitelisting.
Holders without redemption access must depend on secondary-market buyers to exit.
This creates another problem of limited arbitrage.
When eligible participants cannot freely mint or redeem, token prices can diverge from the underlying shares despite continued trading.
The result is that two products tracking the same stock can behave differently under market stress.
—
● Same Asset Exposure, Different Rights
Tokenized-stock providers use different legal and redemption structures.
• @xStocksFi: Supports cash redemption and an in-kind redemption route through xPort, subject to eligibility.
• @Ondo : Uses structured notes issued through a BVI SPV, with redemption governed by product terms.
• @RobinhoodApp: Offers Jersey-issued debt securities providing economic exposure rather than direct shareholder rights.
• @DinariGlobal: Redemption reportedly involves selling custodied shares and distributing proceeds to eligible holders.
• @MEXC: Lists third-party tokenized stocks alongside its separate RealStocks offering, without necessarily acting as issuer or custodian.
Although these products provide similar market exposure, their ownership claims, custody arrangements and redemption rights differ.
Current product terms remain essential for accurate comparisons.
—
● The Hidden Risk: Custody Concentration
Different issuers do not necessarily mean different custody arrangements.
Multiple tokenized-stock providers may depend on the same underlying broker or custodian.
This creates concentrated intermediary exposure, where holding several different tokens may provide less diversification than investors assume.
The next question is whether custody protections adequately address that risk.
—
● What Custody Protections Actually Cover
Several mechanisms aim to protect underlying assets, but they serve different purposes.
• Segregated accounts: Separate designated assets from others, subject to legal and insolvency rules.
• Security agents: May enforce collateral rights or liquidate assets under specified conditions.
• Proof of reserves: Verifies assets held at a particular moment, but doesn't establish unencumbered ownership or redemption rights.
None of these protections independently guarantees asset recovery if an issuer fails.
Their effectiveness ultimately depends on enforceable legal claims and the underlying custody structure.
—
● Redemption Access in Numbers
Reported industry data highlights the gap between token issuance and actual redemption access.
• ~880 tokenized-stock deployments reportedly existed as of August 2026.
• ~31 reportedly supported open issuer redemption, according to OnChain Benchmark.
• ~94% of tokenized US equity custody or clearing was reportedly linked to Alpaca Securities.
These figures require source verification, but they highlight two important questions: how widely redemption is available and how concentrated the underlying infrastructure has become.
—
● Where Stablecoins Fit Into the Picture
Stablecoins increasingly provide a settlement layer for tokenized financial assets, but their legal obligations remain distinct.
The GENIUS Act establishes rules covering payment stablecoin reserves, redemption and custody, with @USOCC involved in implementation.
While stablecoins can facilitate tokenized-stock settlement, stablecoin redemption rights do not extend automatically to the underlying equity tokens.
The reported January 18, 2027 effective date also requires confirmation against official OCC documentation before publication.
—
Tokenization makes equity exposure transferable onchain, but it doesn't eliminate the legal, custody and redemption structures supporting it.
As tokenized equities scale, adoption will depend on more than trading access or 1:1 backing.
The real test is whether holders can understand, exercise and enforce their rights when liquidity disappears or intermediaries fail.


TECA retweeted
Ethereum recorded ~$49.5B in DeFi TVL on Oct 23, 2026, while Arbitrum One held ~$1.45B on Oct 24.
but TVL alone doesn’t explain what makes each ecosystem different.
the protocols driving activity reveal how each is developing its own role in onchain finance.
@ethereum hosts major financial infrastructure:
→ liquid staking: @LidoFinance
→ lending: @aave, @Morpho, @sparkdotfi
→ restaking: @eigenCloud
→ trading/liquidity: @Uniswap
→ stablecoins/collateral: @SkyEcosystem
→ synthetic dollars/yield: @ethena
these protocols support staking, lending, liquidity, stablecoins, and yield generation
@arbitrum has a strong ecosystem built around DeFi and specialized financial markets:
→ DEXs: @Uniswap
→ lending: @aave, @Morpho, @0xFluid, @compoundfinance, @Dolomite_io
→ perpetuals: @GMX_IO, @Variational_io
→ yield trading: @pendle_fi
other participants include @gains_trade, @Ostium, @muxprotocol, @borosfi, @Overtime_io, and @RAILGUN_Project
together, they support trading, lending, derivatives, yield strategies, and privacy-focused transactions
the ecosystems are also expanding beyond traditional DeFi
Ethereum continues to support staking, stablecoins, lending, and institutional financial infrastructure
Arbitrum is expanding through real-world assets, specialized applications, and Orbit chains
@RobinhoodCrypto, built using Arbitrum technology, processed ~793.7M transactions in Q3 2026. Arbitrum’s September revenue reportedly exceeded $5M, largely driven by Orbit activity
Arbitrum One has highlighted 7,400+ RWAs, while its Stablecoin Growth Program encourages $USDG adoption through a 2M $ARB incentive pool
Ethereum provides settlement infrastructure and hosts major financial protocols
Arbitrum extends that ecosystem with lower-cost transactions and specialized financial markets
both play different roles in the development of onchain finance
the protocols attracting liquidity, users, and transaction volume will be worth watching

TECA retweeted
A company paying salaries onchain shouldn't have to expose every employee's paycheck.
That's one of the practical problems @primus_labs and @allscaleio tested on BNB Chain.
On September 1, both teams completed a technical validation of confidential stablecoin payroll, involving four fictional employees and four sample payments.
The results were straightforward:
• All four payments were recorded onchain.
• Individual salary amounts remained encrypted.
• Authorized users successfully recovered the correct salary figures.
✦ So how does this work?
AllScale handles payroll preparation, settlement, and reconciliation, while Primus uses FHETransform to encrypt salary amounts before they’re submitted to the smart contract.
Employees can then access their salary details by signing a wallet message, without paying gas to view them.
However, this doesn’t make payroll completely anonymous.
- Company wallets
- Recipient addresses
- Timestamps
- Transaction records
…remain visible. The protection applies to compensation amounts.
That’s an important distinction.
Businesses can retain public settlement records without exposing individual salaries.
The validation involved only four sample payments, so larger-scale deployment and operational readiness still need further testing.
Now, with @primus_labs Epoch 2 underway, there's also an opportunity for creators researching these technical developments.
✦ Here’s what participants should know:
→ 0.3% of the $PRIM supply is allocated to the campaign.
→ The top 450 creators across three language regions qualify for rewards.
→ Your four highest-scoring eligible posts determine your Mindshare score.
→ Each creator can submit up to 10 posts per epoch.
There’s also a referral multiplier tied to Primus XP activity, which can contribute to your final score.
For me, the useful part of this campaign is having more reasons to examine what Primus is actually building, from confidential payroll to verifiable offchain data.
If you're planning to participate in Epoch 2, you can join through my referral link:
s.kaito.ai/RsenLO4
