

Finding Systematic Edges In Markets. Posts are Ideas & opinions only. Not investment advice.
Joined April 2026
- Tweets175
- Following332
- Followers236
- Likes222






Quant retweeted

The nodule collection industry builds on more than 50 years of innovation in other offshore industries, drawing on proven technologies and processes widely used today. Among them are riser systems like the one we will use, which have transported materials vertically over several kilometres for decades. $TMC #deepseamining

Quant retweeted

This is how we gently collect these remarkable rocks

The nodule collection industry builds on more than 50 years of innovation in other offshore industries, drawing on many proven technologies and processes widely used today. In our latest video, $TMC Chief Offshore Innovation and Technology Officer Rutger Bosland explains how the collector, riser, and production vessel work together to gently lift nodules from seafloor to surface. #deepseamining
Quant retweeted
Many $TMC investors have questions about USG funding for the Brownsville plant, the USA-A certification and the USA-B lawsuit.
Some speculate if these issues can explain the falling stock price. I personally believe the decline is not based on anything fundamental, and we have seen periods like this over the years where negativity can feed on itself. While I don't have tangible news to share just yet, I can offer some color on why I remain very confident.
USG funding for the Brownsville plant: TMC USA, together with our partner Mariana Minerals, are committed to building a domestic nodule processing and refining facility in the United States, but with one caveat. It has to be in the best interests of our shareholders. The PFS/FS studies for staged construction are well under way, with a talented and motivated team working hard on the Brownsville project. But at the end of the day, the capital requirement is substantial and USG support is a prerequisite. Engagements with multiple U.S. agencies continue. The process is taking longer than we expected, but we aren't the only priority for these Government agencies, and it's evident that these agencies remain fully committed to resolving America's critical minerals shortages, and seafloor nodules remain a vital part of that solution. As CEO (and a substantial shareholder), my number one fiduciary duty is to the shareholders, and it is my job to minimize dilution as we build what could become a new American mining major. Access to capital matters, but so do deal terms. While these USG engagements are in progress, we do not intend to pursue other capital markets transactions. Our cash position remains robust.
Japan remains open to us: As I made clear at our last earnings call, the capital-light option of sending nodules to Japan for processing on a tolling basis remains available to us. Our working relationship with PAMCO remains excellent, and this option provides us with maximum flexibility as we work towards first production.
USA-A certification: Many of you expected certification in June based on the 100-day certification process envisioned in the DSHMRA statute. What we need to appreciate is that our consolidated application is the first of its kind under the new rules just adopted by NOAA in January this year. Getting the details right matters, even when it takes time. We remain in regular communication with NOAA and remain very optimistic about continued progress toward certification.
USA-B litigation: Most mining permits in the United States are challenged by environmental NGOs; that's simply part of doing business here. We anticipated legal challenges and are prepared. In our view, the lawsuit against NOAA mischaracterizes the process. NOAA has not “greenlit” exploration—it certified our application to advance to further review. The process was thorough. Public comment has taken place, and environmental review is underway. A complaint is not a court ruling, and this case does not impact the USA-A application.
Your voice matters, too. Public comments on the USA-A consolidated application are open through October 19, with a virtual hearing today. I encourage you to read the materials and participate via the link in the comments.
My confidence remains strong. I’m invested alongside you—and focused on disciplined funding and delivering a critical minerals project at scale.
#deepseamining

Quant retweeted
TMC Announces Appointment of Liam Mallon, Former President of ExxonMobil Upstream, to its Board of Directors.
Read the press release: investors.metals.co/news-rel… #deepseamining

Quant retweeted
Thanks to the @NYTimes for inviting me to speak at Climate Forward yesterday.
I’ve always believed we need to hold our beliefs lightly and remain open to new evidence as it emerges.
The evidence increasingly supports polymetallic nodules as the best way to meet growing demand for the critical metals that power our energy, technology and industrial systems.
The future is metallic.
nytimes.com/2026/09/23/clima… $TMC

Quant retweeted

$TMC 3 Clips from the Water Tower Research interview with Craig Shesky, CFO @themetalsco


Quant retweeted

$TMC saw 75% more options volume today than normal, trading a total of 39,743 contracts of which 97% were calls.
$TMC Reuters Reported That DOE Is Awarding $500M for US Battery Materials Processing yesterday and Explicitly Mentioned Deep Sea Nodules as Potential Future Feedstock for a $100M Cobalt Refinery. TMC Presented Its Battery Grade Nodule Results and highlighted it Today. Hours Later TMC Rallied on Heavy Volume, Suggesting Institutional Accumulation on Alpha? with Brownsville Funding also in play.
Yesterday Reuters reported that the US Department of Energy is awarding $500M across 7 domestic critical mineral and battery material projects.
One award immediately stood out to me:
$100M for Jervois to build a US cobalt refinery.
DOE Assistant Secretary Audrey Robertson said the facility could process:
Deep sea nodules.
The official DOE funding program is:
DE-FOA-0003585
Battery Materials Processing & Battery Manufacturing and Recycling Grants.
Total funding:
$500M
One of the actual funding categories:
Domestic Critical Minerals Processing from Raw Feedstocks.
The purpose is to build US demonstration/commercial scale facilities that process critical minerals into materials needed for batteries and other strategic uses.
Again, keyword was processing.
Now lets go back to Trumps deep seabed mining Executive Order.
This is where things get much more interesting.
Executive Order 14285, signed April 24, specifically directed DOE and the Department of Defense to support domestic processing capabilities for seabed minerals.
And it didnt stop there.
Section 3(d)(ii) specifically directed them to explore the use of:
Grants, Loans, Defense Production Act authorities, Procurement
AND
Other financing authorities for domestic seabed mineral processing.
Thats an actual White House Executive Order.
This is not speculation, this is a fact.
Now compare that with what TMC told us just last week.
TMC:
“The Company is actively engaged in funding processes with multiple U.S. agencies named in President Trump’s Executive Order 14285 regarding plans to build nodule processing and refining capacity in the United States.”
Gerard also reiterated:
Future domestic onshore capital spending is contingent on a MAJORITY of the funding coming from US government sources.
And:
“Advanced funding processes” are currently in progress with multiple US agencies.
So we already know there are confidential financing processes underway.
We just dont know the agencies, structures or dollar amounts yet.
And where would that US processing/refining capacity potentially be built?
Brownsville, Texas.
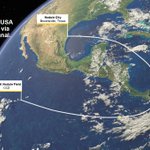
TMC is advancing plans with Mariana Minerals for what it calls Nodule City at the Port of Brownsville.
TMC currently has an exclusive right of negotiation over approximately 1,466 acres.
The company is evaluating a potential:
- 12Mtpa integrated US nodule processing and refining industry park.
- Pre feasibility work is nearing completion.
- Feasibility level work on the first smelting stage is already underway.
No final investment decision has been made.
And importantly:
TMC has repeatedly said the build remains contingent on US government financial support.
Now add this weeks metallurgy presentation.
TMC and Kingston Process Metallurgy presented their successful conversion of nodule derived manganese silicate into:
High purity, battery grade manganese sulfate.
TMC’s SEC filings already say its nodule processing flowsheet is expected to form the basis of its future onshore processing facilities.
And over time TMC has discussed potentially expanding the products from that flowsheet into:
Cobalt sulfate
Nickel sulfate
Manganese sulfate
Copper products
Silicomanganese
And eventually even precursor cathode active materials.
And manganese sulfate puts another product directly into the battery materials category.
Then DOE announces its $500M battery materials processing awards.
And gives:
$100M
to build a domestic COBALT refinery.
One of TMC’s four main metals.
Then a senior DOE official specifically says that refinery could eventually process:
Deep sea nodules.
Thats the part I keep coming back to.
Because Trump’s EO specifically instructed DOE to support US seabed mineral processing.
TMC is trying to build US seabed mineral processing.
And now DOE is putting $100M behind a domestic cobalt refinery while publicly identifying deep sea nodules as a potential future feedstock.
The government financing mechanism is there.
The domestic processing priority is there.
And now the deep sea nodule reference is there too.
I think this is where Brownsville starts becoming more interesting to the market.
TLDR:
DOE is putting $500M into US critical mineral and battery material processing.
A $100M cobalt refinery award comes with an unusually specific comment from a senior DOE official:
It could eventually process deep sea nodules.
Trump’s EO already specifically directed DOE and Defense to explore grants, loans, DPA and other financing tools for domestic seabed mineral processing.
Meanwhile TMC says its proposed Brownsville nodule processing/refining hub is contingent on majority US government funding and that advanced confidential funding processes with multiple agencies named in that exact Executive Order are already underway.
And in the same week TMC is presenting another successfully demonstrated battery grade product from its nodule processing pathway.
This tweet was pure speculation. Im connecting public dots here. No filing OR public info to confirm institutions drove todays move or that Brownsville funding is secured.

$TMC Presents Its Latest Processing Results to the Metallurgy Industry:
This week TMC’s Matt Boulby and Kingston Process Metallurgy’s James McNeice presented the results of TMC’s manganese processing work at COM 2026 in Calgary.
The work successfully converted nodule derived manganese silicate into high purity, battery grade manganese sulfate.
Summarized Recap:
1) Manganese was already a product for TMC, not a waste stream.
When TMC processes nodules, the first major processing stage separates them into:
A high grade nickel copper cobalt alloy/matte
AND
A manganese silicate product containing roughly 40% manganese.
That manganese silicate can already be used as feedstock to produce silicomanganese alloy for steelmaking.
Now TMC has demonstrated another potential route:
Take that same nodule derived manganese silicate and convert it into high purity manganese sulfate for batteries.
So the manganese doesnt have just one potential end market anymore.
Steelmaking through manganese silicate/silicomanganese.
OR
Battery materials through high purity manganese sulfate.
Thats product optionality.
2) The upstream manganese processing has already been demonstrated at much larger scale.
During PAMCO’s 2,000 tonne nodule processing campaign in Japan, PAMCO successfully smelted 450 tonnes of calcine into:
35 tonnes of NiCuCo alloy
AND
320 tonnes of manganese silicate.
So producing the manganese silicate itself isnt just a small laboratory concept.
The important distinction is that converting that manganese silicate into high purity manganese sulfate has so far been demonstrated at bench scale.
Commercial scale up still has to be proven.
3) This builds on TMC’s previous work showing that nodules can be converted into multiple high value products.
TMC has already demonstrated routes to produce:
NiCuCo alloy/matte
Battery grade nickel sulfate
Battery grade cobalt sulfate
Copper cathode
Manganese silicate for steelmaking
And now high purity manganese sulfate for batteries.
TMC previously reported >99% extraction of nickel, cobalt and copper from nodule derived matte during its hydrometallurgical testing.
Adding manganese sulfate means TMC has now demonstrated a pathway to produce nickel, cobalt AND manganese in sulfate form.
Those are the key metal feedstocks used in NMC type precursor cathode active materials.
4) The US manganese angle is probably the most important part.
According to the USGS:
The United States was 100% net import reliant for manganese content in 2025.
The US has not produced manganese ore containing 20%+ manganese domestically since 1970.
Manganese is also officially on the US Critical Minerals List.
So while nickel, cobalt and copper usually get most of the attention around TMC, manganese could become strategically very important.
5) And manganese is by FAR the largest contained metal in TMC’s current USA-A + USA-B resource estimate.
TMC’s latest filing estimates those mineral resources contain approximately:
345M tonnes manganese
15.5M tonnes nickel
12.8M tonnes copper
2.0M tonnes cobalt
Important distinction: those are estimated contained metals within measured, indicated and inferred mineral resources, not 345M tonnes of manganese reserves.
But it shows the scale of the manganese opportunity.
6) This could also matter for Brownsville.
TMC and Mariana Minerals are currently working toward a potential integrated US nodule processing and refining industry park in Brownsville, Texas.
A processing system that can potentially take the same nodule feedstock and produce multiple different product formats gives TMC more flexibility around what ultimately gets produced in the US.
Steel products.
Battery materials.
Nickel/cobalt/copper products.
Potentially manganese sulfate.
The exact commercial configuration hasnt been finalized and TMC has not yet demonstrated commercial scale manganese sulfate production.
But every additional product pathway potentially increases what can be extracted from the same nodule resource.
7) The bigger story is that TMC continues demonstrating that polymetallic nodules are not a single product ore.
One nodule contains nickel, copper, cobalt and a very large amount of manganese.
And TMC is building processing routes that can potentially turn those metals into different products depending on what industry needs them.
Manganese for steel.
Manganese for batteries.
Nickel and cobalt for batteries/industry.
Copper for electrification and infrastructure.
All from the same nodule feedstock.
And in manganese specifically, this comes at a time when the US remains 100% net import reliant.
TLDR: $TMC has demonstrated that the manganese silicate produced from its nodules doesnt have to be limited to steelmaking. It can also be converted into high purity, battery grade manganese sulfate.
That potentially gives TMC two major markets for the manganese stream from the same resource: steel AND batteries.
With ~345M tonnes of estimated contained manganese across TMC’s current USA-A/USA-B mineral resources, and the US currently 100% net import reliant for manganese content, I dont think the market has even begun to fairly reprice the manganese opportunity.
$TMC Presents Its Latest Processing Results to the Metallurgy Industry:
This week TMC’s Matt Boulby and Kingston Process Metallurgy’s James McNeice presented the results of TMC’s manganese processing work at COM 2026 in Calgary.
The work successfully converted nodule derived manganese silicate into high purity, battery grade manganese sulfate.
Summarized Recap:
1) Manganese was already a product for TMC, not a waste stream.
When TMC processes nodules, the first major processing stage separates them into:
A high grade nickel copper cobalt alloy/matte
AND
A manganese silicate product containing roughly 40% manganese.
That manganese silicate can already be used as feedstock to produce silicomanganese alloy for steelmaking.
Now TMC has demonstrated another potential route:
Take that same nodule derived manganese silicate and convert it into high purity manganese sulfate for batteries.
So the manganese doesnt have just one potential end market anymore.
Steelmaking through manganese silicate/silicomanganese.
OR
Battery materials through high purity manganese sulfate.
Thats product optionality.
2) The upstream manganese processing has already been demonstrated at much larger scale.
During PAMCO’s 2,000 tonne nodule processing campaign in Japan, PAMCO successfully smelted 450 tonnes of calcine into:
35 tonnes of NiCuCo alloy
AND
320 tonnes of manganese silicate.
So producing the manganese silicate itself isnt just a small laboratory concept.
The important distinction is that converting that manganese silicate into high purity manganese sulfate has so far been demonstrated at bench scale.
Commercial scale up still has to be proven.
3) This builds on TMC’s previous work showing that nodules can be converted into multiple high value products.
TMC has already demonstrated routes to produce:
NiCuCo alloy/matte
Battery grade nickel sulfate
Battery grade cobalt sulfate
Copper cathode
Manganese silicate for steelmaking
And now high purity manganese sulfate for batteries.
TMC previously reported >99% extraction of nickel, cobalt and copper from nodule derived matte during its hydrometallurgical testing.
Adding manganese sulfate means TMC has now demonstrated a pathway to produce nickel, cobalt AND manganese in sulfate form.
Those are the key metal feedstocks used in NMC type precursor cathode active materials.
4) The US manganese angle is probably the most important part.
According to the USGS:
The United States was 100% net import reliant for manganese content in 2025.
The US has not produced manganese ore containing 20%+ manganese domestically since 1970.
Manganese is also officially on the US Critical Minerals List.
So while nickel, cobalt and copper usually get most of the attention around TMC, manganese could become strategically very important.
5) And manganese is by FAR the largest contained metal in TMC’s current USA-A + USA-B resource estimate.
TMC’s latest filing estimates those mineral resources contain approximately:
345M tonnes manganese
15.5M tonnes nickel
12.8M tonnes copper
2.0M tonnes cobalt
Important distinction: those are estimated contained metals within measured, indicated and inferred mineral resources, not 345M tonnes of manganese reserves.
But it shows the scale of the manganese opportunity.
6) This could also matter for Brownsville.
TMC and Mariana Minerals are currently working toward a potential integrated US nodule processing and refining industry park in Brownsville, Texas.
A processing system that can potentially take the same nodule feedstock and produce multiple different product formats gives TMC more flexibility around what ultimately gets produced in the US.
Steel products.
Battery materials.
Nickel/cobalt/copper products.
Potentially manganese sulfate.
The exact commercial configuration hasnt been finalized and TMC has not yet demonstrated commercial scale manganese sulfate production.
But every additional product pathway potentially increases what can be extracted from the same nodule resource.
7) The bigger story is that TMC continues demonstrating that polymetallic nodules are not a single product ore.
One nodule contains nickel, copper, cobalt and a very large amount of manganese.
And TMC is building processing routes that can potentially turn those metals into different products depending on what industry needs them.
Manganese for steel.
Manganese for batteries.
Nickel and cobalt for batteries/industry.
Copper for electrification and infrastructure.
All from the same nodule feedstock.
And in manganese specifically, this comes at a time when the US remains 100% net import reliant.
TLDR: $TMC has demonstrated that the manganese silicate produced from its nodules doesnt have to be limited to steelmaking. It can also be converted into high purity, battery grade manganese sulfate.
That potentially gives TMC two major markets for the manganese stream from the same resource: steel AND batteries.
With ~345M tonnes of estimated contained manganese across TMC’s current USA-A/USA-B mineral resources, and the US currently 100% net import reliant for manganese content, I dont think the market has even begun to fairly reprice the manganese opportunity.
This week, $TMC's Matt Boulby and Kingston Process Metallurgy's James McNeice presented to a full house at the 64th Conference of Metallurgy and Materials in Calgary on our successful production of high-purity manganese sulfate from nodule-derived manganese silicate produced during pilot trials. The findings further demonstrate our capability to convert seafloor nodules into a wide variety of metal products and formats, including high-grade NiCuCo alloy, battery-grade sulfates, and a manganese silicate used in the production of silico-manganese alloy for steelmaking. #COM2026 #deepseamining

$TMC USA-A Permitting Update:
TLDR: Another major US permitting milestone is now complete. NOAA has formally published TMC’s fully compliant USA-A application, starting the public comment period that management says is a prerequisite to certification. The application covers ~65,000 km² containing 619Mt of estimated nodules + ~200Mt potential upside, while the separate USA-B area contains another ~1.02Bt. Comments close Oct. 19, USA-A then moves toward certification/environmental review, and USA-B is already in the EIS process.
NOAA has officially published TMC USA’s consolidated USA-A application in the Federal Register.
This is TMC’s main application for both an exploration license AND commercial recovery permit under the US Deep Seabed Hard Mineral Resources Act.
Importantly, NOAA states that the application is fully compliant with the applicable information requirements. (Federal Register)
This isnt the final permit yet, but it moves USA-A into the next formal stage of the US permitting process.
The public comment clock has now officially started.
Comments are open until October 19, 2026, and NOAA will hold a virtual public hearing on October 13. (Federal Register)
Gerard Barron:
“Publication of our consolidated application in the Federal Register is an important milestone on the permitting path under DSHMRA as it starts the clock on the public comment period that NOAA views as a prerequisite to certification.”
Thats the important part here.
The public comment period isnt just another administrative announcement. Management says NOAA views completion of this process as a prerequisite to certification of the application.
The scale of USA-A is much larger than the original proposed commercial recovery area.
The consolidated application expands the proposed commercial recovery area from roughly 25,000 km² to 65,000 km².
That area contains an estimated:
619 million tonnes of wet polymetallic nodules
Plus potential exploration upside of another:
~200 million tonnes.
So we are potentially talking about ~819Mt of nodules within USA-A alone if that additional exploration upside is ultimately established.
And remember, USA-B is separate.
USA-B covers another ~122,000 km² and contains an estimated 1.02 billion tonnes of nodules.
The sequence from here is becoming clearer.
USA-A has already received NOAA’s full compliance determination.
Now:
Federal Register publication/public comment → Certification → Environmental review/draft EIS → Final NOAA determination on the exploration license + commercial recovery permit and associated terms.
Management said on the Q2 call that certification was expected around October 2026 after the administrative delay.
The comment period now ends October 19.
So the timeline is lining up closely with what management just told us.
This also matters because USA-A is the first consolidated application of its kind under NOAA’s updated framework.
Instead of completing exploration licensing and then beginning a separate commercial recovery permitting process, TMC is pursuing both through the consolidated pathway.
NOAA changed its regulations specifically to allow applicants with sufficient exploration data and expertise to pursue this more efficient process.
TMC has spent more than a decade building the environmental, engineering and resource dataset supporting this application.
Thats where the years of work start to matter.
And USA-A isnt moving in isolation.
Just two days ago NOAA also published its Notice of Intent to prepare an Environmental Impact Statement for TMC’s USA-B exploration application.
USA-B was already certified in May and is now moving through formal environmental review. (Stock Titan)
So both US applications are now moving simultaneously:
USA-A: consolidated exploration + commercial recovery pathway.
USA-B: exploration pathway with EIS preparation underway.
NOAA Publishes TMC USA’s Consolidated Application for an Exploration License and Commercial Recovery Permit for TMC USA-A in the Federal Register.
Read the press release: investors.metals.co/news-rel… $TMC #deepseamining

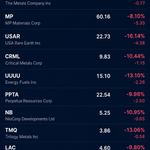
This is partly why the critical minerals sector got hit today, especially $TMC.
Xi flying in for a one day White House meeting with Trump on the 24th (first state visit in 11 years). Agenda covers trade, Taiwan, AI, and the Iran/Hormuz situation.
Market was treating that as potential deal talk, so the short term push for mineral independence could getting dialed back a bit??(which I don’t believe will happen)
On top of the high beta sector already selling off from the war escalation.
Even if a critical minerals deal does come through, the national security need for these metals does not change. The United States still requires secure, independent supply of nickel, cobalt, copper and manganese. That strategic requirement does not disappear with a handshake.

Chinese President Xi Jinping will fly into the US on September 23, hold one day of White House meetings with Trump on September 24, and leave September 25.
Xi will skip the UN General Assembly entirely.
It will be his first US state visit in 11 years.
The agenda is expected to cover trade, Taiwan, AI, and the Iran/Hormuz situation.
Source: Politico

Quant retweeted

Link below to @RKEquityRocks summary of @themetalsco earnings call yesterday.
Commentary this morning from two sell-side analysts:
Alliance Global Partners
“We are reiterating our Buy rating and $12.25 price target. Our valuation remains based on a NAV analysis of the company's NORI-D license area utilizing a 12%
discount rate and 0.6x NAV multiple. Given the increasing urgency related to onshoring the domestic critical materials supply chain in the U.S. as evidenced by the aforementioned expedited permitting process, we believe our mid-2028 production
estimate remains achievable.”
HC Wainwright
“We reiterate our Buy rating on TMC and our PT of $11.75. Our valuation for TMC remains driven by a DCF valuation for the firm. We continue to utilize a 12.0% discount rate on the company that we believe fairly accounts for governmental support and TMC's permitting pathway. We also maintain our valuation for the remaining NORI area and TOML blocks in a DCF based on the IA, while still assuming a start date of 2037. We ultimately value the NORI-D Project at $3.42B, before adding $1.37B for the rest of the resource area. We also incorporate TMC's most recent cash balance of $98.7M into our model. The firm still has no debt. We then apply an unchanged 1.25x NAV multiple that yields a total value of $6.10B, or $11.79 per share, which rounds to our PT of $11.75 per share.”
$TMC
Not advice. DYOR
👇

$TMC Q2 was more constructive than the headline numbers suggest.
USA-A certification is now expected in October, pushing a Q1’27 permit off the table. But importantly, management still sees no impact to the Q4’27 commissioning schedule. At this stage, the distinction between a permitting delay and a project delay matters.
Offshore execution also continues to advance. Allseas has completed basic engineering on key long-lead systems, procurement is beginning and fabrication is expected to start in Q4.
The capital structure is increasingly worth watching. Underlying Q2 operating cash burn was about $11m excluding a timing item, much of the current Allseas liability is deferred until production, and Allseas is expected to fund a significant portion of pre-production development.
Onshore, Brownsville is being developed with much greater scale in mind, while near-term feasibility spending remains measured and tied to the work required to unlock potential U.S. government support.
There are still important milestones ahead, particularly permitting and government funding.
But the story is becoming less about whether @themetalsco can assemble the pieces, and more about how efficiently those pieces can be brought into production.

Quant retweeted

.@gtbgtb, Chairman and CEO of @themetalsco, says deep sea mining could reduce U.S. reliance on foreign critical minerals as policy support accelerates and demand for domestic supply grows.
$TMC
cnbc.com/video/2026/08/14/th…

$TMC Q2 Call Updates:
1) TMC is actively in confidential funding processes with multiple US government agencies named in Trump’s executive order.
While those discussions remain confidential, management said it does not currently intend to pursue other capital market transactions until further public updates.
CEO Gerard Barron:
“The company does not currently intend to pursue other capital market transactions until such time as further updates are publicly released.”
What that means: no equity offering, follow on, ATM, convertible, or equivalent capital markets raise is currently planned before we hear more on the government funding process.
2) Allseas is moving the first commercial collection system into procurement now, with fabrication expected to begin in Q4 2026.
Installation and commissioning still targeting Q4 2027. Initial capacity 3Mtpa.
3 million wet tonnes of nodules per year. Thats the starting point with two collectors on the Hidden Gem. If processed in the US, that single system alone could cover roughly a quarter to a third of current American nickel and cobalt demand.
Allseas is funding a meaningful portion of the preproduction costs, recoverable from production revenues. Alignment is strong.
Allseas exclusivity remains an important part of the setup. Gerard confirmed the offshore mining arrangement is exclusive.
Allseas could only offer another system elsewhere if it first offered that system to TMC and TMC declined.
Gerard said the likelihood of that happening is very low because TMC wants multiple systems in the water.
3) Mariana Minerals is becoming a major execution partner. Theyre helping advance permitting, construction, processing, automation and plant design at Nodule City, Brownsville.
The Prefeasibility for a potential 12 Mtpa industry park is nearing completion. Modest spend underway for the work that unlocks potential government support.
Feasibility level work on the first smelting stage is underway with Mariana Minerals (the software/automation heavy processing partner that just raised $310M).
TMC has an exclusive right of negotiation over the Brownsville site. The area being evaluated is 1,466 acres, and No final investment decision has been made, and any future capital commitment remains contingent on US government support.
4) Management is looking out for shareholders and doing what it can to avoid unnecessary dilution.
TMC decided not to extend the September 2026 SPAC warrants. The 15M public warrants have an $11.50 strike, but extending them would also require extending 9.5M private warrants that can be exercised cashlessly.
CFO Craig Shesky also noted that extending them would require extending the private warrants, which are:
“unlikely to result in any incremental cash proceeds to the company while still diluting existing shareholders.”
So management chose to let the warrants expire rather than accept dilution that may bring little additional cash.
The read through is pretty clear: management appears confident enough in the upcoming catalysts to wait rather than raise/dilute around today’s valuation.
If they believed $11.50 was as good as it gets, taking the cash would have been the easier decision.
Why accept unnecessary dilution around an $11.50 strike when management says the stock is undervalued and expects major catalysts ahead and believes the equity should be valued materially higher?
5) New mutual services agreement with Eco Minerals, another US company pursuing its own NOAA application.
Eco can provide TMC vessels, AUVs, marine survey capacity and offshore services at preferential pricing. TMC provides ~15 years of resource definition, environmental and permitting expertise.
A joint offshore campaign is possible later this year to gather more data and potentially move additional USA-A tonnage toward reserves.
6) Permitting continues moving under the US pathway.
USA-A Federal Register publication/public comment is imminent. Certification is now expected in October 2026 due to an administrative delay, not an issue with the application.
A Q1 2027 permit is no longer expected, but management still expects it well ahead of the Q4 2027 vessel commissioning target.
USA-B, covering ~122,000 km², is also moving into formal EIS review.
7) Resource economics remain unchanged.
$5.5B PFS NPV + $18.1B initial assessment = $23.6B combined stated NPV.
Across both projects, the studies point to roughly $369B in undiscounted revenue and >$200B in EBITDA.
Management directly acknowledged the stock has lagged the operational progress and resource value.
Craig Shesky:
“Our market cap is undervalued relative to the resource itself by any reasonable peer based metric.”
8) TMC’s scientific/environmental dataset continues to be a major part of the moat.
NORI has completed:
22 offshore research campaigns
959 research days at sea
More than 1 petabyte of data
41 peer-reviewed papers
That work supports permitting, environmental review and TMC’s ability to move resource categories toward reserves.
9) US government support for the broader critical minerals strategy remains strong.
Gerard attended the Aug. 7 State Department critical minerals roundtable alongside senior Trump administration officials.
Trump again reiterated support for deep seabed mining.
Important distinction: no direct nodule collection funding was announced at that event. TMC’s own government funding processes remain separate and confidential.
10) TMC is building beyond just one vessel and one processing plant.
Management is working across US shipbuilding, marine logistics, autonomous vessels, environmental monitoring, processing, refining and rare earth development.
The goal is an integrated American deep seabed critical mineral supply chain from collection all the way through delivery of finished metal products.
11) TMC is keeping PAMCO Japan as a processing fallback while Brownsville advances.
Management said they’re maintaining the partnership with PAMCO specifically to preserve processing optionality, so the US build is the preferred path without leaving TMC dependent on a single route.
So TMC keeps an existing processing route available while working toward domestic US processing.
12) Offshore logistics are also being optimized.
A typical shipment would carry ~60,000 tonnes of nodules from the CCZ to Brownsville.
The Panama Canal is the base case, but TMC is also studying a Cape Horn route as autonomous vessels become more practical.
They’re also integrating USV/AUV technology for logistics, environmental monitoring, situational awareness and continued resource definition.
13) Failed attempt against the U.S. pathway: China, Russia and Greenpeace supported an effort seeking an ITLOS advisory opinion targeting seabed mining outside the UNCLOS/ISA framework.
“The effort failed and received significant pushback from member states across Europe, Asia and the Pacific.”
14) TMC also got a favorable outcome on the ISA side.
The ITLOS Seabed Disputes Chamber unanimously prescribed provisional measures protecting NORI and TOML rights to due process and fair treatment in their disputes with the ISA.
Days later, the ISA Council approved a 5 year extension of NORI’s exploration contract by consensus.
15) Liquidity remains solid.
TMC ended Q2 with $143M of liquidity, including $44M of undrawn credit capacity.
Management expects cash on hand to cover working capital and capex commitments for at least the next 12 months.
A large portion of the Allseas liabilities are also deferred until production.
TLDR(Q2 was about exectution) Government funding talks are active, and management currently doesnt plan on doing any offerings at all. Allseas is moving into procurement while funding a meaningful portion of preproduction costs, with the first 3Mtpa system alone potentially covering 25-33% of current US nickel/cobalt demand. Brownsville is advancing, Q4 2027 commissioning remains intact, liquidity is solid, management is protecting shareholders from unnecessary dilution, and the stated $23.6B NPV remains unchanged.


I can’t stress this enough.
$TMC is the fastest path to actual mineral sovereignty the United States has right now.
While every traditional mine is still stuck in a 20-30 year permitting nightmare, TMC already has the only SEC compliant deep sea reserve ever filed, NOAA full compliance locked, Allseas production system signed, and the commercial recovery permit decision still tracking for Q1 2027.
Four critical metals in one rock. No digging. No blasting. Just vacuum the nodules and process them.
Capital, policy, and the processing partner (Mariana) are all lining up at the exact same time. This is the purest speed play in the entire critical minerals space.
(Not investment advice. High risk, high reward. Do your own work.)

$TMC CEO Gerard Barron was in the room Friday at the State Department critical minerals roundtable, where President Trump declared America a minerals superpower.
The administration rolled out ~$3B in new mining commitments and fresh workforce funding for mining engineers.
He also sat down with Turner Caldwell of Mariana Minerals, TMC’s processing partner, fresh off a $310M Series B.
Capital is flowing to the exact layer $TMC needs.

President Trump's Administration is serious about mining, and I'm pleased to say it includes recovering nodules from the deep seabed.
Friday's gathering was further proof and it was great to see the administration’s commitment of $$$ to encourage more mining engineers to come through USA's best universities.
I also caught up with Turner, who had just announced a successful $310M Series-B raise at Mariana Minerals. They’ve assembled an impressive team that does not shy away from the toughest challenges in mineral mining & processing. Given the velocity of their progress, the future belongs to them and the future is metal! Congrats to the whole @MarianaMinerals team. Proud to count you as our strategic partner.
