

Equity Analyst + Macro Trader, hobby economist & humble market student.
Either SF or NY
Joined August 2014
- Tweets23.8K
- Following1.1K
- Followers15.3K
- Likes12.4K




I’ve said this before and I will say it again.
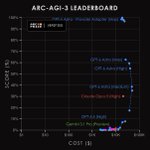
A token is analogous to a semiconductor transistor. Cost per a transistor (token) has been in free fall for decades yet revenue for the semiconductor industry has outgrown GDP relentlessly. People just consume proportionately more compute as it becomes cheaper. AI economics are no different. Token costs fall and token usage goes up by >1x. $ANT $SMH

Revenue per GPU can increase as token prices decline if per GPU token throughput increases enough.
So both Anthropic revenue *and* margins can go up as token prices go down *if* GPU prices go up less than the product of (token price decline * per GPU throughput increase).
But I have super enjoyed all the commentary to the contrary!
Greg retweeted
I am shocked, absolutely shocked, that Anthropic ARR has likely gone vertical in October after they cut token prices.
Except the exact same thing happened for the entire AI market, which is why GPU rental prices have surged while token prices declined.
$100b plus in year-end ARR looks possible again.


Until spreads settle a bit equities and might be stuck in the mud.
CCC-BBB spreads are nearing oh shit levels.


Greg retweeted
This might be the most important chart in Semis over the next 5-7 years. If. Wafer throughput is increased 40% then we could see capital intensity become much more moderate than expectations over the next decade. Additionally, $ASML is working on a more intense light source which could improve this further as multiple passes are lessened or no longer required. $TSM $NVDA $SMH

I don’t agree with this. Rental $/GPU hr are independent of the cost of equipment and financing of that equipment. Higher cost of capital just moves break evens and IRR.
But I will state the view the commodity like companies in the AI value chain are not the Frontier labs as many have suggested, but the neoclouds providing raw compute. It’s why their bonds are priced like shale oil companies circa 2013-2019 at 9-25% yields. $NCLD $SMH

I've been critical in the past of AI compute indexes and the willingness to price compute based on the spot rental price, but now that the AI reset is sinking into the repricing of AI buildout debt its time to realize that the cost of capital is what determines the price of compute.
The most important number in GPU pricing right now isn't $/GPU-hour. It's the gap between what a hyperscaler pays to borrow (~90bp over Treasuries) and what a neocloud pays (~1,100bp).
The cost of compute is now set by the cost of capital, and the spot rental rate no longer tells you much.
The price of an H100 isn't one number. The same chip in the same rack costs a different amount depending on whose balance sheet it sits on. A ~1,000bp funding gap is a structural cost advantage that no amount of operating skill closes.
For example, take one GPU-hour apart. Most of it isn't power or space. It's paying back the chip, the interest on the loan that bought it, and the return the equity expects. A $40–55k all-in GPU, 75% debt-funded, at ~7,000 utilized hours a year is a financing instrument that happens to do matrix multiplication.
As the +500bp on neocloud debt (10%→15%) adds $0.20–0.30 to the break-even cost of every GPU-hour, which is then added on to the rental price.
That's 8–10% of the H100 index, from a credit spread alone, driven almost entirely by the cost of capital.
That means that the compute spot index is a derivative of the AI infra debt credit curve and the squeeze on neocloud margins.
This might be the most important chart in Semis over the next 5-7 years. If. Wafer throughput is increased 40% then we could see capital intensity become much more moderate than expectations over the next decade. Additionally, $ASML is working on a more intense light source which could improve this further as multiple passes are lessened or no longer required. $TSM $NVDA $SMH


Narratives vs reality
It’s a “miss” vs fastest company to ramp revenue to $100B in history
"Anthropic Q3 revenue was a big miss - $16.8bn for the quarter vs $5.4bn implied monthly run-rate for July (which was reported in Aug), implying close to 0 growth in August and September. This has weighed heavily on sentiment, as a key pillar of the AI investment thesis is the ARR growth trajectory of frontier models. The funding stress facing Coreweave and the neocloud ecosystem are further exacerbating concerns." - Goldman Asia S&T
A bubble that entails zero euphoria
The OpenAI "Tell": BofA Says The AI Bubble Will Burst With Stocks AND Yields Tumbling... Here Is The Cheapest Hedge zerohedge.com/markets/openai…

Greg retweeted
This is the diffusion of CPI inflation, measured similarly to Kevin Warsh's preferred PCE inflation diffusion metric.
It's down.
our full reaction @TheTerminal blinks.bloomberg.com/news/st…


When 1 customer and a dumb policy choice of token maxing gets reversed, ARR growth decelerates substantially. $META

The bear argument that hyperscaler ROIC is below cost of capital on DCs have some explaining to do. $AMZN
AWS HIKES GPU PRICES AGAIN AS AI DEMAND STAYS STRONG
AWS will raise reserved GPU compute prices by 15% on October 7, following a 20% increase in July, according to Wells Fargo.
It marks the fourth consecutive quarterly increase, with H100/H200 and B200/B300 pricing now up 40–75% YTD.
Wells Fargo sees the pricing power supporting AWS revenue acceleration into early 2027 and maintains Overweight on Amazon ($AMZN ) with a $338 target.

