

Diary for speculative market analysis and frequent political musings. L/S enjoyer
Joined January 2021
- Tweets11.1K
- Following157
- Followers1.7K
- Likes13.4K





Pinned Tweet
The name of a killed service member covered up by a Dow Jones index ticker is a pretty grim metaphor for how America often operates.

Frothy Assets retweeted

Hedge Fund Manager David Orr (@orrdavid) on why he’ll back a delivery guy over a Harvard grad, as long as the track record is real.
David Orr runs Militia Capital, a ~$480M hedge fund. ~50% annualized, Sharpe 2.
“If you didn’t go to Harvard, they’re not going to give you money. They’re gonna lead you on for years.”
We cover:
- Edge is just reps. He's placed a few hundred independent bets every year since 2019, more in one year than a lot of hedge fund managers get in a decade.
- The two-hour rule: if he can't decide on a stock in an hour or two, he skips it. When a trade goes against him, he quits. "The market said I'm wrong, I'm wrong."
- 500 positions in his partition and zero notes. Some of his best shorts are down 40% and he's forgotten what the company does.
- The Gogo lesson: he spent 100 hours on a short and was right on the fundamentals (it's now $2), but it ripped to $20 first. All that research made him stubborn on the way up.
- The AI risk system: it groups the book into custom baskets like "Banks Done Right" and "yield traps," recalculated daily. A 25% bet can quietly become 45% in two weeks.
- How Militia recruits PMs: 95% of track records are junk, and one cherry-picker ran 30 accounts and sent the best one. The PMs who make it include a game show winner, a Spanish government worker and a programmer, with 0.15 cross-correlation.
- The best short seller in the world, quietly: 40% a year short only for years, and he still gets a tiny allocation at his fund.
- Why multi-managers' real business is marketing. Collect $2B a year in fees on $100B and it's "mission accomplished," whatever the returns.
- The long/short tax trick: harvest losses on losing shorts, and never cover one that's down 90%. No tax is due until it's delisted, which can take 10 years.
- $150M raised from one email asking LPs for $100M. He says he could raise a billion but won't, and admits they "must have gotten at least somewhat lucky."
- His AI stock map: hyperscalers locked customers into take-or-pay deals at ~35% return on capital. If compute prices crash 80%, the end customers get wiped out, not the hyperscalers.
- Is investing 99% talent? For big alpha, almost entirely. Pod shop alpha is teachable, maybe for 1 in 50 people rather than 1 in 10,000.
Highlights:
00:00 Intro
00:44 How AI custom factor baskets track dynamic correlation in levered portfolios
03:24 Sourcing non-consensus PM talent and verifying live Sharpe track records
07:24 Structuring carry and tax deferral to attract elite proprietary traders
12:50 Why institutional multi-manager platforms fail to back pure alpha
20:22 The two-hour research limit: Avoiding sunk-cost bias in short selling
27:58 Momentum screening vs deep value: Why top longs hit new highs
29:40 Why traditional finance books fail and what operator biographies teach
37:16 Why rapid technological adaptation beats traditional economic moats
39:26 Analyzing the AI trade: Why hyperscalers offer superior downside protection
44:57 Internalizing stock borrow desks to maximize net-of-fee fund compounding
55:25 Avoiding confirmation bias and why shorting revenue growth fails
01:01:42 Pod shop leverage factories vs raw discretionary alpha generation
01:07:12 Unplugging from market narrative feeds to preserve independent conviction


Frothy Assets retweeted

The S&P500 fell 1.2% yesterday despite more than 300 of it's constituents moving higher. This makes yesterday the 2nd widest divergence since 1990 when Bloomberg began collecting the data
Only time yesterday's dispersion was topped was in January of 2025 when DeepSeek happened per Bloomberg

Frothy Assets retweeted

Meta spending a cool 2.5% of GDP on off-balance sheet AI infrastructure.
roughly double the European Union’s total defense spending

Eventually there won’t be much left for L/S degrossing, plenty now.
Positioning + flows matter short term, but long term many AI losers can do poorly even while semis struggle.
I asked ChatGPT to give me some consensus AI losers, they are squeezy today:


Semis have moved inversely to AI-losers given that we had 3-4 straight months of putting the “easy” trade on, and now 3-4 months of degrossing.
We are slowing moving to an environment of less semis ownership and less AI-losers short exposure and I’d expect the inverse relationship to slowly weaken.
These things probably got crowded in part by analysts asking LLMs what companies are AI-losers and everyone put on the same 50 shorts.


I don’t even think that, say the Russell 2000 or homebuilders or biotech (or anything that isn’t fully interest rate-related) does well long term in an AI-unwind bear market.
It just seems inevitable that there will be a rotation first before people go “oh, most of our economy was AI and this is bad for everything (besides bonds).”
Perhaps tech finishes bigly green tomorrow + Friday and these views are a waste, but not my guess.
More rotation/degrossing today. Does not feel like we are close yet, but what would be very bearish equities + bullish vol is full risk off, when these are also down when tech is down big. That would tell me that most rotation + degrossing is completed and the next bearish shift move would be to sell equities indiscriminately to buy bonds. Plenty more rotation/repositioning left imo, you can’t undo three years in three weeks…


1) USA blows Iran to smithereens
2) Iran agrees to very favorable deal while they have the most leverage (now before the midterms)
3) old fashioned demand destruction

actually scratch that, Trump probably cares more about his precious stocks than some lousy elections. Iran may even have more negotiating leverage at a time with SPX in >10% drawdown…
This is Trump personally tbf, there are certainly (more politically concerned) decision makers influencing his actions.
Number 2 seems most unlikely. Because Iran does not fear number 1 and because they love war and feel religiously compelled to always keep going. They’ll miss their strongest negotiating window and they’ll get blown to kingdom cum.
Imagine if $GS does a 5/1 stock split and now its weighting in the Dow Jones is 80% lower. Hilarious index.
The ever-quoted price-weighted politically important index. $DIA is only around 45 billion AUM, so not that relevant.
Hypothetically, if $GS expects to badly miss earnings, they should do an emergency 20/1 stock split before their earnings report (for national security reasons heh).
Surprisingly doing well with equities at ATHs despite very negative beta. Bonds started puking late June, so it’s been a very easy period since then. These tailwinds have been notable and even larger than I thought, so I have been adjusting lately given (likely) risk of a bond rally. My vol is high, lowering via adding bullish equity exposure and pushing gross exposure higher.


Last week the cards perfectly hit my hand, partly factor related. If I was very responsible I’d (ignore directional views) increase tech exposure. I have no hesitancy adding bullish rate-sensitive equity exposure.


Short form video content dominating. Apparent in Meta + Netflix results. Not just attention spans, a two hour movie is a big commitment, people can’t commit to anything these days.
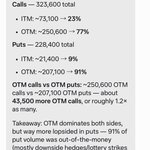
I remain underweight tech but do like Meta and Amazon especially. Muse only somewhat helpful for travel. I’ve used it some and will use more scrubbing Barchart options volume to find out % of daily options volume OTM vs ITM for calls + puts. Only seems relevant for ERs/events or outside RTHs gapping moves.
And not even sure how relevant delta-hedging related views are, hard to ever really know their impact. But based on this the below name should bleed lower from tomorrow’s opening bell to the close:


Frothy Assets retweeted

I want to be clear: the rioters have no legitimate demands. French social spending is too high, not too low. This is mostly ethnic warfare and just plain low-IQ low impulse control violence from third-world savages incompatible with Western civilization.

We can’t just have a 35% drawdown in QQQ without it hurting everyone. Much of the economy is tied to asset prices via wealth effect and businesses more directly. A collapse of the AI trade/equities would have ripple effects. It would at least solve the inflation problem though.
A better argument than the OP imo, perhaps this is what’s meant: ‘if the AI-related capital allocation is bad/bubble, it is probably better to pop before it gets any bigger.’
I will note that positioning for an AI slowdown and acknowledging the consequences of said slowdown are two different things.
I want to clarify that I’m not rooting for AI-backstops or anything, only acknowledging that an unwind would be painful for the country economically.
If these AI capex bets are wrong, those players should be allowed to fail.
Frothy Assets retweeted

In France, benefits are "free." They're free the way dinner is free when someone else pays the bill. For forty years that someone has been the next generation, and the bond market has been the go-between. France already taxes more than any other G10 economy, and it borrows to fund the welfare state. Now the rent is coming due:

Frothy Assets retweeted
I thought MMT meant inflation was the constraint. But then we got partly fiscal-induced inflation and their proposed solution was student loan debt relief and price controls. So I’m left confused about what they mean by anything.


