

Dubai, UAE
Joined August 2020
- Tweets6.8K
- Following1.3K
- Followers11.1K
- Likes24.7K




Pinned Tweet
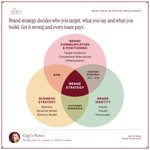
Most early-stage teams spend their first marketing budget before they've answered the one question that decides if any of it works: who is this actually for.
AI is only accelerating the commoditization. My advice:
1) Start with a decent brand strategy, slow down to accelerate later. This is HEAVILY misunderstood by so many early-stage teams and where I do a lot of heavy lifting;
2) A real brand strategy is what lets you focus and focus is non-negotiable now that the internet has balkanized into endless niche islands, each running its own language, what cyber-ethnographer @being_on_line calls Babelification. Pick your ICP. Go all in there.
3) Then be bold and build brand equity offline. A recent chat with the talented @chebibtarik who scaled massively across the globe in just the last few years, confirmed it.

Gigi retweeted
Consumption layer is up for grabs again. This happened somewhat with mobile. And more significantly with the Internet.
It happens rarely, every couple of decades. But when it does it can be very very disruptive.

Momentum in Egypt's market across the entire capital stack!
1) The state: Egypt's Minister of Planning & Economy Ahmed Rostom unveiled a joint investment fund with NI Capital. Target: back 5,000 startups and mobilise $5B in venture capital, with a $1B unified financing initiative over five years.
2) Private funds: @TanmeyaCapital closed its second growth fund at $130M with about $38M from @EIB. And DPI Venture Capital's Nclude Capital closed above $112M, backed by @BanqueMisr, National Bank of Egypt and Banque du Caire, for fintech across Africa and the Middle East. Egypt's three largest state-linked banks on the same specialist VC vehicle.
3) Public markets: Banque du Caire just saw Egypt's highest-ever demand for a private IPO tranche. @EBRD and @IFC_org each committed roughly $100M as anchors. Egypt's biggest IPO in over a decade. Trading starts November 2 under BQDC.

WHERE WILL THE NEXT GENERATION OF GULF CAPITAL GO?
About $1 trillion is set to pass to the next generation of Gulf families by 2030. @lombardodier's 2025 GCC survey showed 79% of next-gen respondents said they’re likely to change the advisor their parents used.
That’s stated intent, not behaviour yet. But new signatures mean a new underwriter looking for new gaps in the market.
I look at it through three lenses:
1) Who decides: a generation with different advisors and its own priorities.
2) What they want: venture, tech and impact alongside market returns.
3) What’s still unfunded: categories with proven global need and little regional capital.
One of my bets is women’s health.
Globally, women spend 25% more of their lives in poor health than men. The World Economic Forum and McKinsey Health Institute estimate that closing that gap could add at least $1 trillion a year to global GDP by 2040, and that every dollar invested could add about $3 to the economy.
Capital has started to follow. Women’s health companies raised a record $1.55B in equity in 2025, up 41% on the year before (W Group).
In the GCC, @Tracxn counts about $9.7M raised by femtech startups in total. Even against a single year of global funding, that’s under 1%.
I spent a couple of years dealing with health problems myself, and felt first-hand how little of the system is built around women. That’s why I’m glad capital is starting to move here.
So the better question is: which gaps look like their priorities, not their parents.
Gigi retweeted

Sequoia just made a bold claim:
They think the next $1T company will NOT be a software company.
Their take?
Services will be the new software.
Because SaaS companies have spent 25 years fighting over a smaller budget in comparison.
For every $1 companies spend on software → they spend about $6 on services.
For reference:
• A company might pay $10K a year for QuickBooks.
• And $120K for the accountant who closes the books.
AI has completely changed that.
Now, a company can sell the finished WORK instead of the tool.
Here's how the 3 models compare:
TRADITIONAL SAAS
• The customer buys access to software, and their own team runs it.
• Growth is capped by product + distribution.
TRADITIONAL SERVICES
• The customer buys people's time + expertise
• Growth is capped by hiring.
SERVICE-AS-A-SOFTWARE
• The customer buys a completed piece of work.
• Software handles most of the delivery, with the provider's team on decisions + exceptions.
• Growth is capped by how much of the work software can do reliably.
Something to keep an eye on.
Gigi retweeted
I regret to inform you that a lot of problems in life are solved by waking up early and working out.
I am chronically online these days, and it becomes harder and harder to take a full rest. Anyone relate?
a16z data: more than 1 in 3 Americans bought something based on an AI recommendation in the past year, and 34% would pay more if AI showed it was the best option.
If AI assistants become the new storefront, does brand still matter, or only being the answer the assistant picks?
I think it depends on the category. When you know exactly what you want, the assistant wins. When you want to discover, browse vintage or fall for a brand, people will still scroll and explore.
As @mlevchin put it on @tbpn , a lot of shopping is a form of entertainment. Nobody wants an agent to do the fun part for them.
So brand experience matters, maybe even more nowadays to ensure you fall into the bucket of entertainment.
Gigi retweeted

This is how banks are planning to stop those "agentic bank runs." Watch closely: their business model depends on seeding this narrative that AI agents are dangerous.
Remember, an "agentic bank run" (coined by Apollo) means agents helping customers move their own money en masse to higher-yielding products.
Once agents are ubiquitous, there are only a few ways for banks to hold onto cheap retail deposits.
Option A: Raise APYs (lol no)
Option B: Reduce leverage via fewer loans (no fun)
Option C: Ban AI agents, claiming they are a security risk (ding ding ding)
Cloud agents like Muse and Dot are trivial to stop, since they come from Meta / OAI IP ranges. If JPM sends them a cease and desist, they will comply.
Why would JPM bother? Because their business model depends on it; a huge portion of their ROE comes from cheap retail deposits. This is not theoretical. Just like Amazon banned Muse from shopping there to protect their ad revenue, JPM and Schwab have already banned AI agents to protect sticky deposits.
Are agents perfectly reliable today? Of course not. But look at the fix they chose. Not "here's a safe API for agents," it's "no agents ever." That tells you they're not protecting customers, they're protecting themselves.
No company ever wins a technological revolution this way. It's the last gasp of a dying business model. It's like the retailers who refused to put their inventory online and demanded users walk into the storefront. Over time they will lose market share to those platforms that embrace what's coming. Their whole deposit franchise depends on users unthinkingly clicking through walls of T&Cs and accepting 0.2% when the risk free rate is closer to 4%. Agents read the fine print and do their research, even when humans don't.
For users, the answer is simple: local AI agent frameworks like Hermes, that will actually act on your behalf and that the banks can't block. As the article says, if the agent is running on your own computer, they can't actually tell it's not you.


SCOOP: Major U.S. banks are detecting unauthorized third-party AI agents inside customer accounts, including some attempting to take actions that appear to be independent of user instructions, sources told Axios.
The findings have alarmed banking executives, who are racing to restrict access to their systems as AI moves at a velocity faster than financial institutions can respond, multiple industry and bank executives told Axios.
Several banks are now preparing for worst-case and even “day after” scenarios, including how to rapidly secure or restore customer accounts if things go wrong, the people said.
Several bank executives told Axios they're struggling to distinguish between human users and AI agents. One executive said banks also struggle to determine whether agents are authorized by customers or potentially operating without their permission, more akin to rogue agent behavior.
Read my latest for Axios here: axios.com/2026/10/22/ai-agen…

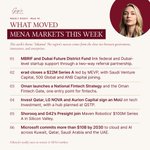
A $1B US growth fund picked Doha, a US startup got acquired by a Qatari super-app, and impact mandates and crypto adoption kept raising.
This week in MENA venture:
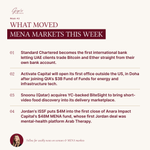
1) @StanChartUAE is the first international bank to offer @varadubai-licensed crypto trading straight from existing accounts, settled with @zodiamarkets. A 170-year-old bank launched it in the UAE before anywhere else, proving my thesis on how the Gulf is an adoption market.
2) Activate Capital a $1B+ SF growth fund backing @CrusoeAI is opening its first office outside the US, in Doha, after joining QIA's $3B fund of funds.
3) @snoonu_qa bought @TryBiteSight (YC W24), the short-video food discovery app.
4) Jordan's Innovative Startups and SMEs Fund @issfjo put $4 million into the first close of @ndakkak's Anara Impact Capital's $48 million MENA fund. Anara backs seed and Series A startups working on education, wellbeing, financial inclusion and climate resilience.

Taking rising early to the next level, going for a glute strength session at 6 am.
Maybe New York culture is landing in Dubai.
Sleepmaxxing = looxmaxxing
Sleeping 9pm-5am every day. It’s addictive. The mental clarity and the results on skin / health. Unbeatable.

Gigi retweeted

JUST IN: US OCC finalizes GENIUS Act rules for stablecoin issuers
The rules set requirements for reserve assets, redemption procedures and custody, establishing key compliance standards for permitted payment stablecoin issuers.


Gigi retweeted
I think I've gotten to the bottom of the issue with the "network effects" discourse. The problem is the shape of a moat is often conflated with the mechanism. And there is remarkably little consensus on what a network effect is, or a flywheel.
Here's a very simple, very rough vocabulary that I think works with current working definitions. Seriously, learn these few rules so your boardroom conversation about defensibility isn't a waste of time:
Shape of Moat: This is what happens to the advantage as the company scales
Static : Doesn't change
Sublinear : Advantage compounds but at a diminishing rate as the company scales (this is not a long term durable moat against challengers)
Linear: advantage is fixed relative to a competitor as company scales
Superlinear : Advantage compounds at an increasing rate as the company scale (this is the white wale everyone pretends they have, but almost no one does)
Mechanism of Moat: The property, business process that produces the advantage.
Network : more users creates more interaction between users. Hopefully superlinear.
Scale : greater volume produces better unit economics. normally sublinear
Data-driven : new users means more data for new users (or to get new users). normally sublinear
Platform : growth on one side increases value to the other. sublinear to superlinear depending on size
Distribution : scale improves reach or channel economics. normally sublinear
... etc.
Flywheels: Flywheels are also conflated with the above. The most useful working definition of a flywheel is the aggregate advantage when multiple mechanisms are self reinforcing, something in a chain (A->B->C). Imagine multiple forces pushing a flywheel to make it go faster. The hope is this complex interaction produces a superlinear advantage. They are incredibly hard to reason about. And most discussion around them are based on vibes.
Banks were built for humans. Stablecoins turn out to be built for agents.
@HadickM's point: bank transfers fail about 2% of the time. Fine for a few bills a month but for an agent making thousands of payments a day.
Some days I'm still shocked how far blockchain has come in six years, from a scammy industry to a key enabler of the agent first economy.

.@HadickM on @MTSlive re: agents + money:
“When you’re built on top of Plaid, you have a bunch of failures, failure rates at 2% or so for ACH. And there’s a lot of capital inefficiency in it as well.”
“If you ask your LLM what bank should you use that is agent friendly, they’ll tell you Mercury. They won’t tell you JPMorgan.”
“A financial institution that controls those different accounts and is able to monetize those different accounts, that is AI first and agent first, that is where you’re likely to see a lot of this happen.”
“The concern is the surplus will continue to shift from banks to fintechs.”
Gigi retweeted

Ben Horowitz on treating your story as your strategy, and why founders often skip writing it even though it's one of the most important parts of the job:
"The story of the company is also the strategy of the company... In your mind, you're kind of adjusting that strategy a little bit at a time every day. But then a quarter later, it's actually pretty different than what you started with."
"So it's really important that you keep upgrading your story. The articulation of your story. I would definitely recommend it be in written form."
"Something that you can share with everybody in the company, and everybody you're recruiting, everybody you're trying to raise money from, all your constituents, every customer."
"The problem that I think founders have is it doesn't feel like work. Like, 'What are you doing today?' 'I'm working on my story.' That doesn't sound like work."
"Because it doesn't feel like work, people don't do it, but it's probably one of the most important parts of the job."
@bhorowitz w/ @speedrun GP @Tocelot
Agentic commerce went from dead to vertical in four months.
In May Stripe shipped all the tools and usage was low. ChatGPT's buy button flopped. Now @collision says it's taking off.
My take: nobody wanted to open a new app to let a bot shop for them. @Muse and Instinct just showed up in the chats we already live in!
And now Amazon is blocking agents? I'm with Mark @finkd on this one. Open up and build sustainable moats with the models, or watch your customers shop somewhere else.
The market is starting to price aesthetics. Even X now bars ugly ads.
Last week Stripe's head of design @lil_dill gave a name to what AI produces by default: "zombie products." Monotonous, vacant, disposable.
The problem is the dopamine hit of having it done. And it reveals the many people out there without taste...
I see it all over LinkedIn, makes me cringe.
glad I have born talents for both (don't tell me to be humble, I am.)

Ben Horowitz on the two skills that will matter more than ever before in an AI world: creativity and relationships.
"I think those are things that are hard to get out of today's AI in a very good way. So if you don't have instincts around those things, I don't know if all the AI in the world could help you. Whereas the grind-them-out tasks, AI is already really good at."
"Do you have original ideas? Can you establish and maintain very high quality, high fidelity relationships with people off the rip? I think people don't think about that enough."
"One big advantage I think that we have is we really look for that. Many just ignore that whole thing, like it's not a thing... It's a thing."
@bhorowitz w/ @Tocelot