






Gavin Baker's list: $CRWV, Crusoe, $NBIS, $SPCX and the hyperscalers.
No mention of $IREN.
Here's the pit crew it's been hiring.


Gavin Baker says standing up a GPU cloud is like running a Formula One team, and CoreWeave, Crusoe, Nebius, SpaceX and the hyperscalers are the ones who can do it
“But standing up a big GPU cloud, not just bringing on the power, standing up the cluster, it’s like running a Formula One team.”
“And a bunch of people who have no real relevant experience, whatever, they acquire some land and some power and then they get a zero down payment offtake agreement from someone. And a lot of that is being cleaned up.”
“And I think, this is a forcing function to allocate GPUs to people who can actually bring on a cluster, energize the GPUs, run it well.”
“Like, running a Formula One team, it’s like really hard. You gotta like pack everything up, put it on a plane, go to a new city, unpack it, set it up, set the car up. You need all the people to change the tires, to change the rear wing if you get in a collision, to do whatever needs to be done during the race, to do the strategy, to communicate with the driver. It’s really, really hard.”
“And some of these people, they don’t have the relevant experience. CoreWeave, Crusoe, Nebius, SpaceX, the big hyperscalers, these are companies that can bring on GPUs and energize them and run them.”


My pick: $SPCX.
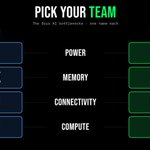
The addressable market. It covers three themes I'm most bullish on:
> Space: launch
>Connectivity: Starlink
> Compute: AI data centres
If it ever merges with $TSLA, add autonomous vehicles and the energy grid.
Timelines will slip. Elon's always do. But over 10 years, the addressable market is unmatched.
Two takeaways from Citizens on neoclouds:
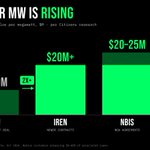
1. Pricing power. Customers are paying 2x+ more per MW than a year ago. Demand is still outrunning supply.
2. Every delayed MW makes existing capacity more valuable.
That's exactly why $IREN isn't rushing to sign its remaining capacity.


Citizens: Neoclouds
"CoreWeave has the largest contracted platform and the most future capacity to reprice; Nebius already shows the rate reset in agreements signed at $20–$25 million/MW, with customers prepaying 50–60% of the associated capex; and IREN shows the progression from roughly $10 million/MW on its original Microsoft agreement to above $20 million on newer contracts."
"We are more positive on the Neocloud business model in the near-to-intermediate term. The equities and credit have repriced around the capital required to deliver the build, but demand continues to exceed available supply, delivery remains back-end loaded, and the newest contracts are being signed at higher rates."
$NBIS $IREN $CRWV

$WULF CEO @PaulBPrager has been direct and vocal on X as neoclouds face financing questions.
Recently he stated TeraWulf is not a neocloud. It's an energy infrastructure company.
Do you want more CEOs speaking up on X?
Or does it start to look like CEOs trying to save a falling stock?

@elonmusk may be right that we'll see unfinished data centers. But not all developers operate the same way.
$WULF follows a disciplined approach:
1. Identify sites with demonstrated customer interest.
2. Secure power from investment grade utilities.
3. Lock down specs, construction costs and schedules through GMP EPC contracts.
4. Secure long-term customer commitments backed by investment grade credit.
5. Arrange financing before committing to major construction.
We may move dirt early, but we don't build on spec.
I suspect we'll see projects stall because of inadequate capital, weak counterparties, execution misses, or regulatory hurdles. For experienced infrastructure developers with strong balance sheets, that creates opportunity.
What others call stranded assets, we may call a development pipeline. @PSInvestor @GavinSBaker
Microsoft offering buyouts to ~27% of its workforce is incredibly bullish for AI infrastructure.
But if a quarter of workers everywhere get replaced by agents, who's left to pay for the AI subscriptions?

BREAKING: Microsoft, $MSFT, is offering buyouts to 60,000 workers as part of the company’s efforts to cut costs amid AI adoption, per Bloomberg.
Personnel on select teams in the US, Canada, India, and the UK at a vice president level and below will be eligible.
This reflects ~27% of Microsoft's total workforce.
Calling this chart bullish is making the chart fit your thesis.
I'm bullish on $NBIS long term. The chart tells a different story.
I'm not ruling out $135 from a technical standpoint. That's the April breakout zone before the run to $300.
I call the chart as I see it, not to fit my thesis.


Robotics will require substantially more memory than chat-based AI, even more than agentic AI.
Interesting that Elon mentions RAM here.
Bullish $MU.


