

Senior Equity Analyst at ByteTree | CFA Charterholder | Focused on quality investing | Views my own, not investment advice.
London, England
Joined March 2019
- Tweets4.7K
- Following500
- Followers1.1K
- Likes8.2K





Pinned Tweet
“A great business at a fair price is superior to a fair business at a great price… The investment game always involves considering both quality and price, and the trick is to get more quality than you pay for in price. It’s just that simple." - Charlie Munger
@ByteTree Quality is an investment research service which does exactly that.
#Quality #Investing
bytetree.com/bytetree-qualit…

Kit Winder, CFA retweeted
Great note by @FTAlphaville on the different ways to slice and dice French debt metrics. Firstly, converting it into constant currency to make intl rates more comparable, and then looking at spreads over the overnight funding rates, showing how small the current crisis is compared to Greece in the early 2010s.
This is a seismic flicker at the moment - a warning - but not an earthquake (yet).
In the end, perhaps what matters most is how much of a country’s GDP goes towards interest payments. France has quite a long average maturity (8.5yrs) sparing it a degree of urgency. And despite the last few weeks, France’s EU-leading govt spending and debt/GDP levels, the US and Italy are still set to spend a higher proportion of their economic product on paying off interest.
ft.com/content/9aa4549e-26f4… How nervous are bond markets about France?

Haven’t even listened yet, that’s how sure I am this will be worth sharing…

I caught up on Friday with my friend and business partner Anatole @kaletsky for our weekly Gavekal zoominar. We were supposed to discuss how sustainable the AI capex spending boom would prove to be in the face of rapidly rising corporate bond yields? But given the headlines on France, on the Middle-East and on the growing likelihood of a peace deal between Russia and Ukraine, we struggled to stay on track…
I asked the @gavekal editors to remove the locks on the podcast…
research.gavekal.com/content…
Bill Ackman’s Ground Rules
(As per his Knowledge Project interview with @shaneparrish)
- Large cap, liquid companies
- Simple predictable businesses
- Free cash flow generative
- Great management teams
- No short selling
They’re looking for the best companies in the world with the most durable moats run by the best management teams.
IMO the first rule is underestimated by many.

Great note by @FTAlphaville on the different ways to slice and dice French debt metrics. Firstly, converting it into constant currency to make intl rates more comparable, and then looking at spreads over the overnight funding rates, showing how small the current crisis is compared to Greece in the early 2010s.
This is a seismic flicker at the moment - a warning - but not an earthquake (yet).
In the end, perhaps what matters most is how much of a country’s GDP goes towards interest payments. France has quite a long average maturity (8.5yrs) sparing it a degree of urgency. And despite the last few weeks, France’s EU-leading govt spending and debt/GDP levels, the US and Italy are still set to spend a higher proportion of their economic product on paying off interest.
ft.com/content/9aa4549e-26f4… How nervous are bond markets about France?
Kit Winder, CFA retweeted

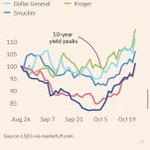
Huge move in high beta/low volatility yesterday. Quality stocks doing what they should when the wind picks up.

First Citrini, now Robert Armstrong in the FT.
Looking to hedge falling tech? Markets are telling you that cheap consumer staples is a good place to look. These are American, but Europe has many excellent options too…


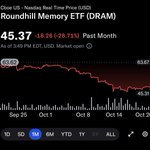
The memory chip ETF $DRAM is now down 30% in a month after failing to make a new high (absolute or relative).


Alpha breadth - key concept.
No of stocks beating the world index in green. Most stock neutral. Many stocks red - underperforming $ACWI.
Alpha is rare.


Kit Winder, CFA retweeted

Right now, the biggest risk to financial markets is an oil shock, as it impacts everything. #CrudeOil is heading back towards all-time highs, and US WTI is closing the gap with Brent. The world’s oil problem is becoming a US problem too.
Meanwhile, another concern is market concentration.
📈 The world’s 100 largest companies now account for 43% of the global market cap. That level of concentration is rare and usually appears only at major market peaks.
Eventually, that concentration will reverse. We saw major rotations in 1975, 2003, and 2009, and the latest market rotation may already be underway. This is when the real opportunities kick in.
This and more in our latest update of The Multi-Asset Investor by @AtlasPulse - link in reply 👇
#OilPlay #OilShock #BRENTCRUDE

With all the neocloud spreads exploding, CDS volumes also jumping (front page of FT), the CGT $5.5 trillion capex question, GMO’s note on the IPOs draining market liquidity, Anthropic’s revenue figure disappointing, Korea making new lows, and their hot new IPO flopping last night….
It’s starting to feel like the AI narrative supertanker is finally shifting gears.

Significant if true.
Claims $MSFT don’t appear to have turned all their GPU purchases into actual, completed data centres. Mostly chips sit in warehouses awaiting construction in years to come.
$NVDA revenues boosted by these sales, which are for future projects, not ones that have swiftly come online…

Free newsletter: I estimate that ~50% of AI chip sales - $200bn to $300bn+ - are sitting in warehouses, with NVIDIA selling hundreds of billions of GPUs years in advance. Data centers take way longer to build than hyperscalers are leading us to believe.
wheresyoured.at/wherere-all-…

$UBER says is an employment company, not a taxi company.
This is tough to square with their AV ambitions, but it does play that role currently in Brazil…


