

AI, semiconductor & quantum research for investors Intel | Foundry | Memory | Advanced Packaging Founder, Roaring Fork Research
Ohio
Joined October 2024
- Tweets8.6K
- Following864
- Followers1.5K
- Likes23.7K




Pinned Tweet
🧵 The part of Intel's foundry strategy most investors will never talk about.
$INTC just opened a new 107,000 sq ft photomask facility with a Class 1 cleanroom.
At first glance, that sounds boring.
It isn't.
Photomasks are essentially the templates used to print transistor patterns onto wafers. As nodes get smaller, the masks become dramatically more complex and expensive.
This facility is being built to support Intel's future roadmap, including 18A, 18A-P, and eventually 14A.
Here's the part I think matters.
Advanced EUV systems are incredibly powerful, but the masks don't last forever. Over time they degrade, get damaged, and need to be replaced.
If you can't replace them quickly, production slows.
That means a mask shop isn't just manufacturing infrastructure.
It's production insurance.
Intel also has an advantage that doesn't get discussed enough.
Through IMS Nanofabrication, Intel is the only major chipmaker that owns the company building the world's leading multi-beam mask writers.
Instead of writing masks with a single electron beam, IMS systems use over 262,000 beams simultaneously.
Faster mask creation.
Higher throughput.
Less risk of becoming a bottleneck.
Most investors are focused on foundry customers, yield numbers, and whether Intel can win share from TSMC.
Those things matter.
But none of it works without the infrastructure behind it.
This looks like another piece of Intel quietly building the ecosystem needed to support advanced manufacturing on U.S. soil.
The market is watching the fabs.
Intel is investing in everything that keeps the fabs running.

Steven Martin retweeted

Q3季度很多机构加仓买入了INTC


𝗜𝗡𝗧𝗖 𝗣𝗼𝘀𝘁 𝗠𝗮𝗿𝗸𝗲𝘁
November 11, 2026
𝗠𝘆 𝗿𝗲𝗮𝗱
It was a good day for Intel. Shares rose 7.5% to $62.50 at the close as the broader AI and chip trade rebounded after CoreWeave’s strong results and higher outlook.
The stock gave back part of the gain after hours.
$INTC really needs about a week of this kind of gains but its a start. Intel still has to turn strong server demand into shipments and protect margins. The foundry is cutting loses every quarter. This time it was over $200 million. That will add up very fast.
Sources: CoreWeave Q3 release, Nov. 10; Intel Q3 release, Oct. 29.

Thank you @HunterAllen4 I made enough from your tip to pay 5 years worth of your subscription to telegram on this stock
$BW 2nd great day in a row. I guess the backlog and the data center have been noticed!!! See that @HunterAllen4 take a
Victory lap!!!
3
6
262
𝗕𝗪 𝗣𝗼𝘀𝘁 𝗠𝗮𝗿𝗸𝗲𝘁
𝗡𝗼𝘃𝗲𝗺𝗯𝗲𝗿 𝟭𝟭, 𝟮𝟬𝟮𝟲
𝗠𝘆 𝗿𝗲𝗮𝗱:
Babcock & Wilcox supplies boilers, steam turbines and other equipment that utilities, industrial customers and data centers use to generate power.
The electrical demand is lifting its opportunities. They need to keep their momentum and get revenue from the Data Center coming in as soon as possible.
$BW closed at $4.84, up 8.04%, after trading between $4.80 and $5.29. Its around 49% above the November 6 close.
𝗪𝗵𝗮𝘁 𝗰𝗵𝗮𝗻𝗴𝗲𝗱
Q3 revenue rose 109% to $290.8 million. Base Electron contributed $77.8 million. Adjusted EBITDA rose 88% to $17.7 million.
Parts and services bookings set a record. Total bookings were $227.9 million and backlog reached $2.5 billion.
That backlog needs explained. The $2.4 billion Base Electron project is a major contributor. Babcock & Wilcox’s $16 billion pipeline is potential work, not contracted revenue.
Management expects 62% of current backlog to be recognized after 2027.
The North Dakota project is four 300 MW gas fired plants, with commercial operation targeted for 2030.
Separately, BW has an agreement with Siemens Energy to begin work on 20 steam turbine sets totaling 1 GW for its FastPower program. No customer was named.
Management discussed possible $200 million to $500 million bookings in Q4 or early 2027, while stressing the deals are not signed. Needham kept its Buy rating but cut its target from $20 to $15.
𝗪𝗵𝗮𝘁 𝗿𝗲𝗺𝗮𝗶𝗻𝘀 𝘂𝗻𝗽𝗿𝗼𝘃𝗲𝗻
Q3 net income included an $85.1 million noncash warrant gain. Adjusted net income was $4.8 million. Operating cash flow used $130.3 million in the first nine months.
Reaching the $80 million to $105 million 2026 EBITDA target requires $24.5 million to $49.5 million in Q4.
The company says its EBITDA targets are not performance guidance. Its filing also says material weaknesses in internal controls remain unremediated.
𝗪𝗵𝗮𝘁 𝗜’𝗺 𝘄𝗮𝘁𝗰𝗵𝗶𝗻𝗴
Can Babcock & Wilcox turn project growth into cash while meeting its 2026 target? That is my question.
Sources: @HunterAllen4 first told me about BW Babcock & Wilcox Q3 release, 10 Q and earnings call, November 9, 2026; Siemens Energy agreement announcement, August 11, 2026; Needham rating update, November 10, 2026; market data, November 11, 2026.
🤖 Made with AI

𝗜𝗢𝗡𝗤 𝗗𝗮𝗶𝗹𝘆 𝗣𝗼𝘀𝘁 𝗠𝗮𝗿𝗸𝗲𝘁
𝗡𝗼𝘃𝗲𝗺𝗯𝗲𝗿 𝟭𝟭, 𝟮𝟬𝟮𝟲
𝗣𝗿𝗶𝗰𝗲 𝗔𝗰𝘁𝗶𝗼𝗻
$IONQ closed around $34.06, down about 2.6%.
𝗠𝘆 𝗿𝗲𝗮𝗱
IonQ has the interest of commercial and governments. Investors still need to see that growth will be profits.
Q3 revenue was strong. Nearly half came from SkyWater, so the 336% year over year increase reflects the acquisition as well as growth in IonQ’s platform business.
𝗪𝗵𝗮𝘁 𝗖𝗵𝗮𝗻𝗴𝗲𝗱
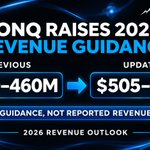
Q3 revenue reached $173.8 million, up 336%. IonQ raised 2026 revenue guidance to $505 million to $515 million, from $450 million to $460 million.
Remaining performance obligations rose to $1.2 billion, but that figure includes funded and unfunded amounts.
IonQ says its Superion 256 capacity for 2027 is sold out, with 2028 orders beginning to fill.
NVIDIA plans to install a Superion 256 at its research center.
DARPA Stage C, worth up to $300 million if fully awarded, is another important opportunity.
𝗧𝗵𝗲 𝗖𝗼𝗻𝘀𝘁𝗿𝗮𝗶𝗻𝘁
IonQ reported $3.7 billion in cash and investments after its October $2 billion offering. It also used $570 million in operating cash during the first nine months of 2026.
Elisity broadens the security business, but IonQ issued $1.15 billion in stock at closing, with up to $150 million more tied to performance milestones.
𝗦𝗼𝘂𝗿𝗰𝗲𝘀
IonQ Q3 release and 10 Q, November 5
IonQ Elisity filing, November 5
IonQ investor updates, November 10 and 11
Market data, November 11
🤖 Made with AI

4
8
475
𝐊𝐄𝐄𝐋 𝐏𝐨𝐬𝐭 𝐌𝐚𝐫𝐤𝐞𝐭 𝐑𝐞𝐩𝐨𝐫𝐭 | 𝟏𝟏.𝟏𝟏.𝟐𝟔
𝐌𝐲 𝐫𝐞𝐚𝐝
KEEL rose with the AI infrastructure niche, The long term case still depends on turning secured power into signed contracts and revenue but with demand like CoreWeave announced that makes it feel more likely.
𝐏𝐫𝐢𝐜𝐞 𝐚𝐜𝐭𝐢𝐨𝐧
$KEEL closed at $2.07, up 8.38%, on 19.65 million shares. Volume was below the recent 10 day average, and the close remains below the $2.10 level from November 4.
𝐒𝐢𝐭𝐞 𝐩𝐫𝐨𝐠𝐫𝐞𝐬𝐬
Keel reports 478 MW of secured capacity across Moses Lake, Sharon and Panther Creek. Construction began at Moses Lake in September, with first HPC revenue expected in 2027. The Pennsylvania substations are targeted for 2027 energization, with revenue expected to begin in early 2028, subject to lease timing.
Expansion studies could raise secured capacity from 478 MW to 1.928 GW. Those studies are due in Q1 2027. That is potential capacity, not already secured power.
𝐂𝐚𝐩𝐢𝐭𝐚𝐥
Keel had $780 million in unrestricted cash as of November 4. Management says that covers pre lease spending and cash SG&A through 2028, with no expected external financing before a lease.. PowerSecure’s Moses Lake agreement is for backup resiliency.
Sources: ChartExchange and Yahoo Finance, Nov. 11; Keel Q3 release, 10 Q and call, Nov. 5; Southern Company, Sept. 9; Keel 8 K, Nov. 10.
🤖 Made with AI

𝗜𝗡𝗧𝗖 𝗣𝗼𝘀𝘁 𝗠𝗮𝗿𝗸𝗲𝘁
November 11, 2026
𝗠𝘆 𝗿𝗲𝗮𝗱
It was a good day for Intel. Shares rose 7.5% to $62.50 at the close as the broader AI and chip trade rebounded after CoreWeave’s strong results and higher outlook.
The stock gave back part of the gain after hours.
$INTC really needs about a week of this kind of gains but its a start. Intel still has to turn strong server demand into shipments and protect margins. The foundry is cutting loses every quarter. This time it was over $200 million. That will add up very fast.
Sources: CoreWeave Q3 release, Nov. 10; Intel Q3 release, Oct. 29.
🤖 Made with AI
$BW 2nd great day in a row. I guess the backlog and the data center have been noticed!!! See that @HunterAllen4 take a
Victory lap!!!
Ok, I have some money burning a hole in my pocket.
I would like to hear what stock or etf you would recommend I pick up today. I would prefer a fairly quick flip.
4
12
358
$NBIS is up 18%, $IREN is up almost 9%, $KEEL is up 12% looks like the market might be catching on to the shortage of data centers with secured power.
After all if you have demand for 10 times more than you have capacity for it’s a great problem to have!
AI Compute Demand Is Outrunning Supply
My read
CoreWeave’s 10 to 1 demand comment is a huge catalyst for the whole AI infrastructure trade. CEO Michael Intrator said qualified customer demand is ten times available capacity through the end of 2027. He also said CoreWeave has sold the infrastructure it has put on the market, with strong demand already forming for 2028.
Nebius management reported that demand continues to outpace supply, meaning virtually no idle connected capacity sits unallocated for long.
That supports the case for stronger pricing and better lease terms where companies can deliver capacity.
Who could benefit
$KEEL is negotiating leases across three near term sites and has started construction at Moses Lake. They have over 300mw of power with existing agreements. The opportunity is clear for them.
$IREN has over 5GW of secured or contracted power. They could be a big player in 2027.
$NBIS raised its year end 2026 contracted power target to 5 GW of connected power by the end of 2026. Some of this active capacity is pre committed to anchor customers such as Microsoft and Meta.
The powered shell story has proof points too. APLD reported 1.41 GW of contracted capacity across its campuses, while CIFR has started recognizing HPC lease revenue and increased Barber Lake’s contracted revenue to about $9.1 billion.
CoreWeave’s and Nebius demand does not automatically become another company’s lease. The winners will be the ones that turn power and construction into signed contracts,

$KEEL is up 12% currently. I guess that statement from the $CRWV CEO about 10 times more demand than supply is hitting today!
𝗞𝗘𝗘𝗟 Daily Premarket
November 11, 2026
$KEEL has power. CoreWeave just announced they are sold out of capacity for 2027. CoreWeave's CEO Michael Intrator confirmed that qualified customer demand outstrips CoreWeave's available capacity through 2027 by a ratio of 10-to-1. This could help everyone in the neo and powered shed niche. However the lease still hasn't happened . Management withdrew its goal of signing three leases by year end and no longer gives a lease date. Site progress matters but the market needs to see a lease.
On a brighter note a director just purchased 15,000 shares Yes it wasn't a huge number but it is still notable.
𝗠𝗮𝗿𝗸𝗲𝘁
KEEL closed Tuesday at $1.91, down 2.55%, after trading between $1.83 and $2.01. Around 7:58 p.m. ET, one quote showed $1.957, roughly 2.4% above the close. The stock remains about 9% below its November 4 close.
𝗪𝗵𝗮𝘁 𝗺𝗮𝘁𝘁𝗲𝗿𝘀
As is well known do to converting from a Bitcoin miner, Q3 revenue fell 59% year over year to $27.6 million. Adjusted EBITDA was negative $27.4 million. Keel sold 2,520 Bitcoin for about $192 million and had no revenue generating HPC capacity in service.
At September 30, it had $815.8 million in cash and $1.02 billion in long term debt. It reported about $780 million in unrestricted cash on November 4. At $1.91, market value was about $1.18 billion and estimated enterprise value about $1.39 billion.
𝗖𝗮𝘁𝗮𝗹𝘆𝘀𝘁 𝗮𝗻𝗱 𝘁𝗲𝘀𝘁
Keel has 478 MW of near term capacity across Moses Lake, Sharon and Panther Creek.
Expansion studies could lift secured capacity toward 1.9 GW, but that remains potential, with results expected in Q1 2027. Moses Lake construction is underway, with energization and first HPC revenue expected in 2027. Pennsylvania revenue depends on lease signing, construction and delivery.
Keel needs a signed deal with disclosed customer with details.
A November 10 filing says General Counsel and Corporate Secretary Rachel Silverstein left effective November 4; no reason was given.
Sources: KEEL Q3 10 Q, earnings release and prepared remarks, November 5; SEC Form 8 K and Form 4, November 10; Yahoo Finance and ChartExchange, November 10.


Steven Martin retweeted

🚨 FUTURE LEADER RADAR | NOVEMBER 11, 2026
THE THEMES HAVE THE BETTER EVIDENCE. THE STOCKS ARE STILL TRYING TO CATCH UP.
The Market Strength Radar is finding a growing pool of stocks that have not fully participated in the strength of their supporting themes.
Some have constructive price structures. Others are still repairing.
But the central problem remains the same.
A strong theme does not automatically create a strong stock.
Healthcare and biotech are showing constructive supporting relative strength. Software has positive medium term evidence but weaker recent momentum. Technology remains under pressure.
That means I cannot treat every potential catch up candidate equally.
📊 WHAT THE FULL WATCHLIST IS SHOWING
193 source entries across 191 unique stocks.
Yesterday's review contained 189 unique stocks.
The largest concentrations:
🟢 $IGV: 26 software stocks
🔵 $XBI: 25 biotech stocks
🟢 $XLV: 25 healthcare stocks
🔵 $XLK: 24 technology stocks
These four groups contain 100 of the 191 unique stocks, approximately 52%.
The future participation pool remains concentrated in a few major areas.
And the two additional unique stocks do not prove that market participation is improving.
Some stocks may be entering this category because they are falling behind their themes, not because their charts are improving.
🔎 THE IMPORTANT DIFFERENCE
$LLY has a strong uptrend, but its current location is stretched.
$IDXX is still repairing and is also stretched.
Both have supportive healthcare theme evidence.
But neither automatically offers a clean current entry.
The theme is one part of the equation.
The stock's own relative strength and price structure still need validation.
🎯 MY FOCUSED FUTURE LEADER RADAR
The experimental V3.1 selection contains 30 stocks for manual chart review.
🟢 10 Best Positioned to Catch Up
🔵 20 Close to Catch Up Confirmation
🟡 0 Early Catch Up Candidates
Ten have strong uptrends, but sixteen still have repairing chart structures.
Seven are stretched.
The focused list has improved slightly since yesterday, but it is far from uniform technical confirmation.
All 30 remain under conditional broader market conditions.
📋 TRADINGVIEW WATCHLIST
30 unique stocks from the larger 191-stock universe.
Original experimental V3.1 selection order preserved.
TradingView copy and paste:
NYSE:BB,NYSE:EOG,NASDAQ:UTHR,NASDAQ:PRME,NASDAQ:CLOV,NYSE:JNJ,NASDAQ:GLBE,NASDAQ:KARO,NYSE:UNH,TSE:4417,NASDAQ:VRSK,NASDAQ:BSY,NYSE:LLY,TSE:KXS,BME:AMS,NASDAQ:OLED,TSE:AIF,NYSE:ABT,NASDAQ:IDXX,NASDAQ:ADSK,NASDAQ:TTAN,NYSE:KVYO,NYSE:BAM,NYSE:AON,NYSE:ZTS,NASDAQ:ISRG,NASDAQ:CLBT,NASDAQ:INTU,NASDAQ:ATGL,NASDAQ:INVE
📌 MY CURRENT READ
The future participation pool is large.
Several supporting themes have established constructive relative strength.
But individual stock confirmation is still inconsistent.
I am interested in stocks that begin matching the performance of their themes while establishing healthier price structures.
I am not assuming that every lagging stock will eventually catch up.
This is a relative strength screening system, not a buy list.
My market journal, not financial advice.
🤖 Made with AI


𝗜𝗡𝗧𝗖 𝗗𝗮𝗶𝗹𝘆 𝗣𝗿𝗲 𝗠𝗮𝗿𝗸𝗲𝘁
𝗡𝗼𝘃𝗲𝗺𝗯𝗲𝗿 𝟭𝟭, 𝟮𝟬𝟮𝟲
𝗠𝘆 𝗥𝗲𝗮𝗱
A firmer chip tape gives Intel some support this morning, but it does not change the setup. Server demand is strong. Intel still has to ship enough product to meet that demand. while PC weakness and supply limits weigh on results.
𝗣𝗿𝗶𝗰𝗲 & 𝗧𝗮𝗽𝗲
INTC closed Tuesday around $58.13, down 2.09%. Price feeds vary by a few cents. An extended hours feed showed about $58.80 around 8 p.m. ET, up roughly 1.2%.U.S. futures were modestly higher overnight, while hot inflation and rate concerns remained a risk for tech shares.
𝗘𝗮𝗿𝗻𝗶𝗻𝗴𝘀 𝗢𝘃𝗲𝗿𝗵𝗮𝗻𝗴
Q3 revenue grew 21% to $16.5B. Non GAAP EPS was $0.52. DCAI rose 78% to $7.3B, while Client Computing and Physical AI fell 5% to $8.1B.
Q4 guidance was the problem: revenue of $15B to $16B, non GAAP EPS of $0.25, and non GAAP gross margin near 38%. Intel expects PC weakness through at least the first half of 2027. Management estimates PC unit market demand could fall about 12% in 2026 and 10% in 2027. In my opinion mainly due to memory prices and the fact they can make more money making higher end chips.
Foundry revenue was $6.7B, but $6.3B was internal sales. External revenue was $411M, primarily from a nonrecurring contract. Foundry lost $1.9B down over $200 million from Q3
𝗡𝗲𝘄𝘀 & 𝗖𝗮𝘁𝗮𝗹𝘆𝘀𝘁𝘀
Intel and Altera plan sensor bridge reference solutions for healthcare, aerospace and defense, and robotics. It supports the edge AI strategy,
The SEC filing confirms Classiq terms of about $1.9B plus up to $350M contingent, with a first half 2027 expected close. Strategic potential is there.
Lip Bu Tan bought 150,000 shares through a family trust for about $9.7M on November 2. Constructive signal, another sign of faith.
𝗪𝗵𝗮𝘁 𝗜’𝗺 𝗪𝗮𝘁𝗰𝗵𝗶𝗻𝗴
Can Intel improve server supply and margins while the PC market weakens? . The next real test is operating performance.
𝗦𝗼𝘂𝗿𝗰𝗲𝘀
Intel Q3 release and 10 Q, October 29 and 30
Intel and Altera announcement, November 10
SEC Form 4, November 4
SEC Classiq disclosure, October 30
Yahoo Finance, ChartExchange and extended hours quote data
Reuters and AP market reports, November 11
Intel IR calendar

𝗞𝗘𝗘𝗟 Daily Premarket
November 11, 2026
$KEEL has power. CoreWeave just announced they are sold out of capacity for 2027. CoreWeave's CEO Michael Intrator confirmed that qualified customer demand outstrips CoreWeave's available capacity through 2027 by a ratio of 10-to-1. This could help everyone in the neo and powered shed niche. However the lease still hasn't happened . Management withdrew its goal of signing three leases by year end and no longer gives a lease date. Site progress matters but the market needs to see a lease.
On a brighter note a director just purchased 15,000 shares Yes it wasn't a huge number but it is still notable.
𝗠𝗮𝗿𝗸𝗲𝘁
KEEL closed Tuesday at $1.91, down 2.55%, after trading between $1.83 and $2.01. Around 7:58 p.m. ET, one quote showed $1.957, roughly 2.4% above the close. The stock remains about 9% below its November 4 close.
𝗪𝗵𝗮𝘁 𝗺𝗮𝘁𝘁𝗲𝗿𝘀
As is well known do to converting from a Bitcoin miner, Q3 revenue fell 59% year over year to $27.6 million. Adjusted EBITDA was negative $27.4 million. Keel sold 2,520 Bitcoin for about $192 million and had no revenue generating HPC capacity in service.
At September 30, it had $815.8 million in cash and $1.02 billion in long term debt. It reported about $780 million in unrestricted cash on November 4. At $1.91, market value was about $1.18 billion and estimated enterprise value about $1.39 billion.
𝗖𝗮𝘁𝗮𝗹𝘆𝘀𝘁 𝗮𝗻𝗱 𝘁𝗲𝘀𝘁
Keel has 478 MW of near term capacity across Moses Lake, Sharon and Panther Creek.
Expansion studies could lift secured capacity toward 1.9 GW, but that remains potential, with results expected in Q1 2027. Moses Lake construction is underway, with energization and first HPC revenue expected in 2027. Pennsylvania revenue depends on lease signing, construction and delivery.
Keel needs a signed deal with disclosed customer with details.
A November 10 filing says General Counsel and Corporate Secretary Rachel Silverstein left effective November 4; no reason was given.
Sources: KEEL Q3 10 Q, earnings release and prepared remarks, November 5; SEC Form 8 K and Form 4, November 10; Yahoo Finance and ChartExchange, November 10.
𝗜𝗢𝗡𝗤 𝗣𝗿𝗲 𝗠𝗮𝗿𝗸𝗲𝘁
𝗡𝗼𝘃𝗲𝗺𝗯𝗲𝗿 𝟭𝟭, 𝟮𝟬𝟮𝟲
𝗠𝘆 𝗥𝗲𝗮𝗱
Gartner recognition and the Carahsoft are another conformation about $IONQ. They continue to show why so many people are excited about their future!
𝗪𝗵𝗮𝘁 𝗖𝗵𝗮𝗻𝗴𝗲𝗱
IONQ closed Tuesday at $34.99, down 0.99%, on about 18 million shares. Gartner named IonQ a “Market Shaper.” The company is exhibiting at Gartner’s Barcelona conference through November 12.
Carahsoft is now IonQ’s public sector distributor. Its procurement support and reseller network may ease agency access to IonQ’s range of products.
𝗧𝗵𝗲 𝗧𝗵𝗲𝘀𝗶𝘀
Q3 revenue rose 336% to $173.8 million. IonQ raised 2026 guidance to $505 million to $515 million.
Its platform segment produced $90.3 million, up 127%; SkyWater supplied $83.5 million, about 48% of total revenue.
Management said 2027 Superion 256 capacity is sold out, with orders beginning to fill for 2028. The $1.168 billion in remaining performance obligations includes funded and unfunded orders. IonQ expects about half to convert to revenue within 12 months.
𝗠𝗮𝗿𝗴𝗶𝗻𝘀 𝗮𝗻𝗱 𝗜𝗻𝘁𝗲𝗴𝗿𝗮𝘁𝗶𝗼𝗻
Cost of revenue excluding depreciation and amortization rose 539%, faster than revenue. Gross profit before that cost fell from 46.7% of revenue a year ago to 21.9% this quarter. Acquisitions and contract mix complicate the comparison, but the market is going to want to see the margins pick up again.
Q3 GAAP net income of $564 million was largely from noncash warrant valuation gains. IonQ lost $1.04 billion from operations in the first nine months. The nine month expense increase included $38.6 million in acquisition transaction and integration costs.
𝗩𝗮𝗹𝘂𝗮𝘁𝗶𝗼𝗻 𝗮𝗻𝗱 𝗦𝗲𝘁𝘂𝗽
At $34.99, the screen reported a market value near $15.1 billion. Using IonQ’s $3.7 billion pro forma cash and investments, the estimated enterprise value is about $11.4 billion. Against screen reported trailing sales near $380 million, that is roughly 40 times sales and 30 times EV to sales.
Latest short interest: 50.63 million shares as of October 30, or 13.38% of the reported float. It was published November 10 and increased from the October 15 settlement. No verified buyout or squeeze catalyst surfaced.
𝗪𝗵𝗮𝘁 𝗜 𝗔𝗺 𝗪𝗮𝘁𝗰𝗵𝗶𝗻𝗴
I would like to see IonQ reach at least $505 million in 2026 revenue and platform growth remains strong. I will be disappointed if it falls short or growth increasingly depends on acquired businesses.
Sources: IonQ Q3 release and quarterly filing, November 5; IonQ Carahsoft release, November 9; IonQ Gartner release, November 10; IonQ Q3 call; StockAnalysis market data; ChartExchange short interest data, October 30 settlement, published November 10.

AI Compute Demand Is Outrunning Supply
My read
CoreWeave’s 10 to 1 demand comment is a huge catalyst for the whole AI infrastructure trade. CEO Michael Intrator said qualified customer demand is ten times available capacity through the end of 2027. He also said CoreWeave has sold the infrastructure it has put on the market, with strong demand already forming for 2028.
Nebius management reported that demand continues to outpace supply, meaning virtually no idle connected capacity sits unallocated for long.
That supports the case for stronger pricing and better lease terms where companies can deliver capacity.
Who could benefit
$KEEL is negotiating leases across three near term sites and has started construction at Moses Lake. They have over 300mw of power with existing agreements. The opportunity is clear for them.
$IREN has over 5GW of secured or contracted power. They could be a big player in 2027.
$NBIS raised its year end 2026 contracted power target to 5 GW of connected power by the end of 2026. Some of this active capacity is pre committed to anchor customers such as Microsoft and Meta.
The powered shell story has proof points too. APLD reported 1.41 GW of contracted capacity across its campuses, while CIFR has started recognizing HPC lease revenue and increased Barber Lake’s contracted revenue to about $9.1 billion.
CoreWeave’s and Nebius demand does not automatically become another company’s lease. The winners will be the ones that turn power and construction into signed contracts,

WAIT... COREWEAVE'S AI CAPACITY IS ALREADY SOLD OUT THROUGH 2027
I've been digging into $CRWV's latest earnings commentary, and some of these numbers are INSANE.
There's a lot more to this story than just the massive debt.
AI DEMAND IS EXPLODING
• Capacity largely sold through 2027
• All 2028 capacity offered so far is also sold
• Qualified demand is 10x available capacity through 2027
• Customers committing over $100M grew more than 2.5x YoY
• Over $9B of infrastructure already built and waiting to go live
NVIDIA GPU PRICES ARE RISING
Here's what really caught my attention:
• Older Nvidia GPU rental rates jumped 30%-50% in Q3
• CoreWeave raised prices around 25% in July and another 10% later in Q3
• Over 130,000 GPUs come off contract in 2027
• Another 170,000 in 2028
Management estimates that renewing these contracts at current prices could generate nearly $10B in additional annualised revenue WITHOUT new CapEx.
That's a massive opportunity if those prices hold.
PROFITABILITY IS THE BIG TARGET
• Adjusted losses expected to fall significantly in 2027
• Targeting adjusted net profit in H1 2028
• Full-year adjusted profitability expected in 2028
• Adjusted EBITDA less interest expense expected to more than double in 2027
BUT WHAT ABOUT ALL THAT DEBT?
This is where we need to be careful.
• 2027 CapEx could remain around $37B–$39B
• Less than $5B in additional parent-level capital expected through 2027
• $5B available through existing loans
• New financing expected to cover over 90% of associated CapEx at around 7%–7.5%
• Over $4B in debt already repaid
Management believes contracted cash flows can cover its planned debt repayments and interest, even without GPU renewals.
Peeps, I genuinely find this fascinating.
The AI demand is clearly there, and rising GPU rental prices could become a huge opportunity.
But spending nearly $40B a year building infrastructure is no joke.
For me, the big question is whether $CRWV can deliver all this capacity, manage its debt and actually achieve profitability in 2028.
Steven Martin retweeted

🚨BREAKING: 🟢 $RKLB 📈📈📈
The Pentagon has issued a $150 million conditional loan commitment to Rocket Lab USA, Inc. to accelerate the production, infrastructure scaling, and launch frequency of its upcoming medium-lift Neutron rocket.
Let’s get @insidegadsmind to 800!! He is 4 short. He is very supportive and has great posts!!!

$NVDA reports in exactly one week.
Down 26% from its high. CEO under investigation. AMD eating its lunch.
You know what happens if they beat, right?